
Antibody Drug Conjugates Contract Manufacturing Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 12.02 Billion |
| Market Size (2031) | USD 20.54 Billion |
| Growth Rate (2026 - 2031) | 11.31 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Antibody Drug Conjugates Contract Manufacturing Market Analysis by 麻豆视频
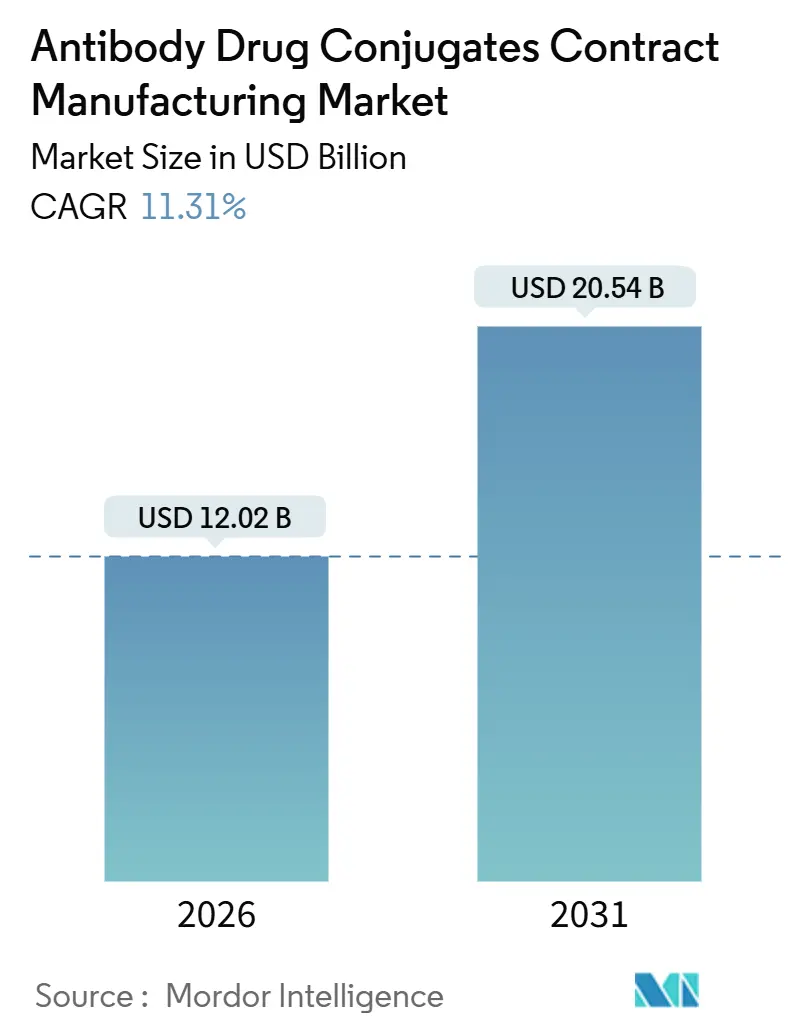
The Antibody Drug Conjugates Contract Manufacturing Market size is estimated at USD 12.02 billion in 2026, and is expected to reach USD 20.54 billion by 2031, at a CAGR of 11.31% during the forecast period (2026-2031).
Capacity additions in high-potency suites, the capital burden of in-house builds, and the growing clinical pipeline of next-generation conjugates are steering sponsors toward external partners. Premium pricing for OEB 4-5 containment, regulatory convergence under ICH Q13, and the need to balance speed with quality are reinforcing the value proposition of specialized CDMOs. Consolidation among innovators - illustrated by Pfizer’s Seagen and AbbVie’s ImmunoGen deals - has expanded outsourced volumes even as acquirers rationalize legacy plants. Investments by Lonza, Samsung Biologics, and WuXi Biologics signal confidence that unmet demand for flexible clinical and commercial capacity will persist through the forecast window.
Key Report Takeaways
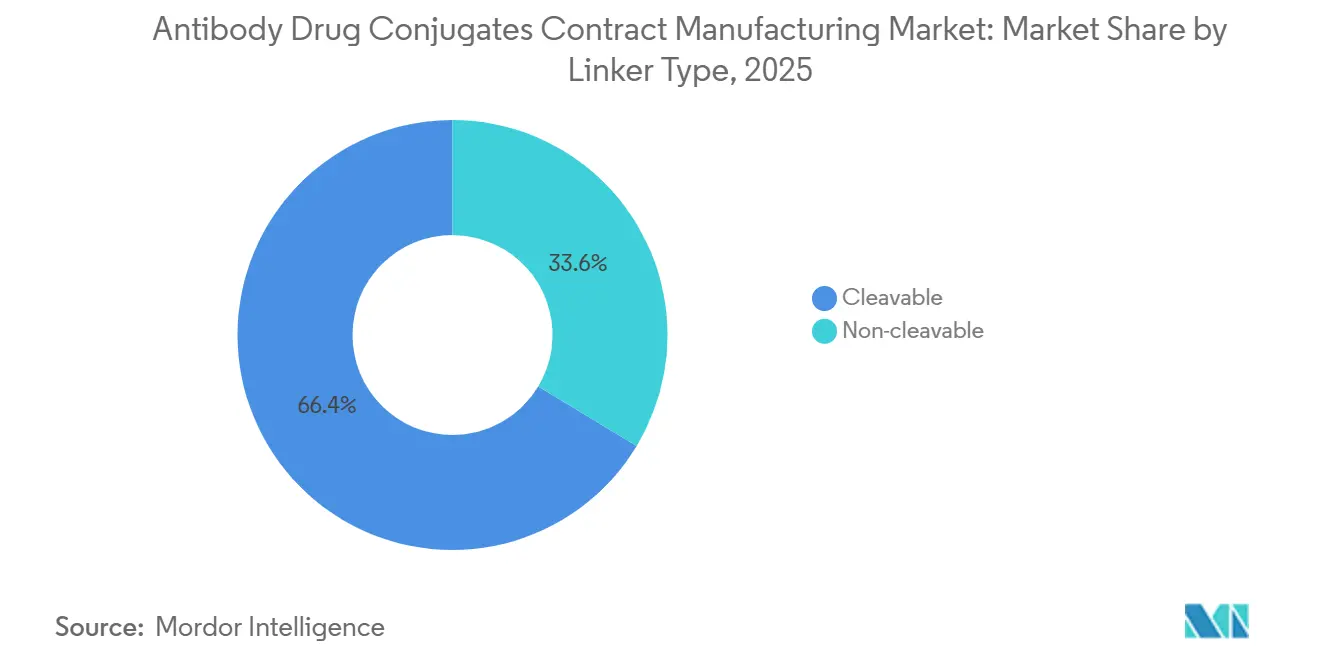
- By linker type, cleavable chemistries held 66.37% of antibody drug conjugates contract manufacturing market share in 2025, while non-cleavable formats are projected to post a 15.25% CAGR to 2031.
- By therapeutic area, solid tumors led with 57.94% revenue share in 2025; autoimmune and infectious-disease programs are forecast to expand at a 14.45% CAGR through 2031.
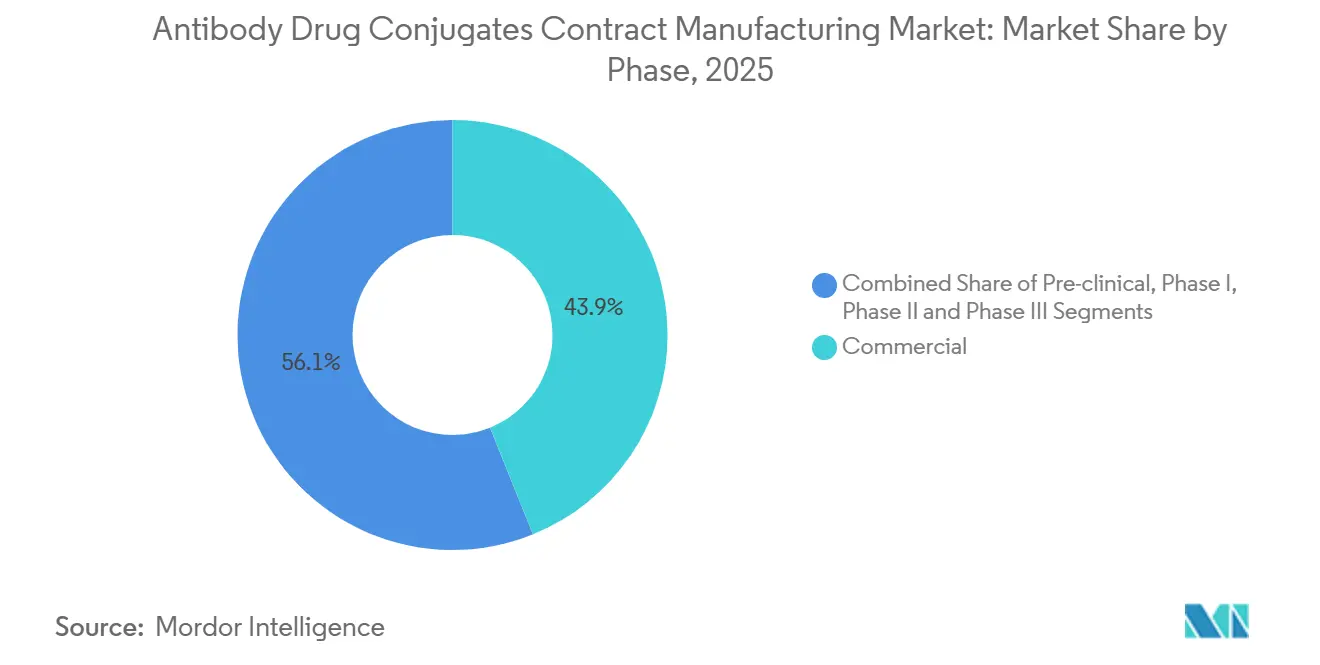
- By phase, commercial manufacturing captured 43.89% of the antibody drug conjugates contract manufacturing market size in 2025 and is advancing at a 13.68% CAGR to 2031.
- By service type, cGMP conjugation and drug-linker production generated 39.73% of revenue in 2025, whereas fill-finish services will accelerate at a 14.83% CAGR through 2031.
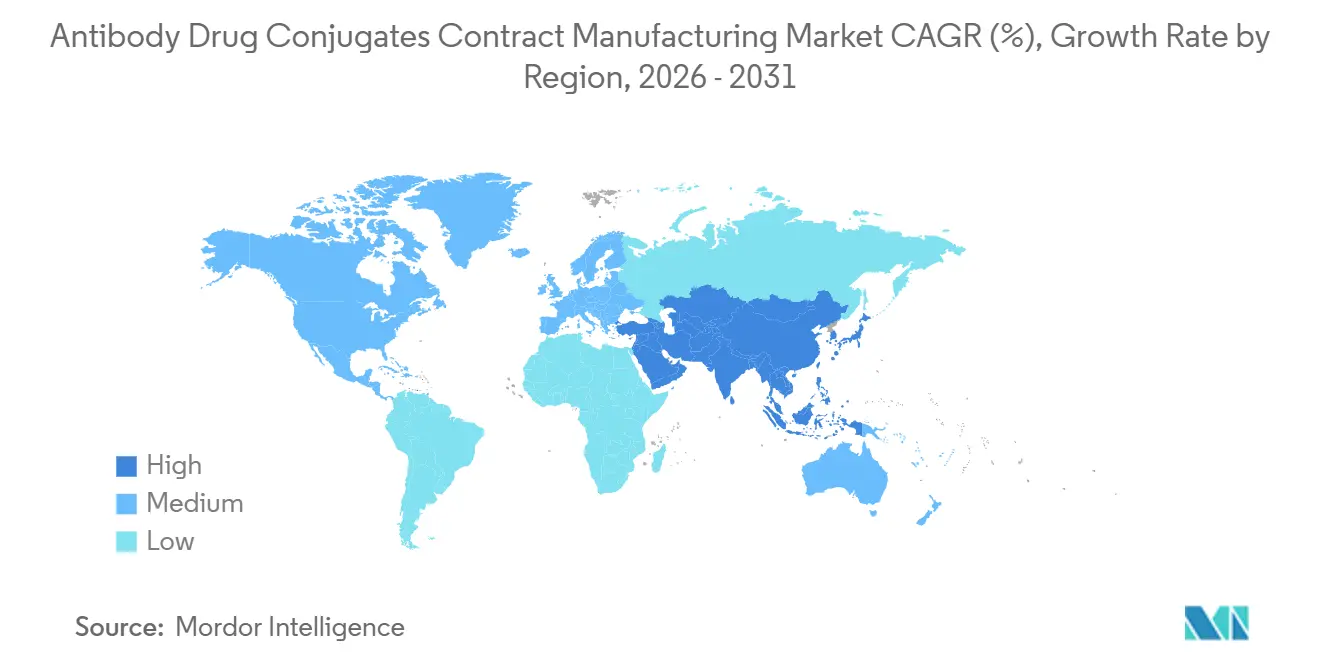
- By geography, North America retained 44.68% share in 2025, but Asia-Pacific is poised to grow at a 14.04% CAGR on the back of large-scale greenfield builds.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Antibody Drug Conjugates Contract Manufacturing Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surging oncology incidence & larger addressable patient pool | 2.3% | Global, with highest concentration in North America & Europe | Medium term (2-4 years) |
| Big-pharma pivot to outsourced biologics manufacturing | 2.8% | Global, led by North America & Europe, expanding to APAC | Short term (≤ 2 years) |
| Expansion of ADC clinical pipeline beyond oncology | 1.9% | North America & Europe early adopters, APAC following | Long term (≥ 4 years) |
| Capacity constraints at HPAPI facilities triggering premium pricing | 1.7% | Global, acute in North America & Europe | Short term (≤ 2 years) |
| Emergence of site-specific conjugation & continuous flow enabling faster tech-transfer | 1.5% | North America & Europe leaders, technology transfer to APAC | Medium term (2-4 years) |
| Regulatory convergence (ICH Q13, Annex 1 rev.) easing multi-site release testing | 1.1% | Global, harmonizing North America, Europe, APAC regulatory pathways | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Surging Oncology Incidence & Larger Addressable Patient Pool
Global cancer cases reached 20 million in 2024, and WHO projects a rise to 35 million by 2050, sustaining demand for safer targeted therapies.[1]World Health Organization, Cancer Fact Sheet, World Health Organization, who.intEnhertu’s 2024 approval for HER2-low breast cancer validated biomarker-driven expansion and added 1.2 million eligible patients per year.[2]U.S. Food and Drug Administration, “FDA Approves Enhertu for HER2-Low Breast Cancer,” U.S. Food and Drug Administration, fda.gov CDMOs responded by installing multi-product conjugation suites sized for 50-200 kg batches, bridging late-stage and early commercial needs, exemplified by Lonza’s twin 1,200 L reactors at Visp scheduled for 2028 service.
Big-Pharma Pivot to Outsourced Biologics Manufacturing
A BCG review found that 70-80% of developers lacked in-house conjugation capacity in 2024. Pfizer halted a USD 350 million build in Everett and instead signed a USD 1.24 billion contract with Samsung Biologics, prioritizing external scale while focusing internal plants on development. AstraZeneca’s Singapore site, slated for 2029, will cover only early phase work, reserving commercial supply for CDMOs.
Expansion of ADC Clinical Pipeline Beyond Oncology
Developers opened 18 Phase I/II autoimmune trials in 2024, applying cytotoxic payloads to selective B-cell depletion. Gilead’s USD 900 million pact with Sutro pursues folate receptor alpha in ovarian cancer and Crohn’s disease under one IND, demonstrating platform flexibility. CDMOs are expanding analytical offerings to characterize immune-modulating effects beyond standard cytotoxicity panels.
Capacity Constraints at HPAPI Facilities Triggering Premium Pricing
Fewer than 25 CDMOs operate OEB 4-5 suites. Samsung’s USD 1.24 billion award in October 2024 carried a 40% per-kilogram premium over mAb pricing. MilliporeSigma tripled capacity in St. Louis yet sold out 2026-2027 slots within three months. Scarcity is steering sponsors toward continuous processes that cut cycle time by a week, although regulatory uptake is still evolving.
Restraints Impact Analysis of Antibody Drug Conjugates Contract Manufacturing Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cytotoxic payload supply bottlenecks & hazardous-material logistics | -1.4% | Global, acute in North America & Europe due to regulatory scrutiny | Short term (≤ 2 years) |
| High COGS owing to multi-modal analytical release requirements | -1.2% | Global, with higher impact in North America & Europe | Medium term (2-4 years) |
| Tight environmental rules on solvent & waste incineration for HPAPIs | -0.9% | Europe & North America, emerging in APAC | Medium term (2-4 years) |
| Patent cliffs for first-generation ADCs tempering legacy line utilisation | -0.7% | North America & Europe, limited APAC impact | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Cytotoxic Payload Supply Bottlenecks & Hazardous-Material Logistics
Fewer than 10 suppliers produce GMP auristatins and maytansinoids, with 18-month lead times in 2024. New IATA rules reclassifying certain payloads as Category 1A carcinogens raised air-freight costs by up to 70%. Daiichi Sankyo’s Shanghai payload plant, set for 2030, reflects vertical-integration efforts to mitigate shortages.
High COGS Owing to Multi-Modal Analytical Release Requirements
ADC lots need 15-20 orthogonal assays, pushing analytical costs to USD 50,000-80,000 per batch.[3]Ronald A. Rader, BioProcess International: Analytical Challenges in ADC Lot Release, BioProcess International, bioprocessintl.com Thermo Fisher’s automated platform trims hands-on time by 40% yet still consumes 72 hours of instrument use. Regulators have granted limited waivers under ICH Q6B for continuous processes, but broader acceptance is pending.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Antibody Drug Conjugates Contract Manufacturing Market Segment Analysis
By Linker Type:
Non-Cleavable Momentum Outpaces Historical LeadersCleavable linkers controlled 66.37% of antibody drug conjugates contract manufacturing market share in 2025, yet non-cleavable systems are forecast to grow 15.25% annually through 2031, outstripping the overall market. The antibody drug conjugates contract manufacturing market size tied to non-cleavable constructs will therefore expand more quickly than cleavable revenue during the period. Developers favor non-cleavable designs for better systemic stability, releasing payload only after lysosomal degradation. Enhertu’s USD 3.1 billion 2024 sales proved that a hybrid approach using membrane-permeable toxins can offset the lower bystander effect seen in first-generation non-cleavables.
CDMOs have invested in flexible conjugation skids that switch between cleavable and non-cleavable chemistries without lengthy changeovers. Lonza’s XpressCys system allows a sponsor to move from early discovery to GMP within a single platform, shortening time to clinic. Cleavable linkers remain essential for hematologic cancers where rapid intracellular release is desirable; however, solid-tumor programs increasingly demand acid-labile and protease-sensitive designs to localize drug activity.


By Therapeutic Area:
Autoimmune Upswing Redraws the MapSolid tumors generated 57.94% of 2025 revenue, but autoimmune and infectious-disease projects are projected to log a 14.45% CAGR to 2031. The antibody drug conjugates contract manufacturing market size tied to autoimmune indications is therefore widening faster than oncology growth alone. Sponsors initiated 18 early-phase autoimmune trials in 2024, betting that selective B-cell ablation can deliver durable remission with intermittent dosing. Solid-tumor demand remains robust, driven by HER2-low, TROP2, and Nectin-4 targets, yet market planners now view non-oncology as the top incremental growth driver.
The autoimmune push requires segregated manufacturing to avoid cross-contamination with high-potency oncology payloads, adding 15-20% to contract pricing. CDMOs willing to dedicate cleanrooms to non-oncology customers stand to command premium margins. Infectious-disease ADCs are nascent, but early venture investment signals future diversification.
By Phase:
Commercial Contracts Dominate Revenue MixCommercial programs accounted for 43.89% of 2025 revenue and will expand at a 13.68% CAGR, cementing their role as the largest contributor to antibody drug conjugates contract manufacturing market size through 2031. Sponsors increasingly lock in five-year supply deals at fixed prices, as seen in Samsung’s record award, passing inflation risk to manufacturers. Late-stage validation runs attract a 20-30% price uplift, motivating CDMOs to allocate scarce HPAPI capacity to near-commercial assets. Early-phase work is more variable and price-sensitive, with Chinese suppliers under-cutting Western peers by up to 40%.
CDMOs counter this price pressure by bundling development, conjugation, and fill-finish under single contracts, reducing tech-transfer friction. Lonza’s Portsmouth-Visp-Stein network exemplifies the integrated model, guaranteeing timeline certainty to sponsors facing competitive pressure.

By Service Type:
Fill-Finish Complexity Spurs Fastest GrowthFill-finish services will grow 14.83% per year through 2031, eclipsing conjugation and linker manufacture even though the latter held 39.73% of 2025 revenue. Pre-filled syringe and autoinjector formats, enabled by FDA draft guidance on combination products, expand the observable market beyond vials. The antibody drug conjugates contract manufacturing market size associated with fill-finish is therefore climbing sharply as containment and sterility requirements add value.
Conjugation remains the cornerstone service. However, the rise of continuous flow and site-specific technologies is shifting value from sheer capacity toward differentiated process know-how. CDMOs offering both legacy stochastic methods and advanced site-specific platforms can serve a broader client mix.
Geography Analysis
North America Antibody Drug Conjugates Contract Manufacturing Market
North America held 44.68% of revenue in 2025, powered by a dense innovator base and ongoing brownfield expansions in Missouri, North Carolina, and Massachusetts. The region’s regulatory environment supports first-to-trial ambitions, keeping average project timelines shorter than in Europe. The antibody drug conjugates contract manufacturing market share held by North America will erode slightly as APAC capacity comes online, but absolute revenue will rise given healthy underlying demand.
APAC Antibody Drug Conjugates Contract Manufacturing Market
Asia-Pacific is set to post a 14.04% CAGR, the fastest among regions. Samsung Biologics’ 256 kL Plant 5 and AGC Biologics’ Yokohama facility together add 350 kL of capacity by 2026, equal to 15% of global supply. Lower labor costs and supportive government incentives underpin competitive pricing, drawing late-stage programs from cost-conscious sponsors.
Europe Antibody Drug Conjugates Contract Manufacturing Market
Europe captured 28% of 2025 revenue, led by Germany, Switzerland, and the United Kingdom. The revised Annex 1 rules have improved operating margins by lowering cleanroom capital outlays, yet divergent post-Brexit filing rules add complexity. Smaller European economies lag due to higher labor costs and less generous R&D tax credits.

Regulatory Landscape
ADCs sit under a hybrid regulatory lens because the antibody is handled under biologics expectations while the drug-linker component and payload can trigger small-molecule style controls. This creates dual-track CMC documentation and inspection readiness requirements for CDMOs. In the United States, FDA issued "Clinical Pharmacology Considerations for Antibody-Drug Conjugates" guidance in March 2024, formalizing expectations for bioanalytical methods, exposure-response, and drug-drug interaction considerations that feed back into release strategy and comparability packages.
For outsourced manufacturing, regulators emphasize control of ADC-specific CQAs such as drug-to-antibody ratio (DAR), drug loading distribution, purity, and linker-related impurities. CDMOs are also expected to provide process validation evidence spanning the mAb, drug-linker, and conjugation steps. Foundational ICH expectations used across regions, for example ICH Q11 for drug substance development and ICH Q5C for stability, increase the analytical burden and stability strategy complexity for CDMOs supporting global filings, reinforcing the need for robust quality systems and data integrity across multi-site supply networks.
Value Chain Analysis
The ADC contract manufacturing value chain connects mAb drug substance production with high-potency payload and linker synthesis, bioconjugation under OEB 4-5 containment, and sterile fill-finish and packaging. This is followed by cold-chain distribution and hazardous-material logistics where applicable. Bottlenecks concentrate in specialized HPAPI handling steps, constrained payload precursor supply, and limited ADC-suitable fill-finish capacity, with additional friction from the need to control DAR and other conjugate-specific CQAs using orthogonal analytics.
CDMOs increasingly bundle upstream biologics, conjugation, and drug product operations to reduce hand-offs, streamline tech transfer, and keep a single quality system across critical steps. Niche specialists still support proprietary linker-payload chemistries. Recent capacity investments underline how capital-intensive the chain is: MilliporeSigma (Merck KGaA) announced a USD 76 million expansion to triple ADC manufacturing capacity in St. Louis (October 2024), and Cohance Lifesciences announced a USD 10 million cGMP bioconjugation suite expansion at its NJ Bio site in Princeton, New Jersey (August 2025). These moves point to continued build-out of domestic hubs and containment-led infrastructure.
Competitive Landscape
The top five CDMOs represented a large share of 2025 revenue, indicating moderate concentration. No single player exceeded a 12% share, reflecting the capital barrier but also the broadening of global capacity. Samsung Biologics set a new benchmark with its USD 1.24 billion bundled contract, signaling buyer appetite for one-stop solutions.
Technology leadership is increasingly decisive. Lonza’s XpressCys, Catalent’s SMARTag, and Thermo Fisher’s continuous flow offering provide differentiation beyond scale. Smaller firms form consortia to compete: Cerbios-Pharma partnered with CARBOGEN AMCIS in 2024 to combine conjugation and analytics under a joint bid model. Emerging Chinese and Indian CDMOs undercut on price but must secure multi-region regulatory track records to win commercial phase contracts.
Antibody Drug Conjugates Contract Manufacturing Industry Leaders
Lonza Group
Samsung Biologics
Piramal Pharma Solutions
Catalent Inc.
WuXi Biologics
- *Disclaimer: Major Players sorted in no particular order

Antibody Drug Conjugates Contract Manufacturing Market Companies Covered in this Report
- Abzena
- AGC Biologics
- Ajinomoto Bio-Pharma Services
- Axplora (Novasep)
- Bora Biologics
- Cambrex Corp.
- CARBOGEN AMCIS
- Catalent
- Cerbios-Pharma
- Emergent Bio Solutions
- FUJIFILM
- Lonza Group
- Merck KGaA (MilliporeSigma)
- Oncotec Pharma Produktion
- Piramal Group
- Recipharm
- Samsung Group
- Sterling Pharma Solutions
- Thermo Fisher Scientific
- Wuxi Biologics
Read Analysis of Antibody Drug Conjugates Contract Manufacturing Companies

Market Opportunities and Future Outlook
Whitespace continues in integrated, end-to-end offerings that connect payload-linker manufacture, cGMP conjugation, and containment-capable fill-finish, since many developers lack in-house conjugation capacity and must manage multi-vendor coordination risk. Capacity investments reinforce the direction of demand: MilliporeSigma (Merck KGaA) committed USD 76 million to triple ADC capacity in St. Louis (October 2024), Cohance Lifesciences committed USD 10 million to add a cGMP bioconjugation suite at NJ Bio in Princeton (August 2025), and Piramal Pharma Solutions unveiled a dedicated payload-linker suite at its Riverview, Michigan facility (May 2026). Together, these investments highlight a preference for vertically connected capabilities.
Technology-driven differentiation is another lever for CDMOs, especially those that can industrialize site-specific conjugation and in-process monitoring to tighten DAR control and reduce batch variability. Fujifilm added proof of strategic focus in March 2026 by investing in VALANX Biotech to integrate Golden Site Technology for site-specific ADC conjugation within its CDMO infrastructure. Axplora has also been integrating commercial-scale lyophilization at Le Mans as part of a EUR 30 million program (reported April 2026), aligning with ADC drug product stability and containment needs and enabling more complex presentation formats.
Recent Industry Developments in Antibody Drug Conjugates Contract Manufacturing Market
- July 2026: Lonza announced an expansion of payload-linker manufacturing capacity at its Visp, Switzerland hub, with the added capacity planned to be operational in 2028. The move strengthens Lonza's position in a constrained part of the ADC supply chain where specialized HPAPI infrastructure and tight impurity control can limit throughput.
- May 2026: Piramal Pharma Solutions unveiled a new payload-linker development and manufacturing suite at its Riverview, Michigan facility. By expanding payload-linker capabilities closer to key North American sponsors, Piramal supports tighter coordination between chemical development, containment operations, and downstream conjugation programs.
- October 2024: MilliporeSigma (Merck KGaA) announced a USD 76 million investment to triple ADC manufacturing capacity at its St. Louis, Missouri site. The expansion targets capacity constraints in high-potency and bioconjugation services, improving availability for both late-stage clinical and commercial-scale outsourcing demand.


Antibody Drug Conjugates Contract Manufacturing Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market covers outsourced services used to develop, manufacture, conjugate, test, and finish antibody-drug conjugates (ADCs) for clinical and commercial supply, captured as service revenue billed by contract manufacturers.
Scope exclusions: In-house ADC manufacturing done fully within biopharma sites and non-ADC biologics outsourcing are not counted.
Segments Covered in This Report
- By Linker Type
- Cleavable
- Acid-labile
- Protease-cleavable
- Disulfide-cleavable
- Non-cleavable
- Cleavable
- By Therapeutic Area
- Hematologic Cancers
- Multiple Myeloma
- Lymphoma
- Solid Tumours
- Breast
- Lung
- Gastric & GI
- Other Indications (Auto-immune, Infectious)
- Hematologic Cancers
- By Phase
- Pre-clinical
- Phase I
- Phase II
- Phase III
- Commercial
- By Service Type
- Process / Cell-line Development
- Analytical, Bio-assay & QC
- cGMP Conjugation & Drug-linker Manufacturing
- Fill-Finish & Packaging
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market boundaries and build the first pass of demand and capacity signals relevant to ADC outsourcing. We leaned on public sources such as the FDA databases (approvals and inspections), NIH ClinicalTrials.gov for ADC pipeline activity by phase, the World Health Organization for cancer burden context, and OECD health indicators to frame treatment access and diagnostics patterns by region.
We also reviewed company annual reports, investor decks, and press coverage to understand capacity additions, new suites, and announced partnerships that can shift outsourced volumes. For trade and flows, we used public customs and trade statistics where they were relevant, and we complemented it with an approved paid subscription for company financials and news to keep timelines, currency, and corporate actions consistent. These desk research sources are not exhaustive, and we used many other public references for data collection, cross-checking, and clarifying open questions.
Primary Interviews and Surveys
Primary work focused on validating what portion of ADC work is actually outsourced, how pricing is being quoted (development runs versus routine commercial supply), and how quickly new capacity is being absorbed. We spoke with a mix of contract manufacturers, pharma and biotech outsourcing teams, and technical leaders who manage conjugation, analytical/QC, and fill-finish flows across APAC, EMEA, and the Americas, so assumptions could be checked region by region.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 36% | CXOs: 15% | APAC: 41% |
| Mid tier: 49% | Functional/Unit leaders: 30% | EMEA: 36% |
| Smaller Players: 15% | Managers: 55% | Americas: 23% |
Market-Sizing & Forecasting
Our sizing starts with a top-down demand pool view where ADC clinical and commercial activity is translated into outsourced service value through phase mix, typical batch cadence, and service bundle usage (process development, analytical/QC, cGMP conjugation, and fill-finish). To keep it grounded, we then corroborate totals using selective bottom-up checks such as sampled program volumes by phase multiplied by observed price bands, and supplier-side rollups for a limited set of service lines where disclosures are clearer.
Key inputs used in the model include ADC trial counts and phase progression, commercial launches and label expansions, mix shifts between hematologic cancers and solid tumors, typical number of manufacturing runs per program per year, and quoted price movement for conjugation and analytical/QC work as capacity tightness changes. Where direct disclosure is limited, gaps are handled through ranges agreed during interviews, and then narrowed using consistency checks against capacity additions and utilization direction.
For forecasting, we rely on scenario analysis supported by variable-by-variable expert consensus, since pipeline conversion and commercial scale-up timing can change quickly. The forecast therefore adjusts year-by-year for expected approvals, capacity ramp schedules, and service mix changes rather than only extending a single growth rate.
Data Validation & Update Cycle
Outputs are checked against independent signals such as changes in ADC pipeline volume, visible capacity announcements, and shifts in quoted lead times that indicate tightness or slack. When a value looks off, we re-check unit assumptions, reconcile any currency conversion timing, and then re-contact sources if the variance stays material.
Before sign-off, the model goes through a multi-step analyst review where assumptions, calculations, and sensitivities are re-run to ensure the totals can be reproduced. The report is refreshed annually, and interim updates are made when material events occur, followed by a final pre-delivery pass so clients receive the latest view.
麻豆视频's Antibody Drug Conjugates Contract Manufacturing Market Estimate Compared With Other Published Estimates
Published market sizes for ADC contract manufacturing can vary widely because different authors draw the boundary around services differently, and they also apply different timing for currency, inflation, and price progression. Even when the same end year is quoted, the underlying service mix and the way clinical versus commercial work is weighted can move the value a lot.
In this study, the totals are kept stable by refreshing price bands and FX timing close to the base year, and then re-validating the implied spend per program against phase activity and service bundle usage. This helps explain why 麻豆视频 reports a higher value than some conservative estimates that smooth prices or lag updates.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 12.02 B (2026) | |
| Trade Journal A | USD 1.79 B (2024) | This figure is presented as a narrower contract ADC view that tends to emphasize a subset of value chain components and earlier-stage work, which can undercount full service bundles like cGMP conjugation plus fill-finish for commercial supply. |
| Industry Press Release B | USD 3.80 B (2024) | The estimate appears to use a different base year and may blend service categories unevenly across clinical and commercial needs, with limited transparency on ASP updates, currency timing, and how multi-service programs are consolidated into a single revenue pool. |
Across the three figures, the spread is mainly driven by scope width and by how quickly pricing and currency assumptions are refreshed. When service bundles are clearly defined and checked against phase activity and capacity realities, the resulting market value becomes easier to trace and to repeat year to year.


Key Questions Answered in the Report
How large is the antibody drug conjugates contract manufacturing market in 2026 and how fast is it growing?
The market reached USD 12.02 billion in 2026 and is forecast to grow at an 11.31% CAGR to USD 20.54 billion by 2031.
Which linker type is expanding fastest in outsourced ADC production?
Non-cleavable linkers are projected to post a 15.25% CAGR between 2026 and 2031, outpacing cleavable formats.
Why are sponsors outsourcing commercial-scale ADC manufacturing instead of building in-house plants?
Building an OEB 4-5 suite costs USD 80-120 million and takes up to 30 months, whereas CDMOs already operate validated capacity that can be accessed under long-term supply deals.
Which region will add the most new ADC capacity through 2031?
Asia-Pacific leads with USD 3.5 billion in announced greenfield projects, driving a 14.04% regional CAGR.
What is driving premium pricing for ADC contract manufacturing?
Scarce HPAPI containment suites, complex analytical release requirements, and sustained oncology demand allow CDMOs to price ADC contracts 30-40% higher than monoclonal antibody work.
Page last updated on:



