
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 1.01 Trillion |
| Market Size (2026) | USD 1.08 Trillion |
| Market Size (2031) | USD 1.47 Trillion |
| Growth Rate (2026 - 2031) | 6.49 % |
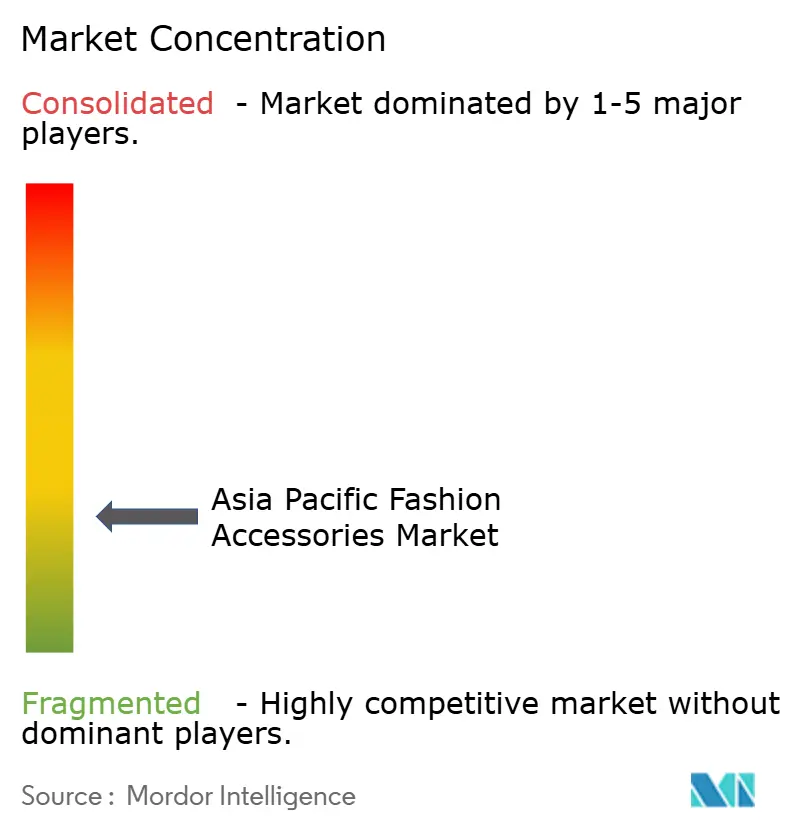
| Market Concentration | Low |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Asia-Pacific Fashion Accessories Market Analysis by 麻豆视频
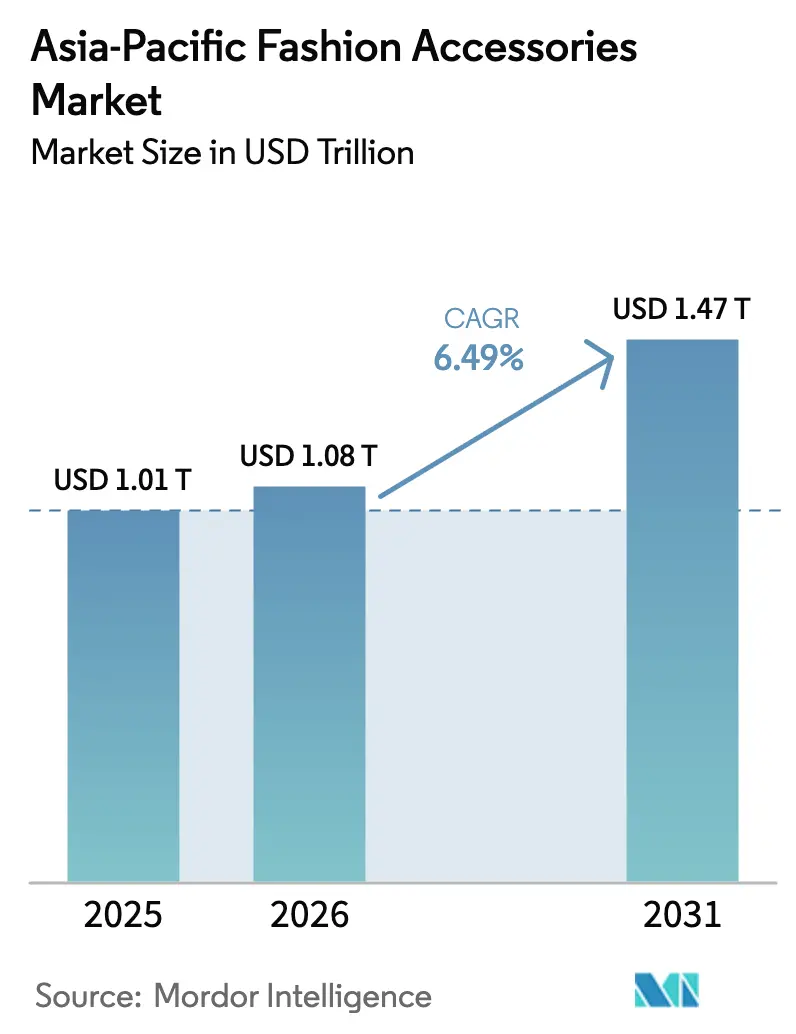
The Asia-Pacific fashion accessories market size was valued at USD 1.01 trillion in 2025 and estimated to grow from USD 1.08 trillion in 2026 to reach USD 1.47 trillion by 2031, at a CAGR of 6.49% during the forecast period (2026-2031). Rising income levels, urbanization, and smartphone usage are making branded accessories more accessible in urban and semi-urban areas. Premiumization is growing as wealthier consumers prefer high-end brands, while the mass-market segment dominates in volume by catering to cost-conscious buyers. E-commerce platforms, supported by mobile payments and social-commerce features, are expediting purchases and boosting international transactions. Companies are attracting environmentally conscious consumers, especially in developed Asia-Pacific metros, through supply-chain transparency and circular-economy practices. The market is highly competitive, with global players like Nike, Adidas, and PUMA competing against regional brands. Companies are tailoring products to local preferences, as seen with Nike’s R&D center in Shenzhen.
Key Report Takeaways
- By product type, apparel accessories commanded 56.78% of the Asia-Pacific fashion accessories market share in 2025, while watches are forecast to post the fastest 6.88% CAGR through 2031.
- By end user, women-led purchases with a 53.92% share in 2025; the kids segment is advancing at a 7.12% CAGR to 2031.
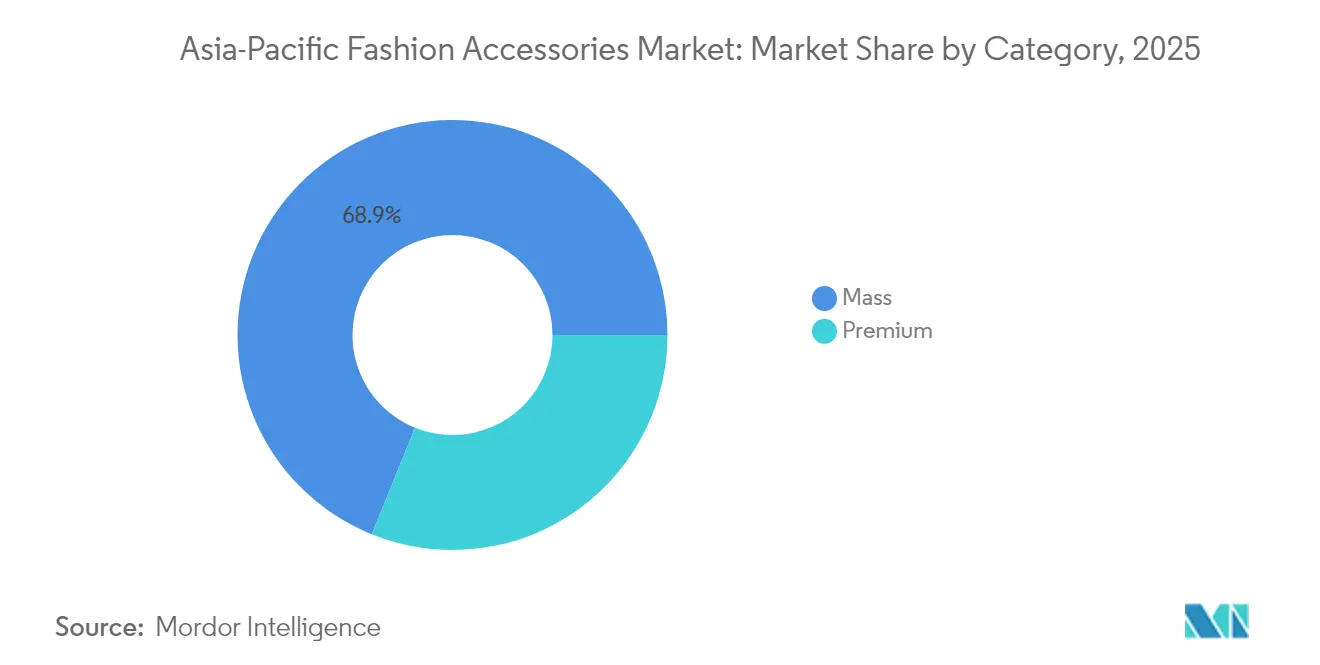
- By category, mass-market goods held 68.88% of the Asia-Pacific fashion accessories market size in 2025; premium lines are set to grow at 7.54% CAGR during 2026-2031.
- By distribution channel, offline stores retained a 63.95% share in 2025, whereas online channels are expanding at an 7.99% CAGR to 2031.
- By geography, China contributed 39.12% revenue in 2025, whereas Thailand is projected to rise at an 8.42% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Table of Asia-Pacific Fashion Accessories Market*
| DRIVER | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Technological advancements in terms of design and raw material | +1.2% | concentration in China, Japan, South Korea | Medium term (2-4 years) |
| Strong demand from inbound tourists | +0.8% | China, Japan, Thailand, Singapore | Short term (≤ 2 years) |
| Growing preference for luxury and branded fashion accessories | +1.5% | China, India, Australia, Singapore | Long term (≥ 4 years) |
| Changing consumer behavior toward fitness and athleisure | +1.1% | early adoption in Australia, South Korea | Medium term (2-4 years) |
| Sustainability and ethical sourcing awareness | +0.7% | Australia, Japan, South Korea, urban China | Long term (≥ 4 years) |
| Influence of social media and celebrity endorsements | +0.9% | China, India, Thailand, Indonesia | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Strong demand from inbound tourists
The Asia-Pacific fashion accessories market is growing rapidly, driven by a strong recovery in tourism. The Pacific Asia Travel Association estimates international visitor arrivals to the region will reach 813.7 million by 2027, up from 648.1 million in 2024 [1]Source: International Visitors Arrival in Asia-Pacific, "PATA Forecasts Strong Asia Pacific Visitor Rebound and Growth Through 2027," pata.org. Similarly, the Japan National Tourism Organization (JNTO) and Japan Tourism Agency (JTA) report that 36.9 million foreign tourists visited Japan in 2024 [2]Source: Foreign Tourists Arrival in Japan, " Tourism in Japan: A look at the Numbers from 2024 and the Outlook for 2025," jittiusa.org. Luxury brands and boutiques are offering exclusive collections and collaborating with local artisans to attract tourists seeking unique, culturally inspired items. Retailers are also using dynamic pricing strategies to address currency fluctuations, such as the weaker yen, ensuring competitiveness and profitability. These trends highlight tourism's direct influence on product offerings and retail strategies in key shopping destinations across the Asia-Pacific.
Changing consumer behavior toward fitness and athleisure
The growing focus on fitness and active lifestyles is reshaping the Asia-Pacific fashion accessories market. More people are choosing products like gym-friendly bags, smartwatches, and multi-purpose accessories as part of their daily routines. For example, backpacks with special compartments for gym shoes and water bottles are becoming popular among professionals who juggle work and exercise. Smartwatches are another favorite, as they help track fitness activities like steps, heart rate, and calories burned, while also offering a stylish look. Brands are also using advanced materials, such as moisture-wicking and quick-dry fabrics, to meet consumer needs. For instance, breathable sneakers are now used not only for workouts but also for casual outings, making them a versatile choice. In March 2025, ASICS India released the GEL-K1011, a retro-inspired sneaker combining GEL-KAYANO aesthetics with modern breathable mesh and FF BLAST cushioning, making it suitable for both running and streetwear. Similarly, gym bags with modern, sleek designs are being used as office bags, appealing to consumers who value both style and practicality.
Growing preference for luxury and branded fashion accessories
In the Asia-Pacific region, rising demand for luxury and branded accessories is driven by a growing middle class and increasing purchasing power. The IMF projects the region's PPP-adjusted GDP per capita to reach USD 96.43 thousand by 2025, highlighting strong consumer spending potential [3]Source: Purchasing Power Parity, " GDP, current prices, Purchasing power parity; billions of international dollars, " imf.org. This economic growth enables more consumers to invest in premium products valued for craftsmanship and cultural relevance. Global brands are localizing offerings, such as Tod’s collaboration with Indian designer Rahul Mishra in September 2024 and LVMH’s "Crafted World" exhibit at the 2025 Osaka Expo, which featured collaborations with Japanese artisans, showcasing traditional craftsmanship while appealing to local consumers. Regional brands like Singapore-based Aupen are also merging local identity with global luxury appeal. These strategies reflect how brands align with regional tastes and economic momentum to thrive in Asia–Pacific’s evolving luxury market.
Technological advancements in terms of design and raw material
Technological advancements in design and raw materials are transforming the Asia-Pacific fashion accessories market. Nike, for example, launched its Shenzhen Technology Hub and Sport Research Lab in 2024, focusing on eco-friendly materials like recyclable fibers and plant-based alternatives. These innovations cater to Chinese consumers, accelerate product development, and reduce waste. Similarly, TAL Apparel in Hong Kong introduced its first Regenagri-certified garment, made from regenerative cotton, renewable energy, and designed to cut greenhouse gas emissions, showcasing its commitment to sustainability. On the retail side, smart technologies like item-level RFID tags are gaining traction. These tags improve product tracking, prevent counterfeits, and enable authenticated resale, helping brands build trust, support premium pricing, and meet stricter regulations while enhancing supply chain transparency.
Restraints Impact Analysis of Asia-Pacific Fashion Accessories Market*
| RESTRAINT | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Proliferation of counterfeit products | -1.8% | China, Southeast Asia, India | Short term (≤ 2 years) |
| Supply chain disruptions | -1.2% | concentration in Vietnam, China, Bangladesh | Medium term (2-4 years) |
| Fluctuating raw material prices | -0.9% | affecting textile-dependent countries like China, India | Short term (≤ 2 years) |
| Rising trade barriers and tariffs | -1.4% | Vietnam, China, Indonesia, Thailand | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Proliferation of counterfeit products
Counterfeit fashion accessories are a growing challenge in the Asia-Pacific market, damaging brand reputations and diverting revenue. In 2025, authorities in the Philippines seized fake Crocs worth PHP 152 million, highlighting the region's rampant counterfeit trade. The National Committee on Intellectual Property Rights reported PHP 40.99 billion worth of counterfeit goods seized in February 2025, a 52% increase from the previous year [4]Source: Counterfeit Products Seized, "NCIPR seizes record P40.99 billion counterfeit goods in 2024," ipophil.gov.ph. Counterfeit designer items are often seen as affordable alternatives in Southeast Asia, complicating consumer education efforts. Regulatory bodies in countries like Vietnam are tightening customs checks, driven by international trade agreements, raising exporters' costs. For example, in June 2025, a clothing store in Pitampura, northwest Delhi, was raided, and over 200 counterfeit items, including shorts and t-shirts, were seized. Global brands are adopting measures like blockchain-based authentication and tamper-proof packaging, but implementing these technologies across fragmented supply chains remains costly and complex.
Rising trade barriers and tariffs
Rising trade barriers and tightening regulations are disrupting fashion accessories consumption across Asia-Pacific. The removal of low-value import exemptions in countries like Australia, India, and Indonesia has increased duties on cross-border purchases, making international fast-fashion and accessory products more expensive for everyday consumers. Governments are also stepping up enforcement on foreign e-commerce platforms. For instance, Indonesia banned Temu in 2024 for non-compliance with local trade rules, while India has imposed stricter norms on platforms like Shein and AliExpress, curbing their operations. These measures are raising prices, reducing product variety, and limiting access to affordable international brands, especially in markets where consumers increasingly rely on cross-border digital channels for trendy, low-cost accessories.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Asia-Pacific Fashion Accessories Market Segment Analysis
By Product Type:
Apparel Dominance Faces Watch InnovationIn 2025, apparel accessories accounted for 56.78% of the Asia-Pacific fashion accessories market. Items like belts, scarves, and costume jewelry remain essential due to changing fashion trends and social media influence. Retailers boost sales through bundled deals and private-label collections, while sourcing hubs in China and Vietnam enable quick restocking. Sustainability demands are driving the use of eco-friendly materials like recycled polyester and low-impact dyes. Personalized products, such as monogrammed items, are also gaining popularity, fostering stronger customer connections and reducing price sensitivity.
Watches are the fastest-growing category, with a 6.88% CAGR projected through 2031. Wealthy millennials favor Swiss mechanical watches as investments, while mainstream consumers prefer smartwatches for features like health tracking and contactless payments. Collaborations between tech firms and fashion brands accelerate wearable technology integration. Local manufacturers in Shenzhen and Seoul reduce costs and enable regional customization. Brands enhance loyalty by offering complementary products like interchangeable straps and charging docks, increasing value for Asia-Pacific consumers.


By End User:
Women Lead While Children AccelerateIn 2025, women contributed 53.92% of the revenue, reflecting their frequent purchases and diverse preferences for accessories like handbags, jewelry, and hair ornaments. Retailers are engaging female shoppers through exclusive collections, influencer collaborations, and buy-now-pay-later options. Advanced customer management tools enable life stage-based segmentation, allowing targeted promotions like bridal jewelry for brides-to-be. Women’s preference for ethically sourced products is driving demand for traceable gold and lab-grown diamonds, aligning with sustainability and ethical values.
The kids' segment is projected to grow at a 7.12% CAGR from 2026 to 2031, making it the fastest-growing demographic. Dual-income households are increasing spending on children’s accessories, often inspired by adult fashion trends. Safety concerns drive manufacturers to use non-toxic dyes and child-safe designs. Licensing agreements with entertainment franchises boost brand appeal, while educators influence functional features like ergonomic backpack straps. Online shopping is rising, offering parents convenience and easy returns.
By Category:
Mass-Market Stability Meets Premium AccelerationIn 2025, mass-market products captured a dominant 68.88% market share, largely attributed to their affordability and widespread accessibility. Manufactured in bulk with standardized designs, these products enable producers to maintain lower costs. Retailers, leveraging efficient logistics like just-in-time inventory management, ensure product availability while sidestepping overstocking. Furthermore, predictive analytics empower retailers to forecast demand, averting stock shortages in major discount outlets. Despite intense price competition, certain brands carve out a niche by introducing sustainability certifications and offering inclusive sizing, broadening their customer appeal. Moreover, flexible return policies in both online and brick-and-mortar stores bolster trust and loyalty among mass-market shoppers.
On the other hand, premium products are set to expand at a 7.54% CAGR until 2031, fueled by consumers' desire for exclusivity and distinctive shopping experiences. Highlighting traditional craftsmanship, limited-edition collections, and bespoke services, these products command their elevated price tags, even in markets where spending is typically restrained. Premium brands are streamlining their supply chains for transparency and quality, ensuring materials are both top-notch and ethically sourced. Some are even venturing into the digital realm, utilizing non-fungible tokens (NFTs) as a modern stamp of authenticity. By straddling both mass-market and premium segments, major players can diversify their portfolios, ensuring resilience against economic shifts in the Asia-Pacific fashion accessories arena. This dual approach empowers them to pivot production and offerings in tune with evolving consumer tastes and market dynamics.
By Distribution Channel:
Digital Transformation AcceleratesPhysical stores accounted for 63.95% of sales in 2025, showing that many customers still prefer to see and touch accessories before buying them. To improve the shopping experience, retailers are upgrading their store layouts with better visual displays, adding QR codes that provide more product details, and offering click-and-collect services. These services allow customers to order online and pick up their purchases in-store, which helps reduce delivery costs. Department stores remain a popular choice because they attract a lot of shoppers, but the rising cost of rent is pushing retailers to try new approaches. Many are experimenting with temporary pop-up stores and shop-in-shop setups, which help them stay visible to customers without committing to long-term leases.
Online sales are expected to grow at a strong 7.99% CAGR, driven by the convenience of mobile payments, high-quality visuals, and the growing influence of social-commerce platforms. In countries like China and Southeast Asia, live-stream shopping events are gaining momentum, allowing consumers to watch product demos and make purchases instantly. Retailers are also investing in seamless omnichannel strategies, integrating physical and online inventory systems to offer faster fulfillment, flexible delivery options, and real-time product availability. These innovations are reshaping the customer journey and fueling continued growth in the region’s online fashion accessories market.
Geography Analysis
China Fashion Accessories Market
In 2025, China commands a dominant 39.12% share of the regional market. This leadership position stems from its sophisticated e-commerce platforms, adeptly serving both luxury aficionados and budget-savvy accessory shoppers. Local brands swiftly pivot to trends surfacing on social media, while international luxury names infuse their marketing with Chinese zodiac symbols and culturally resonant themes. Initiatives to thwart counterfeit products and establish verification systems have bolstered consumer trust, leading to heightened purchases of premium luxury items. Yet, the market grapples with fierce competition, escalating the costs of acquiring new clientele. In response, brands are pivoting to private channels like WeChat groups, fostering direct consumer engagement, loyalty, and bespoke shopping experiences.
ASEAN Fashion Accessories Market
Thailand emerges as the region's fastest-growing market, boasting a projected CAGR of 8.42%. This surge is buoyed by a resurgence in international tourism, ushering more visitors into luxury malls and boutiques. Retailers, in turn, are curating exclusive travel-themed collections and launching pop-up stores tailored for tourists. The broader Southeast Asia region is witnessing a digital commerce boom, with projections from the Asian Development Bank indicating it will represent 61% of global B2C e-commerce transactions by 2025. Meanwhile, Vietnam enhances its export edge through blockchain-driven supply chain transparency, and Singapore solidifies its position as a logistics nexus, providing same-day cross-border deliveries and streamlined payment systems for its mobile-centric shoppers.
India and Indonesia Fashion Accessories Market
India's market expansion is fueled by urbanization, increasing disposable incomes, and a burgeoning retail infrastructure in smaller towns. With a rising middle class splurging on fashion accessories, both local and global brands find fertile ground for expansion. In neighboring Indonesia, celebrity endorsements wield considerable influence, underscoring the region's shared and adapted marketing strategies. Enhanced logistics, like freight routes linking India and Southeast Asia, are slashing delivery times, allowing retailers to swiftly replenish trendy accessories. This agility ensures brands cater to a growing consumer base eager for fashionable yet affordable choices.
Regulatory Landscape
Regulation affecting fashion accessories in Asia-Pacific is increasingly shaped by cross-border trade rules and tightening supply-chain compliance requirements. RCEP implementation by 2026 standardizes rules of origin and tariff schedules across key regional corridors, which can influence sourcing choices and intra-Asia distribution for accessories, spanning footwear components to jewelry and handbags. At the same time, enforcement activity around intellectual property and counterfeits remains an operating factor across multiple markets, pushing brands toward stronger product authentication and closer customs coordination.
On sustainability and responsible sourcing, modern-slavery and forced-labor due diligence expectations for global supply chains are increasing documentation and traceability requirements for exporters and brand owners serving international consumers. This aligns with supplier-focused governance visible in the region, including Titan Company Limited reporting supplier-focused policies and the use of LBMA-accredited refineries for a majority of jewellery inputs, supporting compliance readiness for premium accessory categories where provenance and responsible sourcing claims are central to brand positioning.
Value Chain Analysis
The Asia-Pacific fashion accessories value chain spans raw materials (textiles, leather substitutes, metals, gemstones, and electronics components for wearables), design and product development, manufacturing and assembly, branding and merchandising, and multi-channel distribution. Product development and materials innovation are increasingly localized for speed and fit to market, supported by Nike establishing an R&D center and technology hub in Shenzhen to accelerate development and materials work for the China market. In premium jewelry, supply assurance and craftsmanship capacity depend on upstream investments and tighter supplier governance, while mass-market categories rely more on scale manufacturing, rapid replenishment, and cost discipline.
Downstream, the region is a mix of brand-owned retail, department stores, specialty retailers, and fast-growing online and social commerce. Luxury groups often prioritize direct retail control to manage inventory, pricing, and clienteling, while large regional players also build and optimize store networks alongside digital. Titan Company Limited disclosed an international retail footprint as of March 2026 (including 149 stores in the GCC, 12 in North America, and one in Singapore) and active network optimization during Q4FY26 (store renovations and closures), illustrating how leading accessory sellers manage distribution productivity and brand experience across formats and geographies.
Competitive Landscape
The competition in the Asia-Pacific fashion accessories market is fragmented. Global brands like LVMH, Hermes, and Kering, along with companies such as Nike, Adidas, and PUMA, are competing against regional and niche players. Each brand is tailoring its products to suit local cultural preferences. For example, in 2024, Nike’s research and development center in Shenzhen focused on designing products specifically for the Chinese market, showcasing a strategy known as “in-market, for-market” innovation. This approach allows global brands to stay relevant by addressing the unique needs of local consumers. At the same time, regional brands are leveraging their deep understanding of local tastes to strengthen their market presence and compete effectively with global players.
Opportunities in sustainable accessories and smart wearables are growing, with start-ups using social media platforms for marketing instead of traditional advertising. For instance, in 2024, several start-ups in Southeast Asia introduced eco-friendly bags and jewelry made from recycled materials. These products gained significant attention through Instagram and TikTok campaigns, which helped them reach a large audience without requiring high marketing budgets. Luxury brands are also adopting blockchain technology to provide authenticity certificates, which help prevent counterfeit products and build consumer trust. A notable example is LVMH’s acquisition of Chrome Hearts in 2024, which allowed the company to expand its portfolio with niche brands that have strong online followings. This highlights the increasing importance of digital engagement and sustainability in the fashion accessories market.
Global brands are increasingly collaborating with local artisans to craft culturally authentic products that meet environmental standards. Renowned names such as Hermès, Louis Vuitton, and Gucci are sourcing from Indian artisans, infusing their collections with a touch of handmade elegance. This move not only safeguards traditional craftsmanship but also resonates with eco-conscious consumers. Furthermore, contract manufacturers are expanding their operations from China to nations like Cambodia and India, mitigating risks tied to tariffs and trade restrictions. This strategic shift bolsters stable supply chains and lessens reliance on any single region. In the Asia-Pacific fashion accessories market, businesses are harnessing advanced technologies like predictive analytics and immersive product visualization. These innovations enhance efficiency, refine demand forecasting, and ensure product alignment with consumer preferences, granting companies a competitive advantage.
Asia-Pacific Fashion Accessories Industry Leaders
-
Titan Company Limited
-
LVMH Mo?t Hennessy Louis Vuitton SE
-
Kering SA
-
Prada SpA
-
Hermès International
- *Disclaimer: Major Players sorted in no particular order
Asia-Pacific Fashion Accessories Market Companies Covered in this Report
- Nike Inc.
- Adidas AG
- Fast Retailing Co., Ltd
- Puma SE
- Bosideng International Holdings Limited
- Fossil Group Inc.
- Seiko Watch Corporation
- Skechers USA Inc.
- LVMH Mo?t Hennessy Louis Vuitton SE
- Kering SA
- Anta International Group Holdings Limited
- Bagzone Lifestyles Pvt. Ltd.
- Tapestry Inc.
- EssilorLuxottica SA
- Swatch Group
- Titan Company Limited
- Prada SpA
- Xiaomi Corp.
- Aditya Birla Fashion & Retail Ltd.
- Hermès International
- Capri Holdings Ltd.

Market Opportunities and Future Outlook
Trade facilitation and manufacturing policy actions create identifiable opportunities for exporters and brands to optimize sourcing and route-to-market across Asia-Pacific. RCEP implementation by 2026, with tariff liberalization across most traded goods and common rules of origin, supports accessory supply chains that combine production in Southeast Asia with sales into Japan, South Korea, Australia, and New Zealand. It also encourages regional consolidation of sourcing for categories such as handbags, apparel accessories, and footwear-related accessories. In India, Union Budget 2026 measures effective 2 February 2026, including customs duty exemptions for inputs used to manufacture shoe uppers and extended export obligation timelines, strengthen the operating backdrop for accessory-adjacent manufacturing ecosystems and supplier localization.
Opportunities also cluster around premiumization, authentication, and circularity where regulatory and consumer pressures overlap. Brand actions in 2026 point to investment in tighter supply-chain control and technology-led retail enablement, for example Kering reorganizing to strengthen centralized industry and supply-chain management and luxury players deepening digital retail partnerships for China-linked ecosystems. In parallel, anti-counterfeit enforcement and traceability requirements increase demand for item-level identification, such as RFID and digital certificates, supporting authenticated resale models and higher trust in premium categories. Tourism-linked shopping remains a concrete demand lever in key hubs, supported by Japan’s reported 36.9 million foreign tourists in 2024, which underpins travel retail, exclusive capsules, and rapid replenishment needs for accessories sold through airports, flagship stores, and luxury malls.
Recent Industry Developments in Asia-Pacific Fashion Accessories Market
- July 2026: Titan Company Limited expands the IRTH premium handbag brand with new retail locations, including inducting a presence at Indore Phoenix Citadel Mall. The expansion formalizes the handbag category within APAC-centric markets and broadens access to direct stores. It supports handbag category growth and strengthens the retailer's direct-store network against unorganized players.
- April 2026: Titan Company Limited reports Q4FY26 results showing 47% growth in the women’s bags category and the addition of 6 stores for the IRTH brand. The performance signals momentum in the premium handbag segment and reflects progress on brand expansion. The results reinforce the premium handbag strategy and the retail expansion trajectory.
- March 2026: Kering SA completes the initial acquisition of a 20% stake in Raselli Franco Group for 115 million euros to strengthen control over the jewelry value chain. The acquisition enhances jewelry supply chain integration within the APAC luxury segment and supports brand positioning in high value markets. It also broadens Kering's access to regional luxury jewelry capabilities and downstream production capacity.


Asia-Pacific Fashion Accessories Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the Asia-Pacific fashion accessories market is measured as the total value of accessories purchased across the region through offline and online channels, covering mass and premium spending and across key consumer groups.
Scope exclusions: This sizing excludes raw material trade values and intermediate manufacturing services that do not directly reflect the finished accessory value sold to end buyers.
Segments Covered in This Report
-
By Product Type
- Footwear
- Apparel
- Wallets
- Handbags
- Watches
- Sunglasses
- Jewelery
-
By End User
- Men
- Women
- Kids/Children
-
By Category
- Mass
- Premium
-
By Distribution Channel
- Offline Stores
- Online Stores
-
By Geography
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the boundaries of the market and to collect the base inputs that can be verified without paywalls. We typically rely on official statistics and public datasets such as UN Comtrade for trade flows, the World Bank for income and macro indicators, the International Labour Organization for workforce indicators, and country statistics offices for household expenditure and retail series. For the region context, we also refer to central bank releases, customs summaries, and consumer price index tables that help normalize values year to year.
To translate these signals into a usable market model, secondary information was layered in from public company filings, investor presentations, audited annual reports, and reputable press coverage that discusses category momentum and channel shifts. Where public reporting was thin, select paid subscriptions for company financials and news intelligence were used, along with shipment-level import and export databases, to cross-check directionally. The desk sources mentioned are illustrative only, and many other public and paid references were consulted for data collection, cross-verification, and clarification.
Primary Interviews and Surveys
Primary work focused on confirming what portion of accessory spending is being captured in each country, and how price-mix changes are playing out between mass and premium lines. We spoke with a spread of brand-side and retail-side respondents, along with distributors and category specialists, across major Asia-Pacific demand centers, so the model assumptions could be adjusted to what is being seen in market pricing and channel behavior.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 33% | CXOs: 13% |
| Mid tier: 53% | Functional/Unit leaders: 29% |
| Smaller Players: 14% | Managers: 58% |
Market-Sizing & Forecasting
Sizing starts from a top-down build where country-level accessory demand pools are reconstructed using consumer spending indicators, retail sales direction, and trade-linked availability checks, then consolidated to the Asia-Pacific total. To keep the estimate realistic, we corroborate it with selective bottom-up approximations such as sampled category revenue roll-ups from disclosed company results, channel checks on online versus offline mix, and price band mapping using typical average selling prices multiplied by implied volumes.
Key inputs that shaped the model included urbanization and income growth patterns, changes in e-commerce penetration and mobile-led buying, premiumization cues from mix shifts, seasonality around gifting and festival periods, and inflation effects captured through CPI adjustments. When a country had limited visibility for one of these inputs, the gap was handled through peer-country proxying and then re-checked with interview feedback before being accepted.
Forecasting was done using scenario analysis supported by multivariate regression, where the main drivers were aligned to expected income trends, digital channel growth, and normalization of price-mix. Assumptions were kept simple enough to be repeated each year, and any outlier trend was only carried forward when it was supported by more than one independent signal.
Data Validation & Update Cycle
Outputs are validated through triangulation across independent signals, and then stress-tested using variance checks at the country level so sudden jumps can be explained by a visible driver. If a value looks inconsistent with trade flows, retail momentum, or reported category commentary, the inputs are revisited, and respondents may be re-contacted to confirm the likely reason.
Before sign-off, the model and written logic go through multi-step analyst review so assumptions are consistent across countries and time periods. Reports are refreshed annually, and interim updates are made when material events meaningfully affect demand, pricing, or channel mix. Prior to delivery, we do a fresh pass to ensure the latest public information is reflected in the final numbers.
麻豆视频's Asia Pacific Fashion Accessories Market Estimate Compared With Other Published Estimates
Published market sizes can look far apart even when they discuss the same category, because the boundary of what is counted as an accessory is not always consistent. Differences also come from how the year and currency are treated, plus the way online channel momentum and premium mix shifts are weighted.
Import and export patterns, along with country retail trend signals and interview checks on price-mix, are the evidence anchors that keep 麻豆视频 tied to a defined Asia-Pacific demand pool rather than a broader apparel-led tally.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 1.01 T (2025) | |
| Trade Journal A | USD 0.67 T (2024) | This figure is anchored to a narrower definition closer to personal accessories and often excludes large adjacent categories that lift total spend, and it also reflects a different base year and currency timing. |
| Regional Consultancy B | USD 0.18 T (2025) | The estimate typically focuses on a limited product set like handbags and similar items, which undercounts the full accessories basket, and the growth path tends to assume a faster premium shift without the same level of country-level cross-checks. |
The spread in values is mainly explained by what product scope is included and how country totals are stitched together across channels. By keeping the inputs traceable to observable demand signals and then adjusting assumptions only after interviews confirm the direction, the final number stays balanced and repeatable for planning.


Key Questions Answered in the Report
What is the current size of the Asia-Pacific fashion accessories market?
The market is valued at USD 1.08 trillion in 2026 and is forecast to reach USD 1.47 trillion by 2031.
Which product category is growing fastest?
Watches, including smartwatches and luxury timepieces, are projected to grow at a 6.88% CAGR through 2031.
How important is China within the regional market?
China contributed 39.12% of 2025 revenue, making it the single largest national market.
What share do online channels hold?
Offline stores still dominate with 63.95% share in 2025, but online channels are advancing at an 7.99% CAGR.
Page last updated on:



