
Canada Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
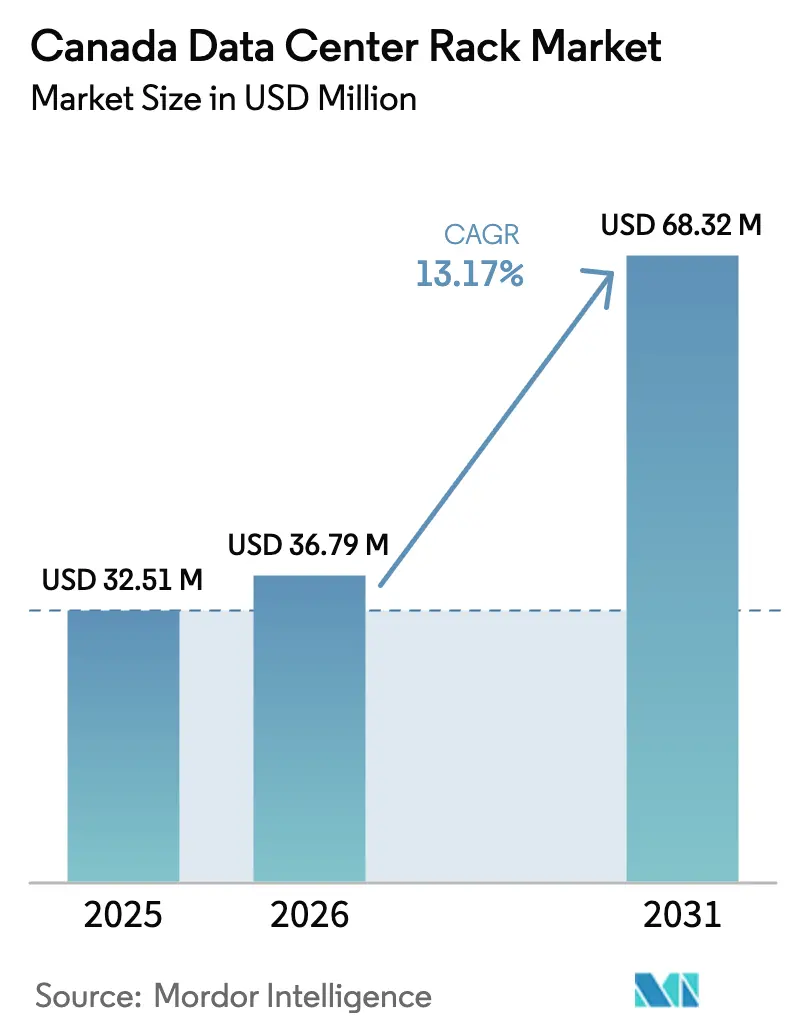
| Base Year Market Size (2025) | USD 32.51 Million |
| Market Size (2026) | USD 36.79 Million |
| Market Size (2031) | USD 68.32 Million |
| Growth Rate (2026 - 2031) | 13.17 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Canada Data Center Rack Market Analysis by 麻豆视频
Canada data center rack market size in 2026 is estimated at USD 36.79 million, growing from 2025 value of USD 32.51 million with 2031 projections showing USD 68.32 million, growing at 13.17% CAGR over 2026-2031. Power-dense deployments above 60 kW per rack, regulatory data-sovereignty mandates and hyperscale expansion are converging to sustain double-digit growth. Canada’s colocation providers are capitalizing on provincial incentives for renewable power and on stringent privacy laws that keep workloads within national borders, while AI training clusters create fresh demand for integrated liquid-cooled racks. Rising tariffs on Chinese steel and aluminum are nudging buyers toward North American supply chains, and labor shortages for high-density commissioning are encouraging turnkey rack solutions that minimize on-site work. These dynamics collectively favor vendors capable of delivering factory-integrated, AI-ready cabinets to hyperscale and colocation sites in Toronto, Montréal, Calgary and Vancouver.
Key Report Takeaways
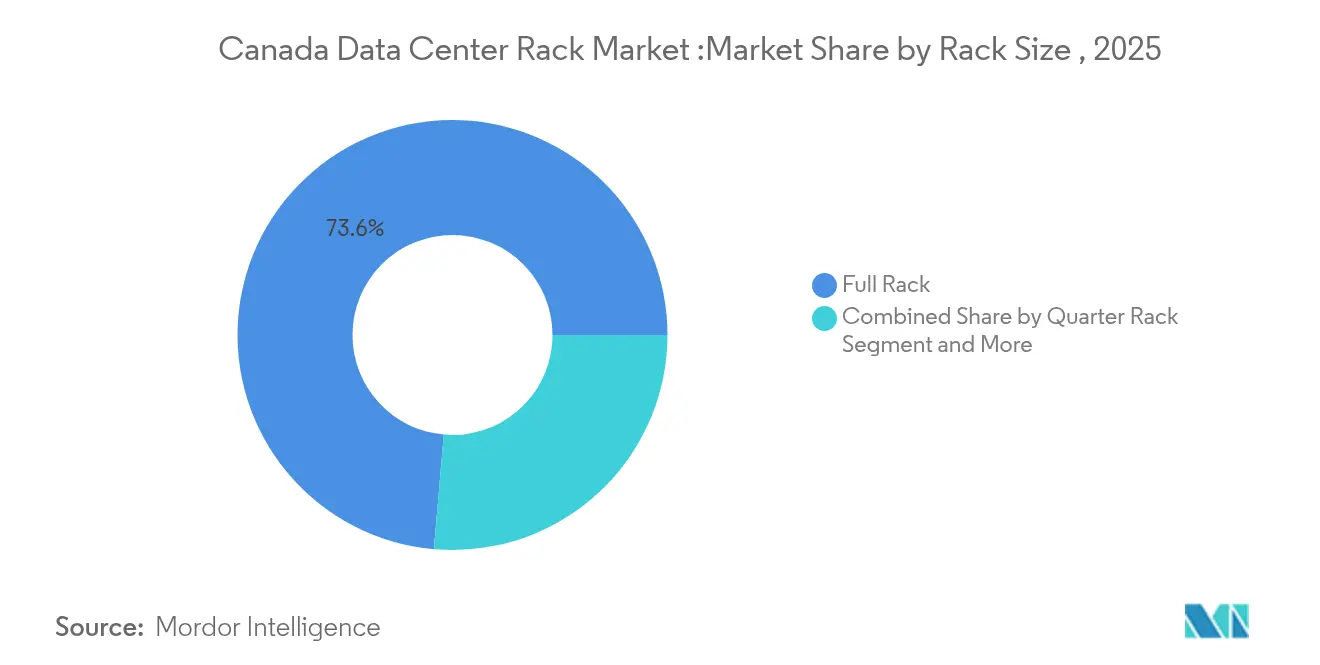
- By rack configuration, Full Rack designs held 73.62% of the Canada data center rack market share in 2025, and the segment is growing at 14.02% CAGR through 2031.
- By rack height, the 48U category is the fastest mover, expanding at 14.92% CAGR, while 42U units retain 55.98% share of the Canada data center rack market size in 2025.
- By rack type, Cabinet (Closed) models accounted for 71.05% of revenue in 2025 and are poised to rise at a 15.88% CAGR to 2031.
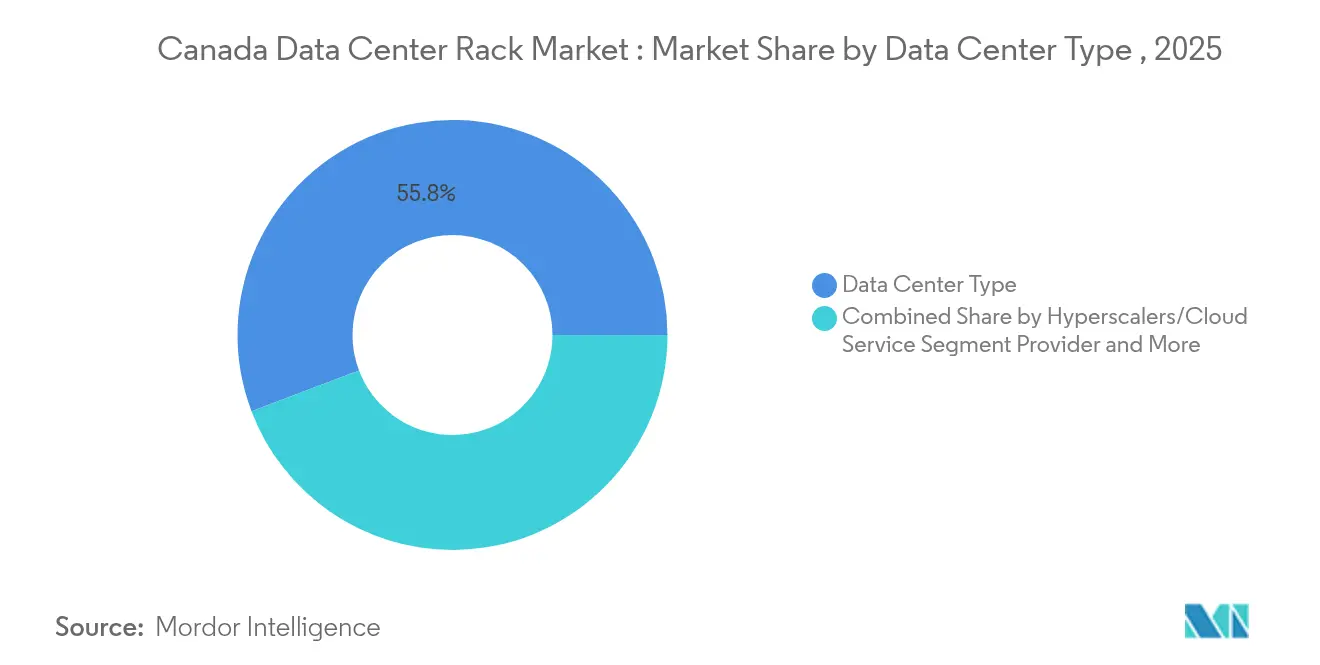
- By data-center type, Hyperscale/Cloud Service Provider deployments are advancing at 16.84% CAGR, even as Colocation Facilities captured 55.77% of the Canada data center rack market size in 2025.
- By material, Steel racks dominated with 77.66% share in 2025, but Aluminum solutions are expanding at 13.98% CAGR on the back of liquid-cooling retrofits.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Canada Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cloud-first enterprise and SMB IT strategies | +2.8% | National (Toronto, Montréal, Vancouver) | Medium term (2-4 years) |
| Hyperscale and AI rack-density leap (≥60 kW/rack) | +3.2% | Alberta, Ontario, Quebec | Short term (≤ 2 years) |
| Provincial data-sovereignty mandates (PIPEDA, Bill C-27) | +2.1% | National (focus on Quebec, Ontario) | Long term (≥ 4 years) |
| Surge in colocation capacity commitments through 2027 | +2.4% | Toronto, Montréal, Calgary, Vancouver | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Cloud-First Enterprise and SMB IT Strategies
Canadian firms are embedding hybrid-cloud architectures that blend on-premises racks with direct links to hyperscale nodes, driving uniform 42U-48U cabinets that suit edge and core alike. The federal CAD 700 million AI Compute Challenge is accelerating adoption of GPU-dense clusters that must reside close to users for latency reasons, especially in secondary metros such as Calgary and Edmonton. SMBs are shifting capex to opex by leasing colocation racks, pushing operators to standardize heights and power distribution for quick scale-up. Major cloud providers’ metro edge programs now specify pre-certified racks that can slide into regional facilities with minimal electrical work. This convergence is underpinning steady demand for flexible, cloud-attached enclosures across the Canada data center rack market.
Hyperscale and AI Rack-Density Leap (≥60 kW/rack)
Artificial-intelligence workloads are forcing hyperscalers to exceed 100 kW—and, in pilot programs, 250 kW—per rack, a step-change from legacy 10-15 kW norms. The University of Calgary’s CCIT hall already operates 20 cabinets totaling 600 kW with integrated rear-door heat exchangers. Hyperscalers are ordering custom frames that marry liquid distribution units, busbar power trunks and structural reinforcement in a single bill of materials, slashing floor-space per petaflop. Vendors able to factory-install manifolds and quick-disconnect lines are winning contracts because they shorten on-site commissioning. As AI density rises, cabinet strength and fire suppression systems must also evolve, spawning retrofit opportunities for seismic-rated, high-load frames in existing Canadian halls.
Provincial Data-Sovereignty Mandates (PIPEDA, Bill C-27)
Bill C-27 and the proposed Artificial Intelligence and Data Act impose strict residency rules for personal data, spurring banks and hospitals to favor domestic hosting.[2]Government of Canada, “Bill C-27: Digital Charter Implementation Act,” canada.ca Quebec’s Act 25 adds provincial layers that restrict cross-border transfers in sectors like fintech and life sciences. These requirements channel workloads into compliant facilities, creating a captive market for racks inside Canadian borders. Public agencies are embedding residency clauses in procurement, locking in long-term demand for regional colocation suites equipped with tamper-proof cabinets and audit-ready monitoring. As regulators finalize enforcement frameworks, operators expect a multi-year uplift in AI-ready, compliance-certified rack orders across the Canada data center rack market.
Surge in Colocation Capacity Commitments Through 2027
Vacancy below 4% in Toronto and Montréal has triggered a build-boom: eStruxture’s eight-site Aptum purchase pushes its footprint past 100 MW, while its Calgary AI campus is budgeted at CAD 750 million for 130 kW per rack formats . Grain Management’s Brampton expansion from 2.5 MW to 20 MW illustrates how metro Toronto sites are scaling by an order of magnitude. Developers want standardized cabinets, PDUs and containment that can ship in modules for multi-site rollouts. Suppliers offering bundled rack-power-cooling kits are securing multiyear frame agreements that anchor recurring revenue in the Canada data center rack market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Scarcity of 10-20 MW power parcels in Toronto core | -1.9% | Greater Toronto Area | Short term (≤ 2 years) |
| Lengthy provincial permitting for water-based cooling loops | -1.2% | Ontario, Quebec, Alberta | Medium term (2-4 years) |
| Skilled-labour gap for high-density rack commissioning | -0.8% | National (Calgary, Vancouver) | Long term (≥ 4 years) |
| Steel/aluminum import tariffs driving rack CAPEX volatility | -1.1% | National (manufacturing in Ontario) | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Scarcity of 10-20 MW Power Parcels in Toronto Core
The Independent Electricity System Operator warns that securing substation access in downtown Toronto now entails multi-year queue positions. Hyperscalers are splitting loads into clusters across Mississauga and Hamilton, increasing the count of smaller halls rather than one big farm. Each site needs identical racks to simplify logistics, benefiting vendors of pre-engineered cabinets that deploy anywhere on short notice. Power scarcity also propels edge micro-data-centers that fit within existing retail and office footprints, again boosting orders for compact enclosed racks in the Canada data center rack market.
Steel/Aluminum Import Tariffs Driving Rack CAPEX Volatility
Canada’s 25% surtax on Chinese metals adds unpredictable cost swings to rack bills of material.[3]Department of Finance Canada, “Countermeasures on Imports of Steel and Aluminum Products,” canada.ca OEMs are dual-sourcing panels from USMCA mills, but conversion lines must re-tool for alternative alloys, stretching lead-times. Aluminum cabinets—lighter and more thermally conductive—offset shipping and cooling costs, partially neutralizing tariff headwinds, yet price indexing in colocation contracts is rising. Suppliers with domestic sheet-metal fabs are locking in volumes, while buyers hedge with forward-purchased inventory, affecting working capital across the Canada data center rack market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full Rack Dominance Driven by AI Workloads
Full Rack units commanded 73.62% of revenue in 2025 and will grow 14.02% annually as AI clusters require full-height frames with integrated manifolds. This dominance places Full Rack formats at the core of the Canada data center rack market size discussion, especially when hyperscalers standardize on 48U full cabinets that deliver consistent airflow and power anchoring. Quarter and Half Rack offerings remain relevant for edge closets but contribute marginal revenue compared with AI-dense cores.
Most hyperscale requests for proposal now bundle racks, rear-door heat exchangers and busbar distribution as a single SKU. Colocation operators mirror this design to accommodate unknown future tenants. Suppliers achieving economies of scale around full-size frames are improving margins even while raw-material prices fluctuate, reinforcing the competitive moat in the Canada data center rack market.


By Rack Height: 48U Emerging as AI-Optimized Standard
Though 42U cabinets hold 55.98% of 2025 revenue, 48U units are accelerating at 14.92% CAGR and are forecast to capture a sizable share of the Canada data center rack market size by 2031. The extra six rack units accommodate in-row pump skids and overhead busways without sacrificing server count.
Operators deploying NVIDIA H100 and forthcoming B100 accelerators often choose 48U to house both compute nodes and coolant distribution in one enclosure. With liquid loops rising, 48U allocations future-proof floorspace while avoiding custom height extensions that complicate containment design. Compact 38U and 52U specials continue to support telecom or seismic zones, yet bulk demand is clustering around the two mainstream heights, helping integrators streamline part numbers and logistics.
By Rack Type: Cabinet Solutions Lead Cooling Integration
Cabinet (Closed) frames captured 71.05% of 2025 spending and will outpace the broader Canada data center rack market at 15.88% CAGR. Enclosed sides allow direct-to-chip circuits and rear-door heat exchangers to run safely, preventing condensation in aisles.
Large colocation providers are layering biometric doors and branch-circuit monitoring into sealed cabinets, selling them as premium “AI suites.” Open-frame racks still serve network corridors where airflow is king and security is less stringent, but their share is eroding as more workloads become power-intensive. Wall-mount enclosures address 5G edge shelters and industrial IoT nodes, yet remain a niche use case relative to sealed cabinets.
By Data Center Type: Hyperscale Growth Outpaces Traditional Segments
Colocation halls led revenue with 55.77% of the Canada data center rack market size in 2025, yet Hyperscale/Cloud deployments are sprinting ahead at 16.84% CAGR. Hyperscalers demand integrated liquid-cool-ready frames that drop into robot-assisted loading bays.
Colos are countering by offering dedicated AI halls, requiring the same specialized cabinets. Enterprise on-prem still matters in regulated verticals like healthcare, but spending tilts toward hybrid racks hosting both private GPUs and cloud-link routers. Edge micro-sites in retail or cell-tower compounds prioritize lightweight, pre-cabled racks sized for elevator transport.
By Material: Aluminum Gains Traction in High-Density Applications
Steel still rules with 77.66% share, but Aluminum is climbing at 13.98% CAGR as operators value lower weight when floors must support 130 kW cabinets. The Canada data center rack market share shift toward Aluminum matches the switch to liquid cooling, where thermal conductivity improves exchanger efficiency.
Vendors investing in aluminum welding lines are shortening lead-times because the metal machines faster than cold-rolled steel. Composite racks serving electromagnetic-sensitive labs remain tiny yet profitable, signaling future diversification possibilities if AI inference expands into healthcare imaging suites and autonomous-vehicle test rigs.
Geography Analysis
Ontario remains the largest provincial buyer thanks to Toronto’s finance and tech demand, but grid congestion has lengthened interconnection queues and raised power costs, nudging capacity into Hamilton and Kitchener. Québec’s hydroelectric surplus and renewable portfolio attract hyperscalers seeking ESG credentials; Hydro-Québec’s unlock of additional industrial rates is spurring multi-hundred-megawatt campuses near Montréal.
Alberta is the fastest-growing node in the Canada data center rack market, leveraging deregulated power and abundant natural gas to entice CAD 75-100 billion in planned data-center capital by 2030. eStruxture’s Calgary campus typifies 130 kW racks cooled by rear-door exchangers, showcasing how local energy expertise translates into data-center engineering. Edmonton’s emerging AI health-research corridor is also driving regional rack orders.
British Columbia leverages hydro assets and Pacific fiber routes to pitch itself as a low-latency CDN hub; racks here often integrate seismic bracing and liquid loops suited for temperate diets. The Maritime provinces court edge workloads linked to offshore wind projects, requiring compact enclosures that withstand salt air. Nationwide, the Canada data center rack market sees policy differences on water-loop permits and clean-energy credits, compelling suppliers to customize cabinet ancillaries by province.
Regulatory Landscape
Canada's data center rack deployments are shaped by privacy and data-residency obligations under PIPEDA, with additional provincial requirements such as Quebec's Act 25 influencing where regulated workloads can be hosted and, in turn, where rack capacity is procured. On the foreign investment side, the Investment Canada Act has been applied more actively to sensitive technology areas (including AI and digital infrastructure), adding review and filing considerations for large-scale, foreign-backed data center expansions and the associated rack, power, and cooling supply packages.
Energy access and environmental permitting increasingly influence rack design decisions because they constrain which sites can electrify and commission high-density halls. In early 2026, British Columbia introduced the Data Centre Facility and Hydrogen Production Facility Power Supply Regulation (B.C. Reg. 8/2026), which limits new electricity capacity available to conventional data centers to an aggregate 100 MW over two years. This cap pushes proponents toward higher-efficiency builds and tighter power allocation per cabinet. Parallel provincial approaches around industrial tariffs, water-based cooling loop approvals, and Indigenous consultation, especially in British Columbia, reinforce the need for compliant, auditable rack systems (metering, security, monitoring) that align with site approval conditions.
Value Chain Analysis
The Canada data center rack value chain starts with raw materials and fabrication (steel and aluminum sheet, structural members, fasteners, coatings), followed by cabinet OEM engineering for high-load frames, doors, containment, and accessory ecosystems (rails, cable management, blanking, and security). As rack densities move beyond 60 kW per rack for AI, adjacent component suppliers become integral to the rack bill of materials, including busway or busbar power distribution, intelligent PDUs, liquid distribution units, rear-door heat exchangers, leak detection, and in-cabinet sensing. Systems integrators then package these inputs into repeatable deployment kits for hyperscale and colocation customers.
Downstream, engineering firms, contractors, and commissioning specialists translate rack specifications into floor layouts, structural anchoring, and power and cooling hookups, before handing them over to colocation operators and enterprise users for ongoing operations and compliance reporting. Standards and guidance shape procurement and acceptance testing, including CSA Group data center infrastructure baselines (for example, CSA C510:21) and Natural Resources Canada best-practice guidance for Canadian data centres. Together, these frameworks set requirements around energy performance, measurement, and maintainability. Supply risk also concentrates in specialized inputs needed for AI halls, such as semiconductors and optical components that drive server and network configurations, which encourages buyers to favor vendors that can secure multi-supplier sourcing and pre-integrate rack-power-cooling assemblies to reduce site labor bottlenecks.
Competitive Landscape
Global OEMs control the top tier, yet the field stays moderately fragmented as local metal-fabrication shops protect regional accounts. Schneider Electric’s EUR 38 billion 2024 turnover included 24% from data-center buyers, and its Motivair acquisition cements liquid-cooling depth.[1]Schneider Electric, “Q1 2025 Revenues,” se.com Vertiv printed USD 8.0 billion in 2024 sales and entered 2025 with a USD 7.9 billion backlog after sealing AI-platform alliances. Eaton’s USD 1.4 billion Fibrebond purchase extends from power gear to enclosures, giving it cradle-to-grave supply for hyperscale bids.
Competitive differentiation now hinges on turnkey delivery—factory-cabled racks, coolant loops, smart PDUs and DCIM sensors shipped as one crate. Players with domestic sheet-metal mills dodge tariff exposure and shorten lead-times, winning colocation rollouts that demand 300-cabinet drops inside three weeks. Regional fabricators lacking cooling know-how risk relegation to build-to-print orders.
Vendor roadmaps converge on Open Compute Project-compatible frames to woo hyperscale giants, alongside AI-ready cabinets that integrate leak-detection, micro-channel plates and structured cabling. Compliance modules for Bill C-27 record-keeping and ESG scoring provide further stickiness. M&A remains likely among mid-range players seeking scale, especially those with limited aluminum tooling.
Canada Data Center Rack Industry Leaders
Rittal GMBH & Co.KG
Schneider Electric SE
Vertiv Group Corp.
Eaton Corporation plc
Dell Technologies Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
High-density AI builds and retrofits are creating whitespace for factory-integrated, liquid-cooling-ready rack platforms that reduce on-site labor and compress commissioning timelines, particularly where a skilled-labor gap slows high-density deployment. Canada-specific signals include the University of Calgary's CCIT hall operating 20 cabinets totaling 600 kW with integrated rear-door heat exchangers, alongside colocation expansion designs targeting 130 kW per rack formats. Vendors that can bundle cabinets with validated power distribution (busway or busbar, intelligent PDUs) and coolant-ready features (manifolds, quick disconnects, leak detection) are better positioned to win multi-site frame agreements as operators standardize repeatable AI suites.
Power-allocation and policy constraints also support opportunities for rack designs that maximize compute per constrained megawatt and enable compliance-grade monitoring. British Columbia's B.C. Reg. 8/2026 caps new electricity capacity for conventional data centers at 100 MW over two years starting in early 2026, which favors efficiency-oriented builds and more granular metering and control within cabinets. On the demand side, federal programs aimed at expanding domestic AI compute, including the CAD 700 million AI Compute Challenge referenced in market drivers, increase the priority of Canadian-hosted, high-density infrastructure that aligns with data-residency requirements. Overall, these factors point to opportunities for North American supply chains to manage tariff-driven metal cost volatility, and for rack suppliers that can certify against Canadian standards and deliver modular, auditable deployments across Ontario, Quebec, Alberta, and British Columbia.
Recent Industry Developments
- May 2026: Schneider Electric reports phased delivery of over $290 million in AI infrastructure solutions, including NetShelter racks and Motivair liquid cooling, to Terawulf's Lake Mariner campus. The initiative highlights direct AI data center rack infrastructure demand and reinforces leadership in high-density racks and integrated cooling for AI deployments.
- March 2026: Siemens and Rittal form a strategic partnership to develop standardized power distribution systems for data centers targeting rack densities over 100 kW. The collaboration accelerates standardization for high-density AI ready architectures and may shift supplier dynamics for the Canadian market.
- March 2025: eStruxture begins a 55H Brampton expansion from 2.5 MW to 20 MW, engineering racks for 130 kW AI loads. This expands Canada specific data center capacity and signals demand for factory integrated AI ready racks in Canada.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market covers revenue generated from selling data center racks used inside Canadian data centers, including rack cabinets and open-frame designs used to house IT equipment and support safe installation.
Scope exclusions: We exclude servers, networking gear, power and cooling equipment, and facility construction spend, even if those items are procured in the same build cycle.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (?52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Our desk research started by mapping Canada data center build activity and operating footprint, then translating that into rack demand signals. We referenced public datasets and official publications such as Statistics Canada, the Canada Border Services Agency trade statistics, the National Research Council of Canada, and peer-reviewed energy and cooling studies that discuss data center efficiency and density trends.
To ground the supply side, we reviewed company filings, investor presentations, product catalogs, and reputable press coverage tied to Canadian expansions and retrofit projects. In a few places, paid subscriptions that track company financials, patents, and shipment-level import data were used to sanity check pricing bands and trade flows. These examples are illustrative only, and we relied on other source types for data collection, validation, and research clarification.
Primary Interviews and Surveys
Primary interviews and surveys were used to confirm which rack types are actually being purchased in Canada, how densities are changing, and how buyers treat accessories and integration services in their budgets. We spoke with a mix of manufacturers, distributors, systems integrators, colocation operators, and enterprise facility teams across major Canadian data center corridors to test assumptions and close data gaps before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 37% | CXOs: 13% |
| Mid tier: 48% | Functional/Unit leaders: 32% |
| Smaller Players: 15% | Managers: 55% |
Market-Sizing & Forecasting
Sizing was built using a mix of top-down and bottom-up checks, and the steps were kept repeatable even when public data is limited. On the top-down side, Canada data center expansion signals were translated into rack demand using typical rack counts per IT load, new hall additions, and refresh and replacement cycles. That demand was then valued using pricing ranges observed across standard and customized racks.
Key inputs that shape the model include rack unit heights (such as 42U, 45U, 48U, and custom), the share shift toward enclosed cabinets versus open frames, steel price movement that affects rack bill of materials, higher power density adoption that pushes demand for stronger frames and airflow features, and the pace of colocation capacity additions. For a reasonableness check, we used selective bottom-up approximations, including sampled ASP x volume checks through channels, distributor feedback on mix shifts, and supplier revenue context where disclosure allowed. When granular volume detail was not available, gaps were handled using bounded ranges that were tightened after interview validation.
Forecasting relied on scenario analysis supported by simple multivariate relationships, where variables like data center pipeline timing, density trend direction, and pricing inflation were stress-tested. Final growth paths were adjusted only after primary respondents confirmed that the demand drivers matched what they are seeing in procurement cycles.
Data Validation & Update Cycle
Outputs are validated through triangulation across independent signals, and then checked for unusual jumps by year or rack category that could point to a modeling issue. If variances are found, assumptions are re-tested, and follow-up calls are triggered with the relevant respondent group to confirm what changed.
Before sign-off, the model and conclusions go through multi-step analyst reviews. This includes a separate pass that checks units, currency timing, and whether exclusions were applied consistently across all tables. Reports are refreshed annually, with interim updates for material events such as large facility announcements, sharp metals price moves, or sudden shifts in rack density expectations. Just before delivery, a fresh review is completed so clients receive the latest updated view.
麻豆视频's Canada Data Center Rack Market Size Compared With Other Published Estimates
Published market sizes for Canada data center racks can diverge because sources do not always count the same items, they pick different base years, and they apply different pricing and replacement assumptions. Some estimates begin from broader data center infrastructure spending and then allocate a share to racks, which can pull in value that is not tied to rack product revenue.
A second driver is how pricing and product mix are treated, since some sources bundle accessories, integration labor, or white-space fit-out elements into the rack number, then apply escalation that is not checked against shipment or channel indicators. Other sources do the opposite and rely on a global-to-country split that does not reflect Canada-specific colocation build timing or cabinet share. Some estimates fold in installation and rack-adjacent fit-out costs. 麻豆视频 counts only rack hardware sales in Canada, using rack type mix and density-linked configuration shifts as the main sizing anchors.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 32.51 M (2025) | |
| Regional Consultancy A | USD 178.41 M (2025) | Uses a broader racks spend concept that appears to bundle a wider set of rack-related systems and project add-ons, which increases the value captured per deployment. |
| Trade Journal B | USD 98.45 M (2025) | Applies a standardized country allocation from global rack totals and a lower assumed cabinet mix, which can miss Canada-specific colocation build timing and pricing differences. |
Across the three numbers, the main gap comes from what is included in the rack value line and how much is assumed per deployment, not from a disagreement that racks are growing in Canada. When the scope is limited to rack products and the inputs are tied back to rack heights, cabinet versus open-frame mix, and realistic replacement timing, the result can be followed and rechecked in a repeatable way.


Key Questions Answered in the Report
What is the current size of the Canada data center rack market?
The market is valued at USD 36.79 million in 2026 and is on track to hit USD 68.32 million by 2031.
Which rack configuration leads Canadian demand?
Full Rack units dominate with 73.62% market share in 2025 thanks to AI workloads requiring full-height, high-density cabinets
Why are 48U racks gaining popularity?
They provide extra vertical space for liquid-cooling manifolds and power gear, supporting densities above 60 kW per rack while future-proofing new builds.
How do data-sovereignty laws influence rack purchases?
Bill C-27 and provincial privacy acts force sensitive datasets to stay in Canada, driving domestic colocation spending and boosting demand for compliant racks.
Page last updated on:
- Data Center Server Market Servers worldwide, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Construction Market Construction across all regions, split by tier, facility size and facility type.
- Canada Data Center Cooling Market Cooling in Canada, split by facility type, tier and cooling technology.
- Canada Data Center Construction Market Canada construction, split by tier.
- Canada Data Center Physical Security Market Physical security in Canada, split by solution type and service type.
- France Data Center Water Consumption Market Water use in France, split by cooling technology, facility type and water source.
- Canada Data Center GPU Market GPUs demand across Canada, covering deployment type, gpu type and interconnect.
- South Africa Data Center Server Market South Africa's servers, split by data-center tier, form factor and application / workload.
- Canada Data Center Storage Market Storage demand across Canada, covering storage technology, storage type and facility type.
- Data Center Switch Market Switches across all regions, split by switch type, bandwidth class and switching technology.



