
Canada Location-Based Services Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 1.35 Billion |
| Market Size (2026) | USD 1.56 Billion |
| Market Size (2031) | USD 3.26 Billion |
| Growth Rate (2026 - 2031) | 15.84 % |
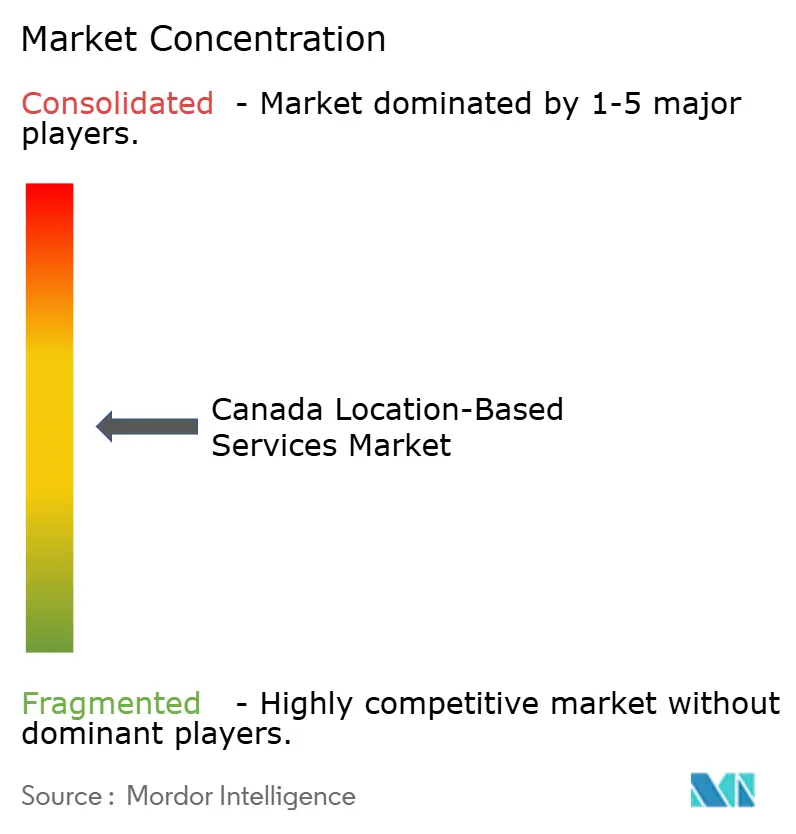
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Canada Location-Based Services Market Analysis by 麻豆视频
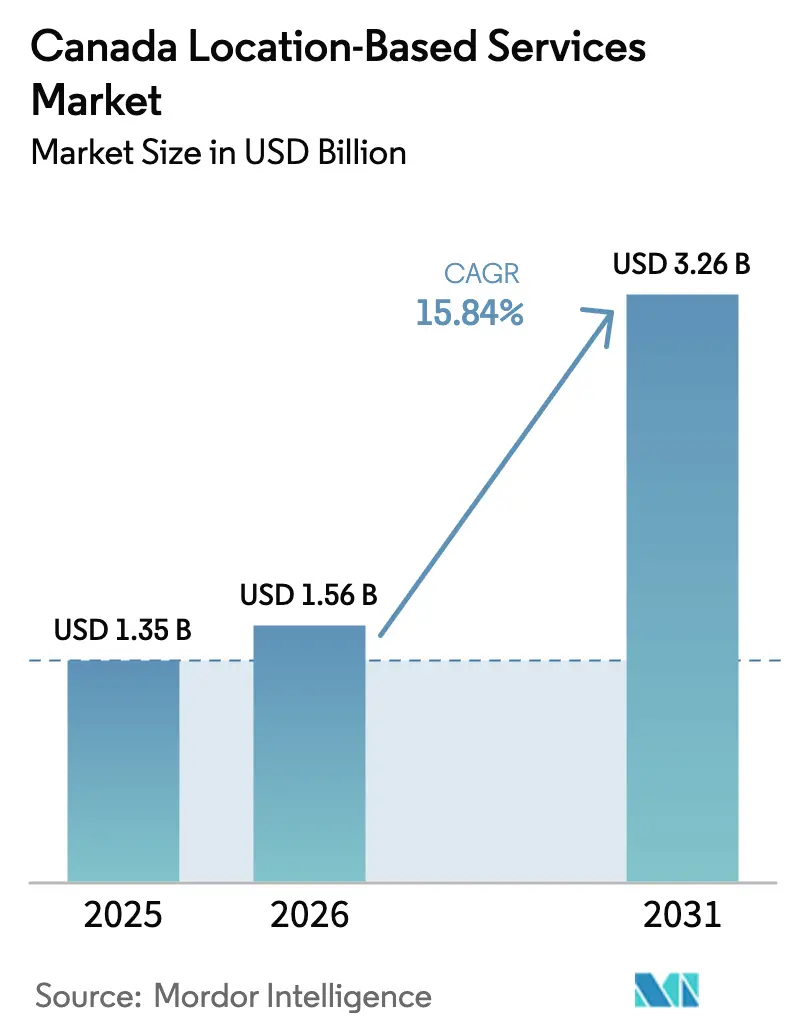
The Canada Location-Based Services Market size was valued at USD 1.35 billion in 2025 and estimated to grow from USD 1.56 billion in 2026 to reach USD 3.26 billion by 2031, at a CAGR of 15.84% during the forecast period (2026-2031).
Growth rests on sustained network capital expenditure by the country’s three national carriers, rapid smartphone adoption that lifts mobile data consumption, and public-sector investments in smart-city infrastructure. Indigenous data sovereignty frameworks—especially OCAP principles—shape solution design, while the delay in federal privacy reform has postponed tighter compliance costs yet heightened uncertainty. Hardware supply-chain pressures continue to elevate component prices, but they also spur service-centric business models that better absorb volatility. Competitive intensity is moderate as telcos safeguard core connectivity revenues and specialist vendors expand through vertical alliances, leaving ample opportunity for niche innovators in precision agriculture, indoor positioning, and remote healthcare applications.
Key Report Takeaways
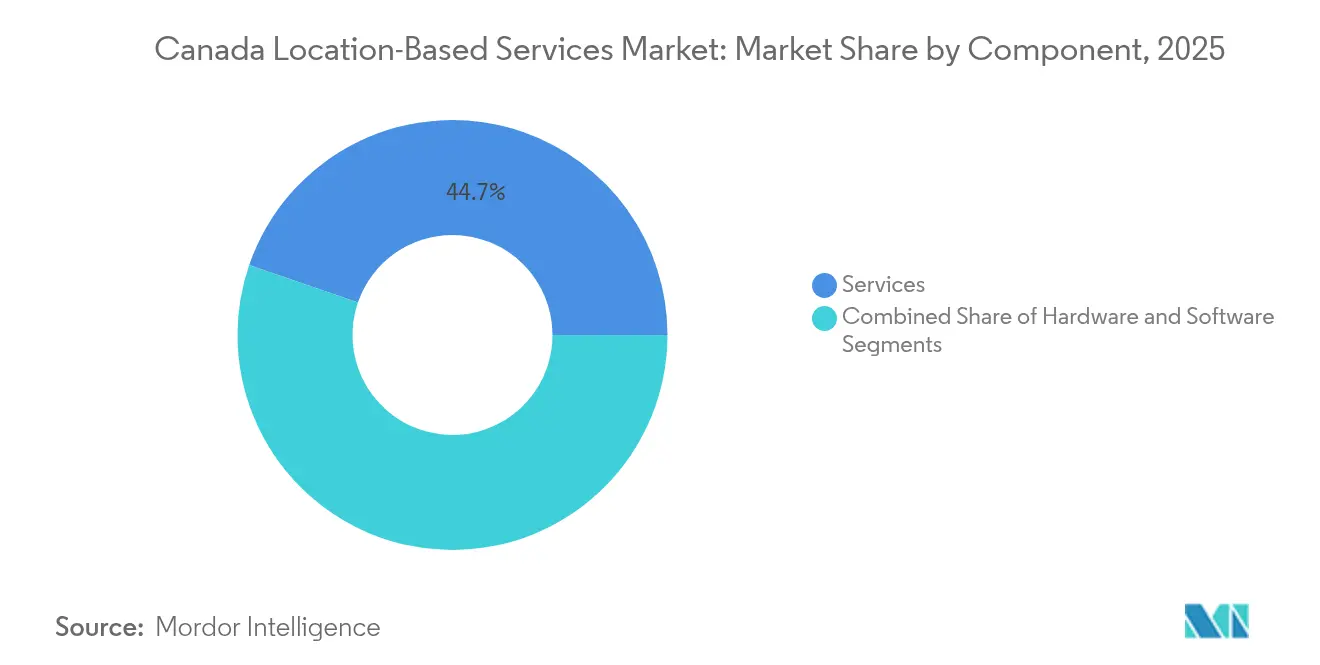
- By component, services held 44.73% of the location-based services market share in 2025; hardware is forecast to expand at a 10.12% CAGR to 2031.
- By location, outdoor deployments commanded a 62.95% share of the location-based services market size in 2025, and indoor positioning is advancing at a 11.62% CAGR through 2031.
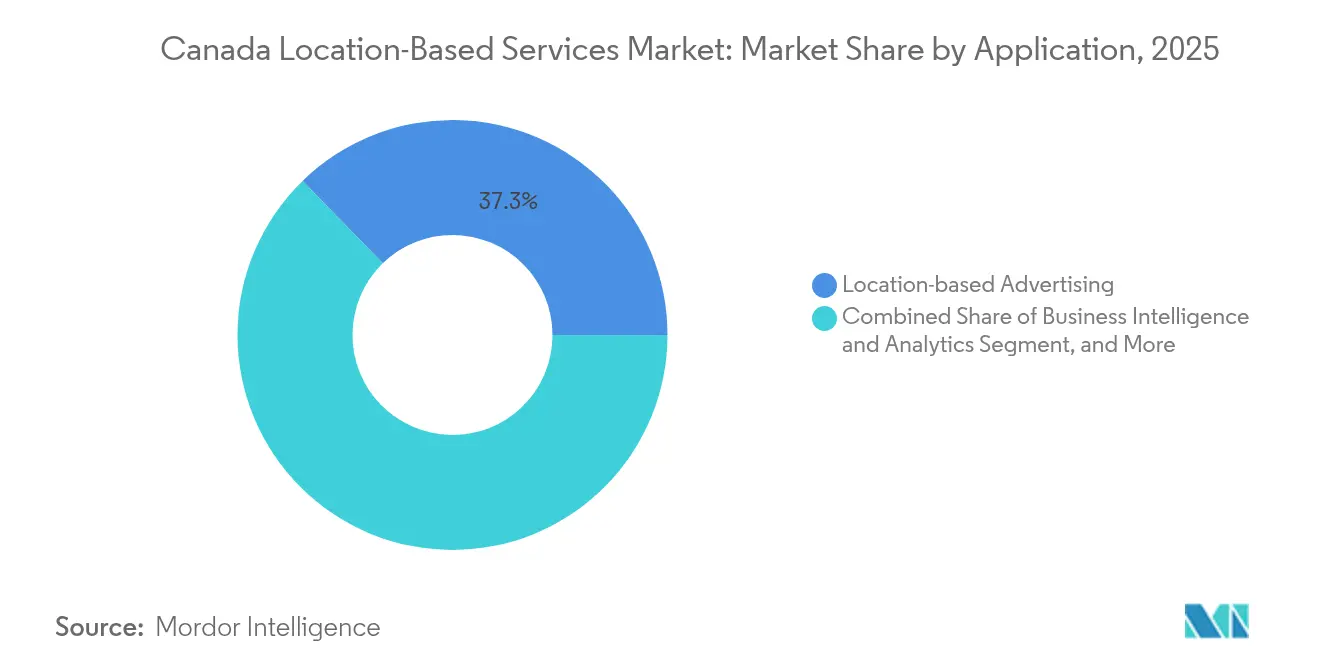
- By application, location-based advertising led with 37.28% of revenue in 2025, while social networking and entertainment applications are projected to grow at a 13.08% CAGR to 2031.
- By end-user industry, transportation and logistics accounted for 40.35% of the location-based services market size in 2025, and healthcare is progressing at a 12.08% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Competitive positioning in Canada includes both locally based firms and those operating across multiple regions. The market landscape in the global location based services industry research shows how these players are arranged internationally.
Canada Location-Based Services Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid smartphone and cheap-data penetration | +3.2% | National, with urban concentration in Toronto, Vancouver, Montreal | Short term (≤ 2 years) |
| IoT uptake in transportation and logistics | +2.8% | National, with early gains in Alberta agriculture, Ontario manufacturing | Medium term (2-4 years) |
| Smart-city and public-safety mandates | +2.1% | Provincial leadership in BC, Ontario, Quebec municipalities | Medium term (2-4 years) |
| Indoor positioning tech (BLE/UWB) rollout | +1.9% | Urban centers, healthcare facilities, retail complexes | Long term (≥ 4 years) |
| Indigenous data-sovereignty push | +1.5% | Northern territories, First Nations lands, rural communities | Long term (≥ 4 years) |
| Precision-agriculture geo-fencing demand | +1.3% | Prairie provinces, agricultural regions across Canada | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Rapid Smartphone and Cheap-Data Penetration
Mobile revenue reached CAD 59.6 billion in 2023, with retail data up 6.6%, a trajectory that underpins most consumer-facing location applications [1]Canadian Radio-Television and Telecommunications Commission, “Communications Market Report 2025,” crtc.gc.ca. Subscriber usage rose 21.3% year on year, translating into richer contextual datasets that ad-tech platforms monetize. Carrier bundles that blend connectivity with value-added location analytics lift average revenue per user and deepen customer retention. Rogers’ satellite-to-mobile pilot, already covering 5.4 million km?, further enlarges the addressable base in previously dark zones. The resulting network breadth allows emergency text-to-911 and asset-tracking services to flourish where traditional towers were never economically viable.
IoT Uptake in Transportation and Logistics
Fleet managers adopt telematics to mitigate rising fuel and maintenance costs. TELUS Farm Fuel Management Solution pairs cellular IoT hubs with sensor probes so growers can locate tanks and schedule refills in real time [2]North Star Systems, “TELUS Farm Fuel Management Solution,” northstarsystems.ca. Geotab’s mixed-fleet module now integrates electric vans and heavy trucks, letting dispatchers benchmark utilization across Rivian, Volkswagen, and legacy assets. In agriculture, variable-rate seeding based on GNSS feedback reduces fertilizer waste across 160 million acres of Canadian cropland. Supply-chain chip shortages have doubled NFC lead times, but recurring software fees shield IoT platform vendors from hardware margin swings.
Smart-City and Public-Safety Mandates
Municipalities view traffic analytics as a lever to trim congestion and emissions. Edmonton’s Smart Roads project already layers sensor data onto adaptive signal cycles, improving corridor travel times. Toronto’s 5G-enabled cameras alert operators to blocked intersections, complementing pedestrian flow metrics gathered from curbside small cells. Standardized permit fees—USD 2,000 per smart-pole plus USD 250 annual upkeep—give cities predictable cost recovery. Such open data policies attract app developers that repurpose feeds for micromobility routing and accessibility mapping, reinforcing the location-based services market ecosystem.
Indoor Positioning Tech Rollout (BLE/UWB)
Mapsted’s software-only engine maps RF fingerprints across 8 million m? of Canadian real estate without extra beacons, lowering retrofit hurdles. Hospitals still favor beacon kits for sub-3 m accuracy; one Montreal facility mounted 1,200 BLE nodes over 60,000 m? and cut lost-equipment spend by digitizing asset locations. Apple’s second-generation U2 chip, fabricated on 7 nm tech, boosts UWB range and throughput, a leap that phone OEMs can exploit for centimeter-level indoor navigation. Shipments of UWB radios are on a path to 7.5 billion units by 2025, pushing venue owners to future-proof physical spaces with multi-protocol networks.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent privacy acts (PIPEDA, C-27) | -2.4% | National, with Quebec leading provincial regulations | Short term (≤ 2 years) |
| Indoor multipath accuracy limits | -1.8% | Urban centers, dense building environments | Medium term (2-4 years) |
| Sparse-north cartography cost burden | -1.3% | Northern territories, remote regions | Long term (≥ 4 years) |
| Carrier-billing rule changes | -0.9% | National, affecting all telecommunications providers | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Stringent Privacy Acts (PIPEDA, C-27)
Bill C-27 remains in legislative limbo, yet its draft clauses on automated decision-making already influence product roadmaps. The Office of the Privacy Commissioner’s “No-Go Zones” explicitly bars location profiling that could enable discrimination, compelling providers to embed differential privacy and on-device processing. Quebec’s anonymization rule forces firms to document re-identification risk, an overhead that weighs more heavily on startups than on telcos with in-house compliance teams. Some vendors now market sovereign-cloud instances hosted within provincial borders to reassure public-sector buyers. Although compliance raises costs, vendors that master privacy-by-design gain a competitive moat as enterprises seek turnkey solutions.
Indoor Multipath Accuracy Limits
Radio reflections inside steel-reinforced buildings still hamper sub-meter precision. Controlled trials in Canadian emergency wards report a 66 cm mean deviation using BLE trilateration, a gap unacceptable for clinical asset tracking, where infusion pumps must be found within seconds. Advanced algorithms that harness non-line-of-sight paths deliver gains but demand high-density antennas and intensive calibration. The capital cost to blanket a 50,000 m? mall can exceed USD 250,000 when factoring in beacon hardware and annual battery swaps. Accuracy constraints, therefore, limit uptake in safety-critical scenarios and temper the overall growth of the location-based services market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Component: Services Anchor Adoption as Hardware Volatility Persists
Services held 44.73% of 2025 revenue, benefiting from predictable subscription contracts and outsized demand for integration expertise. Falling sensor prices narrow the total cost of ownership, yet chip shortages have doubled delivery times for NFC controllers and pushed some SKUs to 2,100% price hikes. Platform vendors insulate clients from these shocks by offering device-agnostic location stacks delivered via managed-service models. Hardware innovators leverage advanced foundry nodes; Apple’s 7 nm UWB die sets a benchmark that mid-tier IC houses must match to stay relevant. Software upgrades spread AI features that enrich context, such as Fraser Health’s digital-twin model that re-creates regional patient flows and guides resource allocation. With USD 100,000–200,000 required for a single 5G macro cell, enterprises prefer opex-driven service contracts, reinforcing the dominance of this component within the location-based services market.
Rising compliance spending also favors service providers able to certify privacy workflows. Many SMEs outsource data-retention audits and consent management, further baking services revenue into long-term operating budgets. Consequently, the location-based services market size for services is forecast to climb from USD 699.12 million in 2026 to USD 1.13 billion by 2031, translating into a 9.98% CAGR.


By Location: Indoor Breakout Accelerates as Use-Cases Mature
Outdoor deployments accounted for 62.95% of 2025 spending thanks to satellite and cellular coverage that now spans almost the entire populated landmass. Rogers’ satellite-to-mobile beta adds 2.5× more footprint than traditional towers, widening the public-safety and asset-tracking opportunity. Indoor positioning, however, registers the quickest climb at a 11.62% CAGR. Hospitals, airports, and retail chains pilot BLE beacons that knit wayfinding, occupancy analytics, and logistics into unified dashboards. The location-based services market share for indoor solutions is projected to surge from 37.05% in 2025 to close to parity with outdoor by 2031.
Software-only approaches lower capital barriers. Mapsted’s RF fingerprinting eliminates beacon hardware, while TDK’s geomagnetic SDK turns existing smartphone sensors into navigation beacons. Despite accuracy headwinds from multipath, emergent multi-modal fusion—combining UWB, BLE, Wi-Fi RTT, and visual odometry—promises sub-30 cm precision in dense venues. As retailers shift to phygital models that blur online and in-store journeys, footfall analytics teams increasingly rely on indoor heatmaps to optimize merchandising.
By Application: Entertainment and Social Networking Redefine Growth
Location-based advertising captured 37.28% of 2025 value, buoyed by Google Services’ USD 76.5 billion quarterly haul. Privacy shifts that limit third-party cookies pivot ad spend toward first-party location signals, keeping revenue robust. Social networking and entertainment apps are forecast to outpace advertising with a 13.08% CAGR, driven by augmented-reality games and immersive media that hinge on centimeter-level positioning. Niantic’s accelerated coordinate encoding shrinks world-scale AR map generation from hours to minutes, unlocking event-based campaigns that overlay digital quests onto real streets.
Mapping and navigation remain essential, but now emphasize live context. HERE Technologies and AWS committed USD 1 billion to stream HD maps for autonomous mobility, opening APIs that developers can embed into business-intelligence dashboards. Enterprise analytics increasingly rely on geofencing to align staffing with local demand or to time restocking cycles. Patent filings from Meta, Samsung, and Apple point to gesture-aware indicators and metaverse locators that will further blur physical-digital boundaries, broadening the application canvas inside the location-based services market.
By End-User Industry: Healthcare Outstrips Transport on Telemonitoring Boom
Transportation and logistics retained 40.35% of 2025 revenue as fleets adopted mixed-asset telematics and farmers optimized inputs across 160 million acres. Geotab’s OEM alliances with Volkswagen and Rivian facilitate standardized diagnostics, cutting maintenance downtime. The location-based services market size embedded in transport will still grow steadily but cede share to healthcare, which posts a 12.08% CAGR. Toronto Grace Health Centre already monitors 16,000 chronic-care patients remotely and plans to double coverage by 2026, leveraging GNSS tags and cellular gateways for continuous vitals streaming.
Government verticals accelerate through smart-city rollouts, while BFSI and hospitality deploy indoor positioning to sharpen customer engagement. Precision AI’s drone-sprayer reduces herbicide cost to USD 2.85 per acre, showing agriculture’s appetite for spatial analytics. Manufacturing plants adopt real-time locating systems to orchestrate just-in-time workflows, and public utilities layer asset maps onto outage-management systems to cut restoration times.
Geography Analysis
Canada’s vast 5.4 million km? landmass yields a dual market profile: dense southern corridors exhibit urban use-case saturation, while sparsely populated northwestern regions present connectivity white spaces. Carrier capex commitments—TELUS at CAD 70 billion through 2029 and Rogers at CAD 45 billion since inception—fuel a backbone that supports high-precision geolocation across provinces. Quebec sets the tone for privacy with its 2024 anonymization rules that ripple into neighboring jurisdictions. Ontario’s draft cybersecurity bill layers additional obligations on public bodies, likely prompting harmonization talks. Western provinces leverage LoRa and private-LTE networks for agriculture, while Atlantic Canada pilots maritime asset tracking on hybrid satellite-cellular links.
Indigenous territories, where only 18% have standard cellular reach, now receive attention as Rogers’ direct-to-device service extends text coverage nationwide. OCAP data principles require solution vendors to secure local consent for positional archives, fundamentally influencing architecture design. Remote healthcare programs collaborate with tribal councils to integrate geo-fencing alerts that respect cultural protocols. Northern resource projects, from hydroelectric dams to critical-mineral mines, demand ruggedized GNSS and UWB tags to monitor worker safety in extreme environments, injecting fresh demand into the location-based services market.
Urban leadership centers on Toronto, Vancouver, Montreal, and the Waterloo tech cluster. Municipal RFPs increasingly stipulate open-data access, spurring SMEs to build micro-services on traffic APIs. Startups capitalize on academic-industry links, with Waterloo turning out RF engineers who fuel indoor-mapping breakthroughs. Meanwhile, Saskatchewan farmers adopt satellite NDVI imagery to optimize crop inputs, illustrating how rural throughput upgrades unlock high-value analytics.
麻豆视频 tracks the location based services market across other major regions such as Middle East and Africa, with additional country-level coverage spanning United States, Brazil, United Arab Emirates, Nigeria, Spain, Italy, and South Korea, each reflecting localized structural drivers, restraints and more.
Regulatory Landscape
Canada location-based services providers operate under federal privacy rules led by the Privacy Act (public sector) and PIPEDA (private sector), with oversight and guidance from the Office of the Privacy Commissioner of Canada (OPC). For location data in particular, the OPC's expectations around privacy management programs and privacy impact assessments shape how vendors design consent, retention, and anonymization workflows. Ongoing federal reform discussions, including Bill C-27 referenced in product roadmaps, keep compliance planning active.
Telecom-driven location use cases also face sector regulation. The Canadian Radio-television and Telecommunications Commission (CRTC) issued Telecom Decision 2023-235 approving handset-based location technology for NG9-1-1 implementation, tying deployment to consensus standards for facilities-based wireless service providers. Parliamentary attention to mobility data governance has been visible through the House of Commons ETHI Committee recommendations (May 2022), including calls for clearer rules around de-identified data transparency. That direction adds pressure for auditable anonymization and disclosure practices across ad-tech and analytics use cases.
Value Chain Analysis
The Canada location-based services value chain begins with positioning and network enablers (GNSS and device sensors, BLE/UWB, Wi-Fi, and cellular infrastructure), then moves into connectivity and edge or cloud delivery from national carriers such as Rogers, TELUS, and Bell. Network and platform suppliers, including Ericsson in wireless infrastructure and Esri Canada in GIS and location intelligence platforms, provide foundational capabilities that downstream vendors package into vertical solutions for transportation and logistics, healthcare, government, and smart-city deployments.
Data and workflow layers sit at the center of value creation, covering mapping, geocoding, real-time event ingestion, analytics, and application integration. Systems integrators and managed service providers handle deployment, security hardening, and ongoing operations, while public-sector buyers increasingly shape demand through procurement frameworks. Federal procurement routes administered by Public Services and Procurement Canada (PSPC) via CanadaBuys, alongside mechanisms such as the Government of Canada AI Source List, create structured pathways for vendors to sell location intelligence and adjacent AI capabilities into departments, agencies, and municipalities.
Competitive Landscape
Canada’s location-based services industry comprises a triad of dominant carriers and a constellation of specialist vendors. Rogers, TELUS, and Bell collectively spent more than CAD 120 billion on networks over the past decade, securing latent advantages in spectrum and fiber access. They defend their footprint by bundling device management, edge compute, and privacy consulting. Partnerships amplify reach: Cisco and TELUS target 1.5 million connected vehicles through a 5G mobility platform, while Rogers taps Ericsson for 5G-Advanced features that cement latency leadership.
Verticalmergers specialists drive differentiation. Mapsted delivers hardware-free indoor maps to malls, Jibestream maintains hospital and airport wayfinding suites, and Descartes Systems optimizes last-mile routing for cross-border freight. Patent activity is brisk: Meta’s UWB physical layer header now supports 124.8 Mb/s, Apple’s context-aware AR cues improve user orientation, and Google’s map-aided inertial odometry reduces battery drain during visual positioning. Investors notice: Battery Ventures acquired TrueContext to consolidate mobile field-service workflows, signaling a new phase of merger and acquisitions that could compress fragmentation.
White-space niches emerge in sovereign-cloud location analytics and agricultural drone mapping, where regulatory hurdles and domain complexity limit new entrants. AI overlays become table stakes as Bell builds a 500 MW sovereign AI fabric, offering on-shore inference for privacy-sensitive geodata. Overall, competition tilts toward collaboration: telcos lease APIs, chipmakers release reference designs, and software vendors bundle datasets, driving a layered ecosystem rather than a winner-takes-all race.
Canada Location-Based Services Industry Leaders
Cisco Systems Inc.
IBM Corporation
Ericsson Inc.
Apple Inc.
Esri Canada Limited
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Public safety, emergency response, and transit security programs create clear whitespace for operational location intelligence with governance controls. Edmonton Transit Enhanced Community Safety System (ETECS) is one example. It uses Esri Canada GIS to incorporate real-time sensor and location inputs and was supported by a CAD 1.3 million federal grant (announced October 2025). Another is the City of Guelphs, which received federal funding to build a NENA NG9-1-1 compliant geodatabase (announced February 2023). These projects pull demand toward interoperable geodatabases, real-time dashboards, and indoor-outdoor continuity, while also raising expectations for auditability and privacy-by-design.
Enterprise workflow integration and sovereign deployment options are broadening adoption beyond traditional mapping teams into operations, asset management, and field services. Esri Canada's prequalification on the Government of Canada AI Source List (Band 3) in December 2025 supports federal buying motions for AI-enabled location intelligence engagements up to CAD 9 million, and ISO-certified managed cloud services in Canada reduce operational friction for regulated buyers that want Canadian-hosted environments. On the infrastructure side, federal support for advanced wireless R&D, including a Strategic Innovation Fund contribution of CAD 79.1 million toward Ericsson's CAD 634.8 million project (announced November 2024), reinforces a pipeline of network capabilities (5G-Advanced, 6G research, and AI-driven network management). Vendors can translate these capabilities into higher-precision positioning, lower-latency telemetry, and more scalable location analytics for logistics, healthcare, and smart-city use cases.
Recent Industry Developments
- July 2026: Esri Canada announces ArcGIS for ServiceNow integration, providing bidirectional integration of location intelligence into enterprise workflows. The integration enables broader enterprise adoption of location based services via workflow automation and data interoperability.
- May 2026: Ericsson Canada partners with the Government of Canada to build the Advanced Wireless Communications Innovation Network for public safety, security, and defence. The partnership gives a government led, location enabled 5G infrastructure and contracts, expanding the Canadian LBS ecosystem.
- March 2026: Esri Canada launches ISO certified ArcGIS Managed Cloud Services in Canada to offload deployment and security management for enterprise ArcGIS environments. The service reduces deployment complexity and security burden, accelerating enterprise LBS adoption across sectors.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the Canada location-based services market covers revenue earned from solutions that use a user or asset location (from GPS, cellular, Wi-Fi, or beacons) to deliver information, navigation, tracking, analytics, or location-triggered services to consumers and enterprises.
Scope exclusions: We exclude general telecom connectivity revenue, device resale margins that are not tied to location service delivery, and non-location digital advertising that is not triggered by a verified location signal.
Segmentation Overview
- By Component
- Hardware
- Software
- Services
- By Location
- Indoor
- Outdoor
- By Application
- Mapping and Navigation
- Business Intelligence and Analytics
- Location-based Advertising
- Social Networking and Entertainment
- Other Applications
- By End-User Industry
- Transportation and Logistics
- IT and Telecom
- Healthcare
- Government
- BFSI
- Hospitality
- Manufacturing
- Other End-Users
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the Canada context and keep assumptions aligned with public signals that can be rechecked later. We referenced official datasets and standards sources such as Statistics Canada, the Canadian Radio-television and Telecommunications Commission (CRTC), Innovation, Science and Economic Development Canada (ISED), Natural Resources Canada (including geospatial and mapping references), and the Bank of Canada for currency and macro indicators.
To convert these signals into market drivers, we also reviewed company filings, investor presentations, procurement notices, reputable press, and association publications that describe adoption and use cases. In addition, we used paid subscriptions for company financials and news screening, patent lookups to spot feature direction (for example, indoor positioning and privacy controls), and shipment-level trade data where hardware linkages were relevant. The desk research sources listed here are illustrative only, and we relied on additional public and paid references for cross-checking and clarification.
Primary Interviews and Surveys
Primary interviews and surveys were used to validate what portion of location-related spending is actually recognized as LBS revenue in Canada, and how pricing changes as deployments move from pilots to scaled rollouts. We spoke with a mix of solution providers, channel partners, and enterprise and public-sector buyers across major provinces, then used follow-up questions to tighten inputs on usage intensity, renewal patterns, and indoor versus outdoor deployment shares.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 38% | CXOs: 13% |
| Mid tier: 46% | Functional/Unit leaders: 40% |
| Smaller Players: 16% | Managers: 47% |
Market-Sizing & Forecasting
Sizing starts with a top-down build that reconstructs the Canada demand pool using connected-device penetration, location feature usage in key apps, and enterprise adoption of tracking, navigation, and geofencing workflows. The model is then checked with selective bottom-up approximations, including sampled vendor revenue disclosures, channel feedback on typical contract values, and a simple ASP by active user or asset logic where it fits the use case.
Key inputs for this market include smartphone and mobile data adoption, 4G and 5G coverage progress, number of active fleet and logistics assets under tracking, the rollout pace of indoor positioning in large venues, and the effect of privacy and consent expectations on monetization. Because market direction depends on several moving variables at the same time, we used multivariate regression for the forecast and ran scenario checks that reflect interview-based views on adoption speed and pricing pressure. When bottom-up indicators were incomplete, we used conservative penetration bands and then re-tested them against observed renewal cycles and implementation timelines shared by respondents.
Data Validation & Update Cycle
Totals are validated through triangulation across independent signals, including macro spend capacity, connected-device indicators, and provider-side revenue direction, and then checked for outliers by segment and year. If a variance cannot be explained by a clear change in adoption, pricing, or definition, the assumption is flagged and reviewed again, and targeted re-contacts are made to resolve it.
Before sign-off, the model and its assumptions go through multi-step analyst review so that unit economics, growth rates, and implied penetration stay consistent with practical levels. Reports are refreshed annually, and interim updates are made when material events occur, such as policy changes, major platform shifts, or step-changes in rollout activity. Right before delivery, we do a final scan to incorporate the latest public releases and confirm that the numbers still reconcile.
麻豆视频's Canada Location Based Services Market Size Compared With Other Published Estimates
It is normal to see different market sizes for Canada location-based services because publishers do not always count the same revenue streams, and they often assume different adoption speeds and pricing curves. The spread usually comes from differences in adjacent software inclusion, how hardware is treated, and how far forecasts are extended from early-stage deployments.
Some published figures bundle broad location intelligence, digital mapping, and even parts of general geospatial analytics into one bucket, which lifts the total even if those revenues are not tied to active location service delivery. In contrast, 麻豆视频 counts LBS revenue only when the product or service is directly triggered by a location signal and is sold as a location-enabled capability, and adjacent data-only geospatial tools are kept out unless they are packaged and billed as LBS.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 1.35 B (2025) | |
| Global Consultancy A | USD 1.90 B (2025) | Uses a wider location intelligence scope that can include standalone geospatial analytics and broader mapping software, and it applies a higher attach rate to enterprise digital transformation budgets. |
| Industry Portal B | USD 1.10 B (2025) | Relies on a narrower view that leans on consumer app monetization and excludes several enterprise and public-sector use cases, and it keeps ASP growth nearly flat even as indoor deployments expand. |
The table shows that scope and monetization assumptions explain most of the difference, more than any single data point. By keeping revenue tied to verified location-triggered delivery and by stress-testing penetration and ASPs against buyer renewal behavior, the estimate stays transparent and repeatable for planning use.


Key Questions Answered in the Report
What is the current value of Canada’s location-based services market?
The location-based services market size in Canada is USD 1.56 billion in 2026, with a forecast to more than double to USD 3.26 billion by 2031.
Which segment grows the fastest within the Canadian market?
Indoor positioning registers the highest growth, advancing at a 11.62% CAGR as hospitals, malls, and airports adopt BLE, UWB, and sensor-fusion solutions.
How does Indigenous data sovereignty influence solution design?
OCAP principles require vendors to secure community consent for geodata collection and storage, leading to privacy-by-design architectures and localized cloud deployments.
Why are services more dominant than hardware sales?
Service contracts shield buyers from chip shortages and large upfront 5G infrastructure outlays, making recurring integration and analytics offerings more attractive.
What regulation poses the greatest near-term risk?
The combination of PIPEDA and the stalled Bill C-27 creates uncertainty and adds compliance costs, curbing aggressive data-monetization models.
Which end-user industry is expected to outpace others by 2031?
Healthcare is projected to grow at a 12.08% CAGR, driven by remote patient monitoring and hospital asset-tracking deployments across multiple provinces.
Page last updated on:



