
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 160.53 Billion |
| Market Size (2026) | USD 169.23 Billion |
| Market Size (2031) | USD 220.17 Billion |
| Growth Rate (2026 - 2031) | 5.42 % |
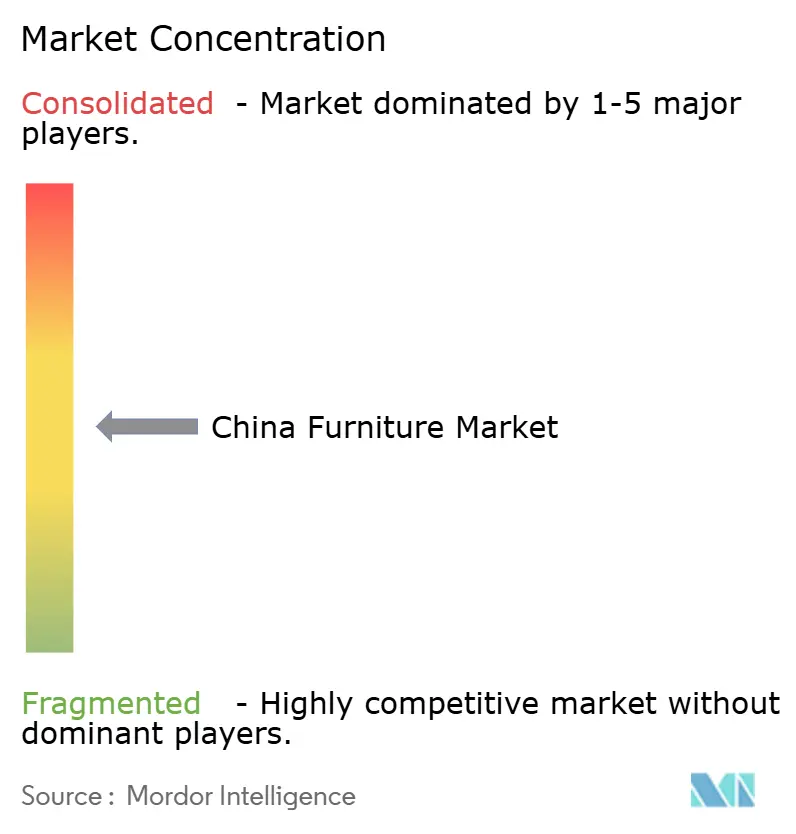
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
China Furniture Market Analysis by 麻豆视频
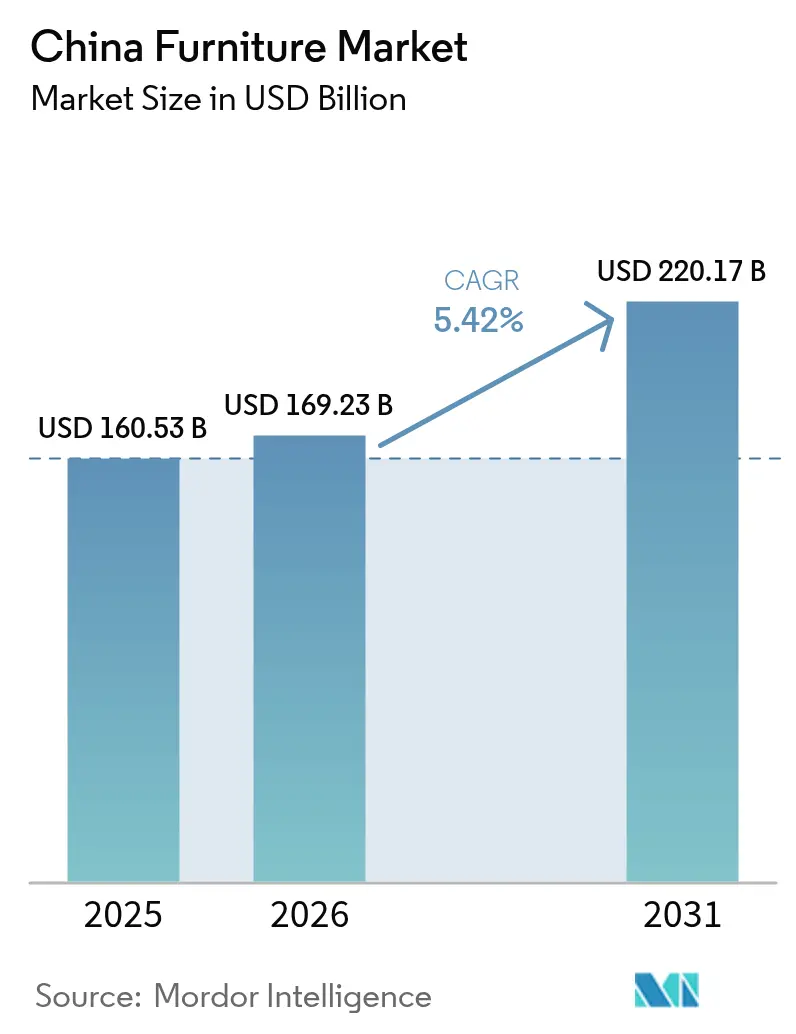
The China furniture market size was valued at USD 160.53 billion in 2025 and estimated to grow from USD 169.23 billion in 2026 to reach USD 220.17 billion by 2031, at a CAGR of 5.42% during the forecast period (2026-2031). Population migration toward lower-tier cities, sustained gains in disposable income, and the rapid adoption of omnichannel retail are steering revenue gains across the China furniture market. Demand patterns remain regionally unbalanced: eastern coastal provinces still account for the largest revenue pool, yet tier-2 and tier-3 urban clusters are generating the fastest incremental sales as housing completions and commercial fit-outs accelerate. Home furniture continues to dominate spending, while office furniture benefits from a renovation wave led by hybrid-work design mandates. On the supply side, export-oriented manufacturers are redirecting capacity to the domestic arena, increasing price competition, and speeding up product innovation. Government trade-in subsidies and a sharp rebound in domestic tourism are cushioning the negative impact of the property slowdown, keeping the China furniture market on a resilient growth trajectory through 2030 [1]International Monetary Fund, “People’s Republic of China: Staff Report for the 2025 Article IV Consultation,” imf.org.
Key Report Takeaways
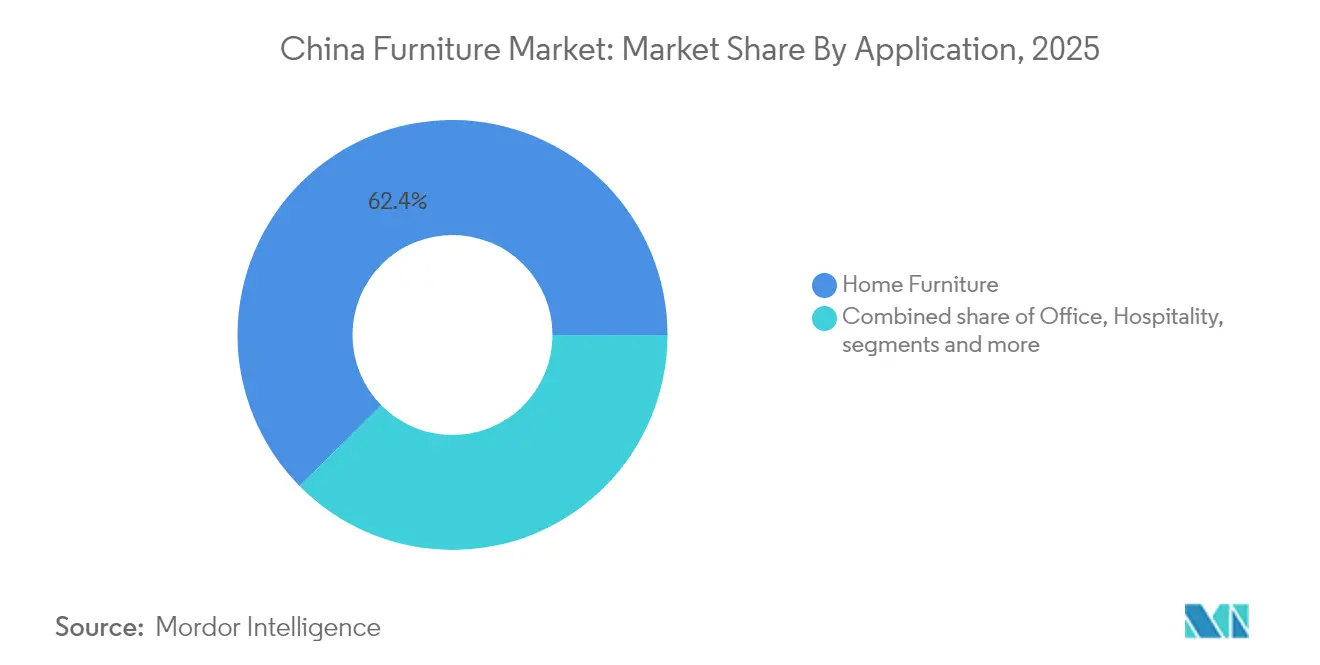
- By application, home furniture led with 62.40% of the China furniture market share in 2025, while office furniture is projected to post the highest 6.01% CAGR through 2031.
- By material, wood retained 56.60% revenue share of the China furniture market in 2025; polymers and plastics are set to expand at a 5.07% CAGR to 2031.
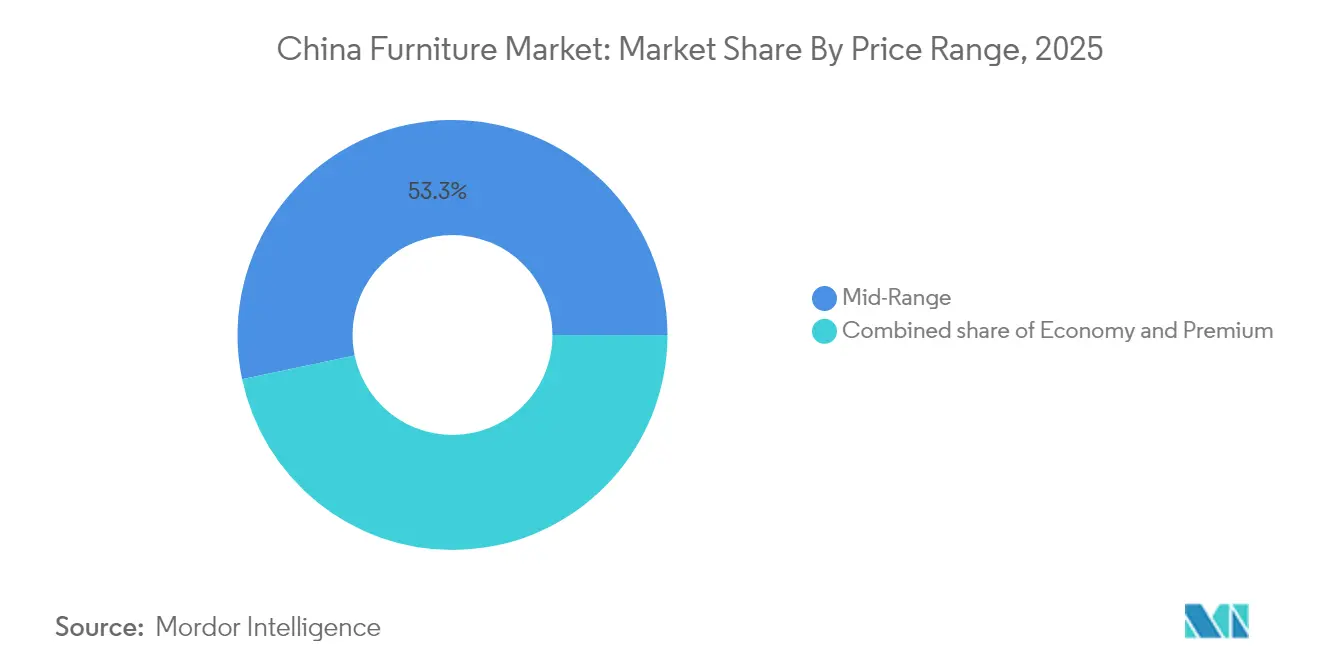
- By price range, mid-range products commanded 53.30% of the China furniture market size in 2025; the premium tier is forecast to grow at 6.18% CAGR between 2026-2031.
- By distribution channel, the B2C/retail segment captured 74.20% revenue share of the China furniture market in 2025, with the same channel advancing at a 5.69% CAGR through 2031.
- By geography, eastern China maintained the largest 37.60% revenue share of the China furniture market in 2025, whereas southwest China is expected to grow at 6.02% CAGR by 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
China Furniture Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid urbanization in tier-2 & 3 cities | +1.2% | Nationwide; strongest in Chengdu, Hangzhou, Wuhan | Medium term (2–4 years) |
| Rise of e-commerce and omnichannel retail | +0.9% | Highest penetration in eastern China | Short term (≤ 2 years) |
| Expansion of commercial & hospitality projects | +0.7% | Tourism hubs and coastal metros | Medium term (2–4 years) |
| Office renovation cycle in metropolitan hubs | +0.6% | Beijing, Shanghai, Guangzhou, Shenzhen | Short term (≤ 2 years) |
| Export manufacturers pivoting to domestic demand | +0.4% | Guangdong, Zhejiang, Jiangsu | Medium term (2–4 years) |
| Source: 麻豆视频 | |||
Rapid Urbanization in Tier-2 & Tier-3 Cities
Urban residency climbed to 66.2% in 2024, a 0.9-point rise year on year. Chengdu and Wuhan together added 2 million new residents during the year [2]National Bureau of Statistics of China, “2024 National Economic and Social Development Statistical Bulletin,” stats.gov.cn. Government-backed city cluster programs continue to channel infrastructure capital toward inland urban centers, spurring new-home deliveries and stimulating furniture purchases. Local buyers in Chengdu, Wuhan and other growth hubs exhibit a stronger preference for design-oriented yet functional pieces, prompting suppliers to extend showrooms and last-mile distribution networks beyond the traditional coastal corridor. Manufacturers that diversify product lines for smaller living spaces find higher attachment rates for modular units and storage-optimized layouts, reinforcing volume gains across the China furniture market.
Rise of E-Commerce and Omnichannel Retail
The Ministry of Commerce tallied CNY 1.02 trillion in 2024 online sales of home-related goods—including furniture—up 15.4% year on year [3]National Bureau of Statistics of China, “2024 National Economic and Social Development Statistical Bulletin,” stats.gov.cn. Digitally led discovery journeys now dominate early-stage furniture research, and blended “click-to-brick” pathways are compressing the buying cycle. Leading platforms deploy augmented-reality visualization, boosting conversion and compressing return rates. Large store networks provide smaller urban showrooms, pick-up lockers, and same-day fulfilment to retain customer loyalty. These shifts lower geographic barriers, broadening the furniture market in China and intensifying competitive pressures on product design and logistics agility.
Expansion of Commercial and Hospitality Projects
Domestic tourism recovered to near-pre-pandemic trip volumes in 2024, driving record room openings by national hotel chains. Shorter three-to-five-year replacement schedules for hospitality furniture compared with residential cycles sustain a reliable demand stream for customized case goods, lobby seating, and outdoor fixtures. Suppliers that couple design-build services with flexible manufacturing capacity capture a disproportionate share of high-margin projects across the China furniture market.
Export Manufacturers Pivoting to Domestic Demand
Heightened tariffs in key overseas markets have redirected capacity back home. Plants in Guangdong and Zhejiang fine-tune product aesthetics for local tastes, leveraging mature supply chains to compress lead times. This domestically focused output introduces more globally inspired styles at competitive ticket prices, intensifying margin pressure but enriching the variety and depth of the China furniture market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Property-sector slowdown | -1.3% | Most acute in tier-1 cities | Medium term (2–4 years) |
| Fragmented retail footprint & high rents | -0.7% | Tier-1 and tier-2 cities | Short term (≤ 2 years) |
| Timber import restrictions elevating costs | -0.5% | Guangdong, Zhejiang, Jiangsu | Medium term (2–4 years) |
| Source: 麻豆视频 | |||
Property-Sector Slowdown Curtailing New Residential Spending
Persistently weak residential starts in premium urban cores undermine demand for complete home furnishing packages. Consumers delay big-ticket purchases, raising promotional intensity across the China furniture market. Still, renovation spending partially offsets the decline as owners retrofit existing apartments, shifting product mix toward multifunctional and space-saving solutions.
Fragmented Retail Footprint & High Mall Rents Compressing Margins
Traditional chains face rent escalations that outpace same-store growth, especially in high-traffic malls. Many operators are moving to hub-and-spoke formats that combine flagship galleries with compact satellite units closer to residential districts. The resulting logistics complexity raises operating costs, pushing smaller dealers toward mergers or strategic alliances to remain viable within the furniture market in China.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Application: Home Leadership and Office Momentum
Home furniture accounted for 62.40% of the China furniture market size in 2025 and continues to benefit from cultural emphasis on domestic comfort and aesthetics. Demand growth, however, is shifting toward upgradable modular units that fit compact apartments in dense cities. Beds and sofas remain volume anchors, yet kitchen cabinets and storage systems register faster growth as households optimize existing space amid slower property turnover.
Office furniture, gaining from a 6.01% CAGR outlook, is propelled by post-pandemic layout realignments, with smart desks, collaborative pods, and ergonomic seating securing order books. This evolution narrows the historical gap between residential and commercial categories, adding diversity to revenue streams across the China furniture market.


By Material: Wood Primacy and Plastic & Polymer Upswing
Wood held 56.60% of the China furniture market share in 2025, supported by consumer perceptions of durability and premium feel. Supply chain tension is prompting heavier use of certified plantations and mixed-wood veneers to stabilize costs.
Simultaneously, Plastic & Polymer posts the swiftest 5.07% CAGR as innovations enhance scratch resistance, color depth, and recyclability. Hybrid constructions that combine wooden frames with polymer accents create new mid-price offerings, extending appeal across broad consumer cohorts in the China furniture market.
By Price Range: Mid-Range Core, Premium Acceleration
Mid-range lines generated 53.30% of the China furniture market size in 2025, balancing design aspirations with value.
The premium tier’s 6.18% CAGR is anchored in affluent households in Beijing, Shanghai and Shenzhen that seek differentiated styling and brand pedigree. Domestic labels partner with European designers to up-level catalogs, while smart-home integration strengthens perceived value. Economy lines defend share in inland cities, though rising wages and raw-material costs compress margins, pushing makers to automation and leaner distribution in the China furniture market.
By Distribution Channel: B2C Dominance and Digital Integration
The B2C route captured 74.20% revenue share in 2025, due to specialist chains, home centers, and direct-to-consumer brands. Digital traffic influences over two-thirds of purchase journeys, and retailers embed augmented-reality visualization plus same-day pick-up to merge online discovery with showroom assurance.
Project-based B2B sales contribute the remaining quarter, buoyed by hotel, office, and institutional remodeling. Logistics and after-sales service excellence remain decisive factors in protecting loyalty across the furniture market in China.
Geography Analysis
East China maintained the largest 37.60% revenue share of the China furniture market in 2025. East provinces—Guangdong, Zhejiang, Jiangsu—retain the lion’s share of consumption and production within the China furniture market, underpinned by dense retail networks, export-ready factories, and higher household incomes. Tier-1 cities feature elevated premium demand, yet slower population inflows temper growth relative to smaller urban clusters.
Central and western regions are emerging flashpoints for expansion as government infrastructure outlays lower logistics barriers. Urban clusters such as Chengdu-Chongqing record double-digit furniture revenue growth, fueled by rising home ownership and tourism-related hospitality projects. Manufacturers are allocating fresh capacity inland to capture labor cost savings, bolstering regional self-sufficiency in the China furniture market.
Distinct aesthetic preferences persist darker solid-wood motifs dominating northern styles, whereas southern consumers gravitate toward lighter hues and contemporary silhouettes. Retailers adjust assortments by city, supported by analytics that map demographic trends to design cues, enriching localization throughout the China furniture market.
Value Chain Analysis
The value chain starts with raw materials and components (timber and engineered boards, metals, polymers, foams, fabrics, coatings, hardware, and mechanisms such as motion motors). It then moves through panel processing, CNC cutting, upholstery, finishing, and final assembly across major manufacturing clusters. Production is concentrated in established hubs, including Foshan for upholstered furniture, Haining for fabrics, and Chengdu for solid-wood products, which supply both standardized SKUs and customized whole-home packages.
On the downstream side, the go-to-market split runs between B2C retail (specialty chains, home centers, and online-to-offline formats) and B2B or project channels covering offices, hospitality, and public-sector fit-outs. In project sales, design, measurement, delivery, and installation services are bundled. Margin pressure has also pushed leading manufacturers toward higher automation and intelligent manufacturing, while indoor-used board and finish compliance (including lower-emission specifications) and lead times often cited at roughly 15-25 days in key clusters raise the importance of supplier qualification, inventory planning, and last-mile delivery capacity for scale.
Competitive Landscape
Competitive Landscape
Kuka Home, Suofeiya Home Collection, and Oppein Home Group exploit vertically integrated supply chains to compress production cycles and defend shelf space. IKEA continues to localize product dimensions and color schemes to suit Chinese apartments, retaining loyalty despite mounting local competition.
Strategic investment cycles emphasize plant automation, digital twins, and in-house logistics to counter wage inflation. Export specialists, pressed by tariffs abroad, accelerate domestic brand launches featuring globally inspired aesthetics at competitive prices, crowding mid-tier shelves across the China furniture market.
Digitally native challengers bypass legacy wholesale, leveraging data-driven configurators and regional micro-factories for three-week delivery of made-to-order pieces. Traditional players respond with omnichannel financing, white-glove assembly, and extended warranties, underscoring service as a key point of differentiation in the China furniture market.
China Furniture Industry Leaders
-
Kuka Home
-
Suofeiya Home Collection
-
Oppein Home Group
-
Red Star Macalline Group
-
IKEA
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Green-compliant materials and low-emission indoor products create identifiable gaps in wood-based and hybrid furniture lines as mandatory national requirements tighten around indoor-used artificial board emissions. With the rollout of GB 18580-2025 (E0 level, formaldehyde emission limit of <=0.050 mg/m3), demand shifts toward certified boards, compliant coatings and adhesives, and traceable sourcing, encouraging manufacturers and retailers to upgrade assortments and use compliance as a premiumization lever in mid-range and premium categories.
Digitalization and whole-home customization also stand out as opportunity areas linked to omnichannel conversion and faster design-to-delivery cycles. Oppein Home Group’s move to roll out an upgraded proprietary AI design tool suite that links sales, design, and production workflows shows ongoing investment in workflow automation for customized furnishings, which supports shorter lead times and better order accuracy for renovation-led demand. Channel partnerships add another lever for scaling, including Suofeiya and Red Star Macalline Group coordinating store network expansion programs inside major mall ecosystems to extend reach beyond coastal cores into tier-2 and tier-3 city clusters.
Recent Industry Developments
- July 2026: IKEA announced the upcoming August 2026 global launch of KOMPISHANG, a collection positioned around mobile urban living. The announcement refreshes its mass-market assortment with space-efficient concepts aimed at smaller apartments and rental mobility in large Chinese cities.
- June 2026: Oppein Home Group launched an upgraded proprietary AI design tool suite integrating sales, design, and production workflows for customized home furnishings. The update strengthens whole-home customization throughput and improves coordination between front-end design and factory execution in a renovation-led demand environment.
- April 2026: Suofeiya Home Collection and Red Star Macalline Group launched the Star Chain Plan to accelerate store layout and recruitment across Red Star Macalline malls. By pairing a customization brand with a major offline mall operator, the initiative focuses on faster channel coverage and more consistent conversion for big-ticket furnishing packages.


Research Methodology Framework and Report Scope
Market Definition and Coverage
The China furniture market is defined as the value of new furniture units sold within mainland China across residential and non-residential uses, captured in USD and counted when a finished unit is placed on the market through any sales channel.
Scope exclusions: Excludes permanently fixed interior fit-outs, built-in cabinetry that is not sold as a unit, and outdoor rental furniture services.
Segmentation Overview
-
By Application
-
Home Furniture
- Chairs
- Tables (side tables, coffee tables, dressing tables, etc.)
- Beds
- Wardrobes
- Sofas
- Dining Tables/Dining Sets
- Kitchen Cabinets
- Other Home Furniture (bathroom furniture, outdoor furniture, etc.)
-
Office Furniture
- Chairs
- Tables
- Storage Cabinets
- Desks
- Sofas and Other Soft Seating
- Other Office Furniture
- Hospitality Furniture
- Educational Furniture
- Healthcare Furniture
- Other Applications (public places, retail malls, government offices, etc.)
-
Home Furniture
-
By Material
- Wood
- Metal
- Plastic & Polymer
- Other Materials
-
By Price Range
- Economy
- Mid-Range
- Premium
-
By Distribution Channel
-
B2C/Retail
- Home Centers
- Specialty Furniture Stores
- Online
- Other Distribution Channels
- B2B /Project
-
B2C/Retail
-
By Geography
- East China
- South-Central China
- North China
- Southwest China
- Others
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts by mapping the demand pool and trade flows that explain why furniture spending moves year to year in China. We use public data such as the National Bureau of Statistics of China releases, China Customs import and export statistics, UN Comtrade, and ITC Trade Map, which help us understand category direction and price and volume signals.
To keep the sizing grounded, we also review sources such as industry association updates, listed company annual reports and investor presentations, and reputable business press coverage for capacity additions, retail trends, and margin changes. Where available, patent databases are checked to understand product feature shifts that can affect pricing and replacement cycles. A paid subscription focused on shipment-level import and export records is used selectively to validate the mix and unit values for key furniture categories. These are illustrative sources only, and many other public references were used for data collection, cross-checking, and clarification.
Primary Interviews and Surveys
Primary work is used to confirm what desk sources cannot fully show, especially channel mix, pricing movement, and how residential and contract demand is behaving in different city tiers. We speak with participants across manufacturing, distribution, and large-buying institutions to validate assumptions, and we also test draft numbers with experts familiar with eastern, central, and western China so regional differences are not missed.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 37% | CXOs: 18% |
| Mid tier: 44% | Functional/Unit leaders: 22% |
| Smaller Players: 19% | Managers: 60% |
Market-Sizing & Forecasting
For market sizing, the core build uses a top-down approach where national furniture sales value is reconstructed using domestic production signals, import and export balances, and spending indicators that point to replacement and new demand. The total is then stress-tested through selective bottom-up checks, where sampled average selling prices are multiplied by indicative volumes for a few high-traded categories and compared with channel checks.
Key inputs used in the model include housing completions and renovation activity, commercial real estate fit-out cycles, import and export unit values for furniture categories, raw material cost direction that often influences pricing (wood panels, metals, polymers), and channel shifts between offline retail and e-commerce. Where a bottom-up view has gaps, we keep the estimates conservative by using ranges from interviews and by aligning the residual with trade and production consistency.
Forecasting is done using scenario analysis supported by multivariate regression, where demand drivers like housing and renovation, office and hospitality activity, and real price movement are varied within realistic bounds. The final trajectory is adjusted only after interview feedback confirms whether assumptions on price progression and category mix are still practical for the next few years.
Data Validation & Update Cycle
Validation is done by triangulating the modeled totals against independent signals, such as furniture trade balances, manufacturing output direction, and reported pricing trends, and then checking for year-to-year jumps that do not match the broader demand story. When a variance is seen, we re-check the input series, review currency conversion timing, and re-contact select interviewees if the change looks structural.
Before sign-off, the work is reviewed in multiple steps so key assumptions and calculations are re-tested by another analyst. The report is refreshed annually, and interim updates are made if material events occur that can move demand or pricing. Before delivery, a final pass is done to ensure clients receive the most current view available.
麻豆视频's China Furniture Market Size Compared With Other Published Estimates
Published market values for China furniture can differ even when they sound like they cover the same topic, because the counted products, pricing basis, and even the point of sale in the value chain are not always aligned. Differences also come from the year used, the currency conversion timing, and whether estimates are refreshed when trade and housing signals change.
The largest gaps typically come from whether the estimate counts furniture at manufacturer gate prices versus retail value, whether built-in fixtures and interior fit-outs are included, and how imports and exports are treated in the consumption math. Some sources also present a single consumption figure without showing the checks used to keep trade values, production direction, and average prices consistent across categories.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 169.23 B (2026) | |
| Industry Publisher A | USD 176.97 B (2024) | Uses a different base year and does not clearly state whether values are at retail or manufacturer level, which can lift totals if retail markups and taxes are implicitly included. |
| Trade Research House B | USD 101.00 B (2025) | Often reflects a consumption view tied closely to production and trade accounting, which can understate the market if contract furniture and channel pricing effects are not fully captured in the spending layer. |
Taken together, the spread is mainly explained by price-point selection and what is treated as furniture units versus fixed interior work, which keeps the sizing steps traceable when using manufacturer gate pricing and excluding permanent fit-outs, a choice applied by 麻豆视频.


Key Questions Answered in the Report
What is the current size of the China furniture market?
The China furniture market size is USD 169.23 billion in 2026, with a projected value of USD 220.17 billion by 2031.
Which application segment is expanding fastest?
Office furniture shows the highest growth, tracking a 6.01% CAGR for 2026-2031 due to renovation cycles and hybrid-work layouts.
How important is e-commerce to furniture sales in China?
Online discovery now drives most purchase journeys, and omnichannel strategies integrating showrooms with digital visualization tools are critical for growth.
What materials are gaining popularity beyond wood?
Engineered polymers and composite materials are registering the quickest gains as manufacturers seek cost stability and sustainability advantages.
How are global trade policies influencing the China furniture market?
Higher tariffs abroad have pushed export-oriented factories to focus on domestic consumers, intensifying competition and enriching product diversity.
Which regions inside China promise the highest growth potential?
Central and western urban clusters such as Chengdu-Chongqing are expanding rapidly, supported by infrastructure investment and rising home ownership.
Page last updated on:



