
Consumer Electronics Retail Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 1.08 Trillion |
| Market Size (2031) | USD 1.24 Trillion |
| Growth Rate (2026 - 2031) | 2.74 % |
| Fastest Growing Market | Middle East and Africa |
| Largest Market | Asia Pacific |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Consumer Electronics Retail Market Analysis by 麻豆视频
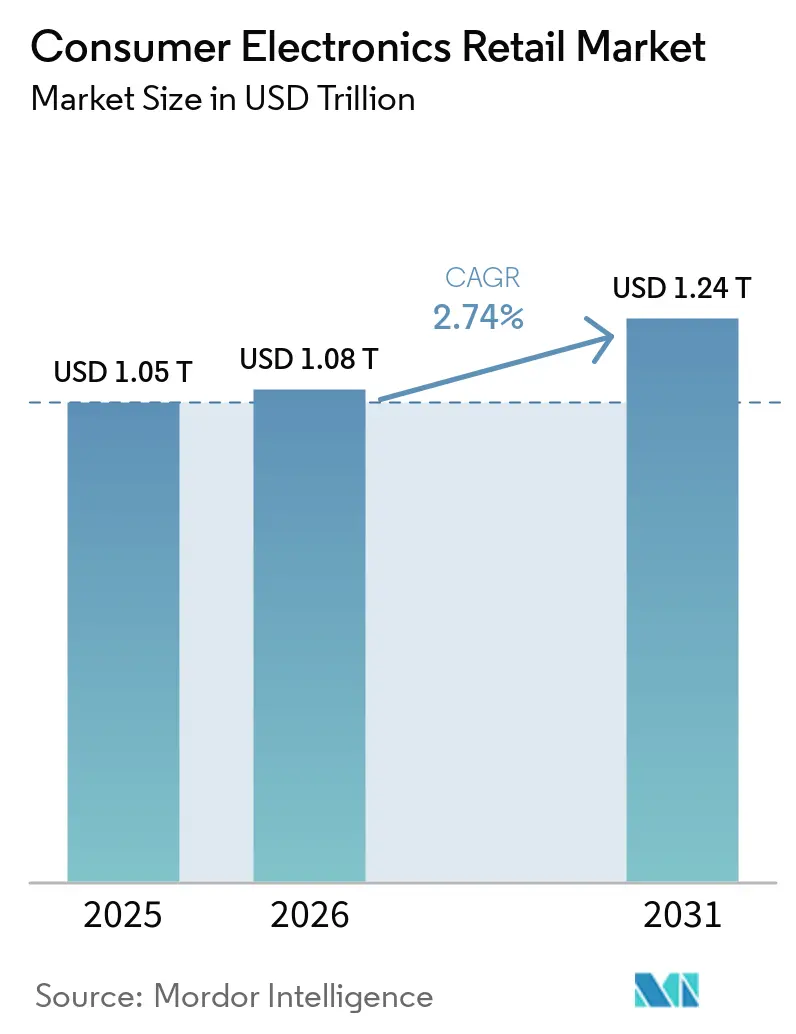
Consumer Electronics Retail market size in 2026 is estimated at USD 1.08 trillion, growing from 2025 value of USD 1.05 trillion with 2031 projections showing USD 1.24 trillion, growing at 2.74% CAGR over 2026-2031. The measured CAGR masks a substantial channel realignment as direct-to-consumer storefronts, bundled smart-home ecosystems, and buy-now-pay-later (BNPL) financing schemes change where and how shoppers spend. At the same time, 5G upgrade cycles, experiential retail formats, and refurbished-device trade-in programs expand purchase occasions even as inflation limits discretionary budgets. Competitive intensity remains moderate: the top five retailers control just under 40% of worldwide sales, leaving meaningful white-space for region-focused specialists. Regionally, Asia-Pacific holds the largest share, yet Middle East & Africa is growing the fastest, proving that localized service, language support, and payment options remain critical to scale in emerging geographies. Inventory planning, meanwhile, stays vulnerable to chip supply swings, prompting retailers to deploy AI-based demand forecasts and multi-sourcing contracts to maintain shelf availability.
Key Report Takeaways
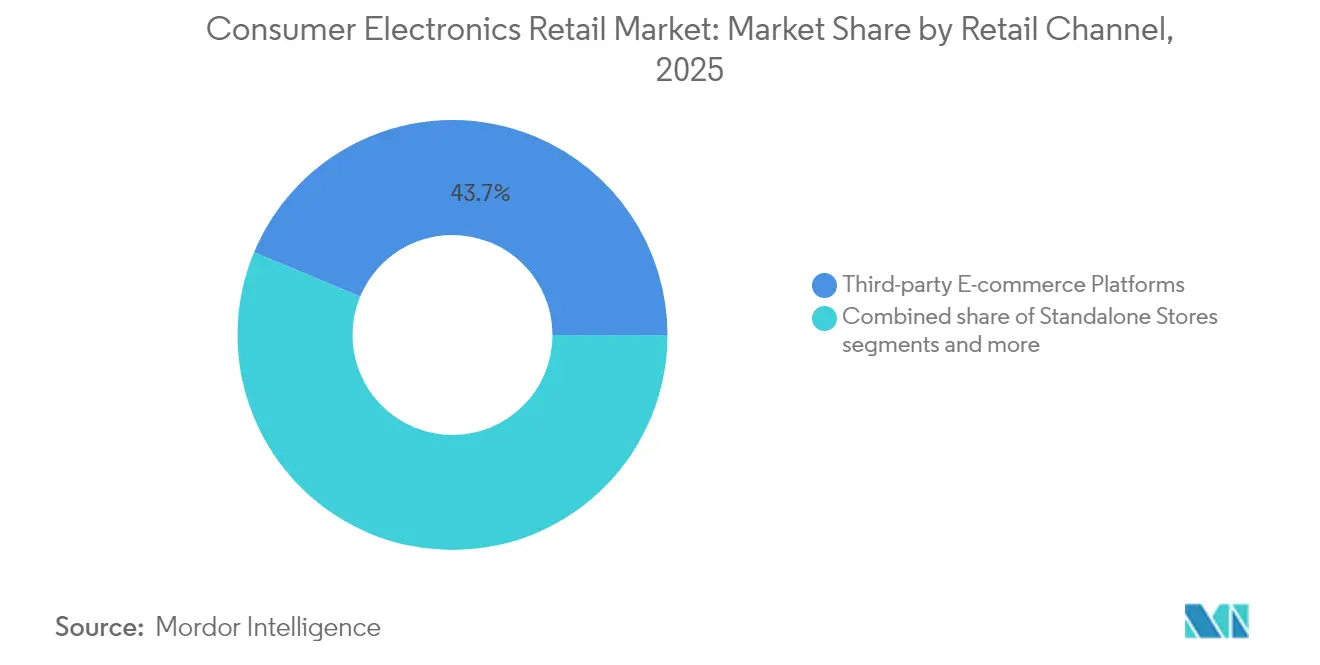
- By retail channel, third-party e-commerce platforms captured 43.72% of the Consumer Electronics Retail market share in 2025; brand-owned websites are projected to expand at a 9.92% CAGR to 2031.
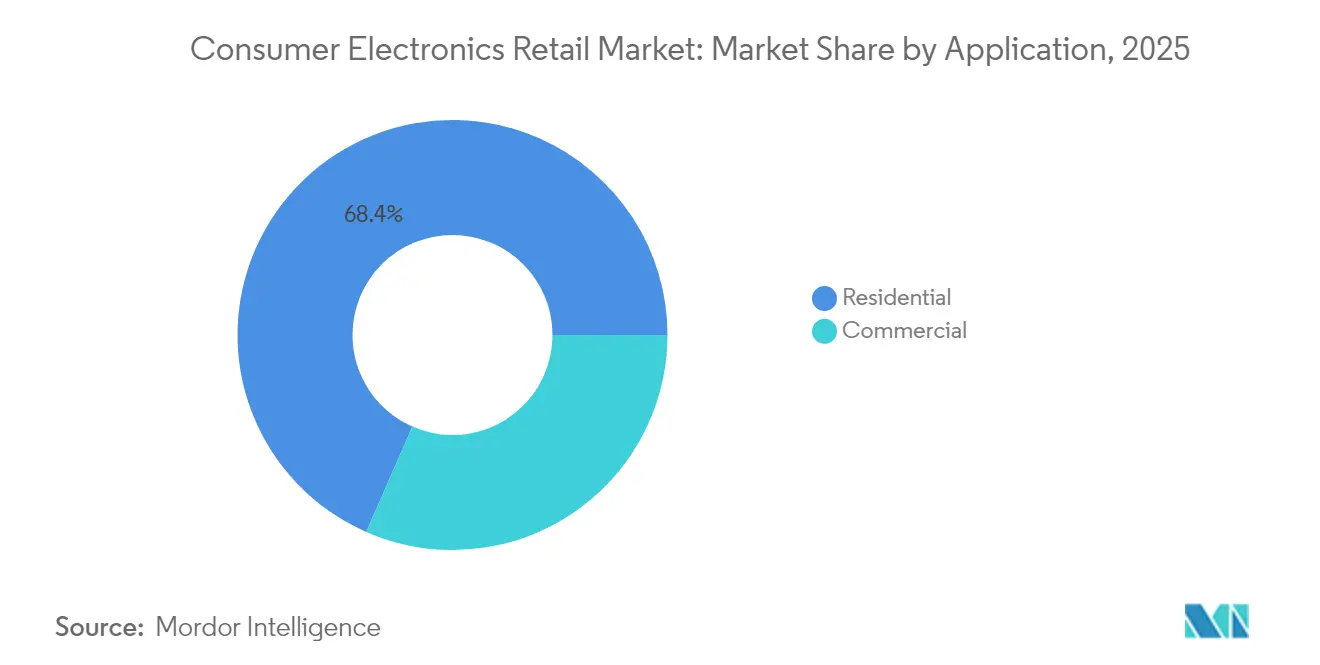
- By application, residential accounted for a 68.43% share of the Consumer Electronics Retail market size in 2025, while commercial is advancing at an 7.98% CAGR through 2031.
- By distribution channel, offline outlets held 56.71% of the Consumer Electronics Retail market size in 2025; online channels record the highest projected CAGR at 9.31% through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Global Consumer Electronics Retail Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of direct-to-consumer (D2C) brand stores | +0.8% | Global, strongest in North America & APAC | Medium term (2-4 years) |
| Rising demand for smart home ecosystems | +0.7% | Global, led by North America & Europe | Long term (≥ 4 years) |
| Growth in "Buy Now, Pay Later" (BNPL) financing options | +0.6% | Global, highest penetration in North America & Europe | Short term (≤ 2 years) |
| Rapid 5G device replacement cycles | +0.5% | APAC core, spill-over to North America & Europe | Medium term (2-4 years) |
| Emergence of experiential retail formats (AR/VR demos) | +0.3% | North America & Europe, expanding to APAC | Long term (≥ 4 years) |
| Circular-economy trade-in & refurbished programs | +0.4% | Global, regulatory driven in Europe | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Expansion of Direct-to-Consumer Brand Stores
Manufacturers increasingly bypass traditional retail intermediaries to establish direct customer relationships, capturing higher margins while controlling brand experience across touchpoints. Xiaomi's expansion into Spain with dedicated Mi Stores in 2024 exemplifies this strategy, as the Chinese brand seeks to differentiate from commodity Android offerings through curated retail environments. This D2C pivot accelerates as brands recognize that traditional retailers often commoditize their products, limiting differentiation opportunities and margin capture. Best Buy's response includes strategic partnerships with brands like Ikea to create shop-in-shop experiences, acknowledging that pure-play electronics retailers must evolve beyond transactional relationships. The trend particularly benefits premium brands that can justify dedicated retail footprints, while mid-tier manufacturers explore pop-up formats and experiential showrooms to test market receptivity before committing to permanent locations.
Rising Demand for Smart Home Ecosystems
Interconnected device ecosystems drive multi-product purchasing behaviours, as consumers seek seamless integration across lighting, security, entertainment, and climate control systems. Samsung's SmartThings platform integration across appliances, mobile devices, and home automation products creates switching costs that lock customers into the ecosystem, generating recurring revenue through services and accessories[1]Samsung Electronics, “2024 Business Report,” samsung.com.. The Matter standard's adoption in 2024 reduces interoperability barriers, paradoxically intensifying competition as consumers gain confidence in cross-brand compatibility. LG's ThinQ platform demonstrates how traditional appliance manufacturers leverage connectivity to enter adjacent categories, with refrigerators becoming central hubs for grocery ordering and energy management. This ecosystem approach transforms one-time hardware sales into ongoing service relationships, fundamentally altering retailer value propositions from product-centric to solution-oriented offerings.
Growth in Buy Now, Pay Later Financing Options
BNPL services expand electronics affordability by fragmenting large purchases into manageable installments, particularly appealing to younger demographics with limited credit history. Affirm's partnership expansions with electronics retailers in 2024 demonstrate how BNPL providers target high-consideration categories where payment flexibility influences purchase decisions[2]Affirm Holdings, “2024 Investor Letter,” affirm.com.. Research indicates that 43% of Gen Z consumers prefer BNPL over traditional credit cards for electronics purchases, as these services avoid interest charges when payments are made on schedule. The trend particularly benefits retailers selling premium devices, as BNPL reduces psychological barriers to higher-priced items while maintaining cash flow through immediate payment from BNPL providers. However, regulatory scrutiny intensifies as consumer advocacy groups raise concerns about over-leveraging, potentially constraining future growth as compliance costs increase.
Rapid 5G Device Replacement Cycles
As 5G network coverage now reaches over 80% of the global population, users are accelerating the transition from 4G to 5G devices, upgrading their handsets far sooner than historical replacement cycles would suggest. This shift is being driven not only by faster network speeds but also by growing consumer demand for high-performance mobile experiences such as real-time gaming, HD streaming, and AI-driven applications, which place increasing strain on legacy 4G devices. According to forecasts by Ericsson, average monthly smartphone data consumption is expected to exceed 7 GB by 2025, placing further pressure on outdated hardware and encouraging users to adopt newer, 5G-enabled models[3]Ericsson AB, “Mobility Report 2024,” ericsson.com. . Retailers are capitalizing on this momentum by offering compelling trade-in incentives, such as elevated credit for old devices and seamless same-day data transfer services, effectively lowering upgrade barriers while enhancing customer convenience. These strategies not only boost new device sales but also create secondary revenue streams through the resale of refurbished units, contributing to circular economy initiatives.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Persistent global chip supply volatility | -0.9% | Global, most severe in APAC manufacturing hubs | Medium term (2-4 years) |
| Inflation-driven discretionary-spend pullback | -0.7% | Global, acute in Europe & South America | Short term (≤ 2 years) |
| Intensifying cross-border e-commerce price competition | -0.4% | Global, strongest impact in Europe & North America | Long term (≥ 4 years) |
| Growing regulatory scrutiny on e-waste compliance | -0.3% | Europe & North America, expanding to APAC | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Persistent Global Chip Supply Volatility
Semiconductor shortages continue disrupting electronics retailng inventory planning, as Hurricane Helene's impact on North Carolina's Spruce Pine quartz mining operations in 2024 highlighted critical supply chain vulnerabilities. This facility supplies approximately 70% of global high-purity quartz essential for semiconductor wafer production, demonstrating how geographically concentrated raw material sources create systemic risks. Artificial intelligence demands further strain on chip allocation, as data center processors command premium pricing and priority allocation over consumer electronics applications. Retailers respond by diversifying supplier relationships and implementing AI-driven demand forecasting to optimize inventory allocation across product categories. General Motors' deployment of AI-powered supply chain risk management systems exemplifies how major buyers proactively identify potential disruptions before they impact production schedules.
Inflation-driven Discretionary Spend Pullback
Persistent inflationary pressures constrain consumer electronics purchases as households prioritize essential goods over discretionary upgrades. Federal Reserve data indicate that consumer electronics spending declined 3.20% year-over-year in Q3 2024, as inflation-adjusted disposable income growth lagged price increases across multiple categories. This constraint particularly affects mid-tier products, as consumers either delay purchases or trade down to basic functionality devices, compressing retailer margins on volume-driven categories. Proposed tariff policies could exacerbate these pressures, with Peterson Institute estimates suggesting 25% tariffs on Chinese electronics could increase laptop prices by 45% and smartphone costs by 26%. Retailers adapt through expanded trade-in programs and financing partnerships, attempting to maintain transaction volumes despite affordability constraints.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Retail Channel: Third-Party Platforms Dominate, D2C Outpaces
Third-party e-commerce held 43.72% of the Consumer Electronics Retail market share in 2025, but brand-owned websites are projected to capture the highest 9.92% CAGR through 2031, reflecting brands’ appetite for direct data ownership. The Consumer Electronics Retail market size attributed to D2C sites is forecast to add more than USD 44.2 billion over the horizon, helping manufacturers offset wholesale margin erosion. Physical omni-channel chains respond with curbside pickup, same-day delivery, and subscription-based tech-support bundles to preserve traffic. D2C momentum does not spell extinction for marketplace giants; network effects still funnel small brands to Amazon for demand generation. Yet, escalating platform fees have triggered high-volume sellers to co-launch standalone sites supported by social-commerce traffic. Standalone mall stores face a shallower 3.22% CAGR as foot traffic migrates to mixed-use developments, but experiential anchors—VR gaming dens or smart-home mockups—can lift dwell time and attachment rates. Ultimately, channel coexistence evolves toward customer-journey orchestration: discovery may start on TikTok, comparison on a marketplace, and purchase at a brand app with in-store pickup.


By Application: Residential Retains Scale, Commercial Accelerates
Residential applications generated 68.43% of the Consumer Electronics Retail market size in 2025, underpinned by multi-device households and smart-home uptake. Nevertheless, the commercial segment is set to grow at 7.98% CAGR on the back of hybrid-work investments. Collaboration displays, conferencing bars, and security analytics servers headline procurement lists as enterprises retrofit spaces for flexible attendance. Commercial buyers operate on total-cost-of-ownership logic; thus, retailers extend managed-services contracts and financing to lock in three- to five-year refresh commitments, elevating lifetime value. Residential shoppers continue to prioritize ease and instant gratification; one-hour delivery windows on premium phones and consoles have proven to increase conversion by 17% for retailers offering the service. As macro conditions tighten, both segments gravitate toward trade-in rebates, establishing a circular inventory stream that lowers entry price and improves environmental credentials.
By Distribution Channel: Online Surges, Offline Reinvents
Online distribution channels surge at 9.31% CAGR through 2031, steadily gaining share against offline channels that maintain 56.71% market share in 2025 but grow at only 4.05% CAGR. This shift reflects permanent behavioural changes from pandemic-era shopping patterns, as consumers embrace digital research and purchase processes for electronics categories. Amazon's electronics segment growth demonstrates online platforms' advantages in selection breadth and price transparency, while traditional retailers invest heavily in omni-channel capabilities to remain competitive. Best Buy's successful "buy online, pick up in store" model illustrates how offline retailers can leverage physical assets to compete with pure-play digital platforms.
The channel evolution creates distinct competitive dynamics, with online platforms excelling in convenience and selection while offline stores provide hands-on product evaluation and immediate gratification. Experiential retail formats attempt to bridge this gap, using AR and VR demonstrations to replicate online information richness within physical environments. Walmart's electronics department redesign in 2024 exemplifies how traditional retailers integrate digital tools to enhance in-store experiences while maintaining their logistics and inventory advantages. Regulatory compliance factors increasingly influence channel strategies, as e-waste management requirements favor retailers with established reverse logistics capabilities for trade-in and recycling programs.
Geography Analysis
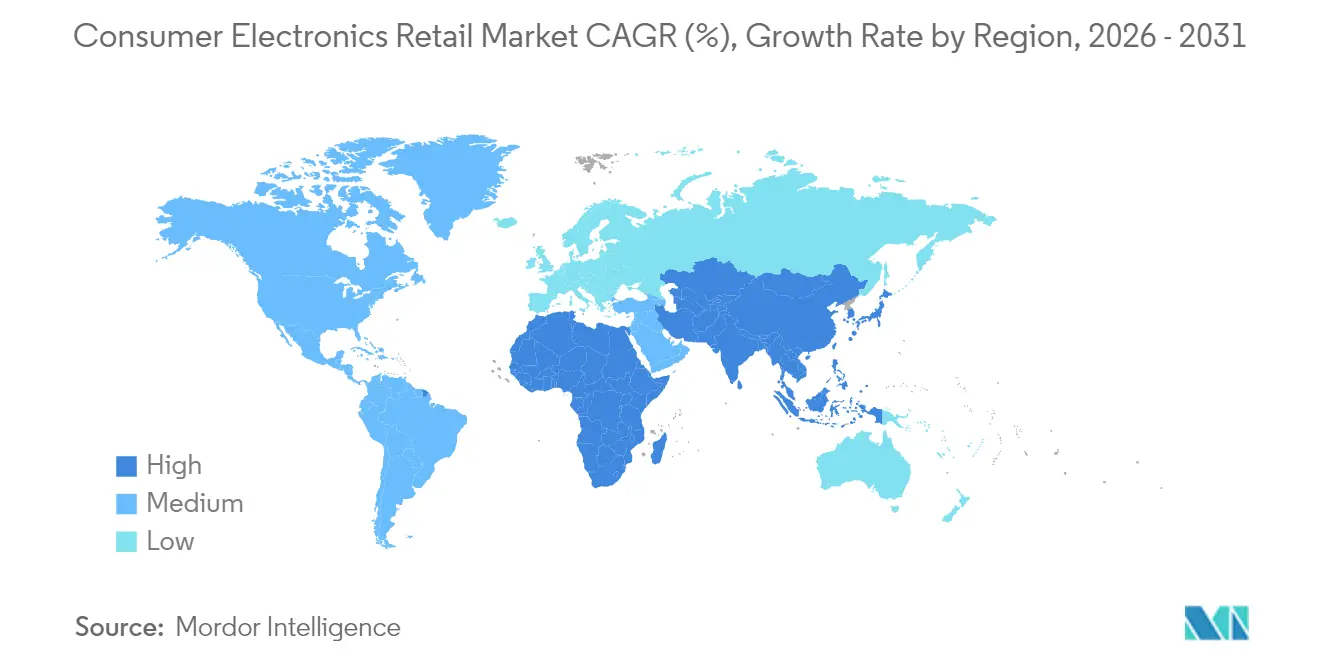
Asia-Pacific dominates the Consumer Electronics Retail market with a 36.05% share in 2025, leveraging manufacturing proximity, rising middle-class consumption, and rapid e-commerce adoption across key economies. China's "New Retail" integration of online and offline channels creates sophisticated omni-channel experiences that Western retailers are now emulating, while India's consumer durables sector grows at approximately 11% CAGR as EY projects the country to become the world's fourth-largest market by fiscal 2027. Indonesia's Electronic City invested USD 15 million in retail expansion during 2024, reflecting regional confidence in sustained demand growth despite global economic uncertainties. Southeast Asia's e-commerce momentum continues with Vietnam's market projected to reach USD 63 billion by 2030, driven by mobile-first shopping behaviours and improving logistics infrastructure.
Middle East & Africa emerges as the fastest-growing region at 7.61% CAGR through 2031, attracting significant foreign investment as retailers recognize untapped market potential. TJX Companies' USD 360 million acquisition of a 35% stake in the UAE's Brands for Less in 2024 signals major retailers' confidence in regional growth prospects, while Sharp's USD 30 million joint venture with Egypt's Elaraby Group for refrigerator manufacturing demonstrates how global brands establish local production to serve expanding markets. The region benefits from young demographics, increasing urbanization, and government digitization initiatives that drive electronics adoption across consumer and commercial segments.
North America and Europe face mature market dynamics with 4.14% and 3.47% CAGR, respectively, through 2031, as replacement cycles extend and consumers become more selective about upgrades. However, these regions lead in premium segment adoption and experiential retail innovation, with Best Buy's VR demonstration areas and Apple's expanded service offerings setting global standards for customer engagement. European markets particularly emphasize sustainability compliance, with WEEE (Waste Electrical and Electronic Equipment) directive requirements creating competitive advantages for retailers with established circular economy programs. South America's 4.93% CAGR reflects economic recovery and expanding middle-class access to consumer electronics, though currency volatility and import dependencies create ongoing challenges for consistent growth trajectories.

Regulatory Landscape
Consumer electronics retail operates under a layered compliance regime spanning product safety, energy use, chemicals, packaging, and end-of-life takeback obligations, with requirements varying by destination market (e.g., FCC in the United States, CE marking in the European Union, BIS in India, ANATEL in Brazil, IFT in Mexico, and KC in South Korea). In 2026, the EU General Product Safety Regulation (GPSR) expands consumer-protection expectations for products sold across channels, tightening obligations around traceability and information flows that online marketplaces and omnichannel retailers must operationalize at scale.
Sustainability-linked rules are also shifting from voluntary programs to enforceable obligations that affect assortment, packaging, and reverse logistics. Oregon's Extended Producer Responsibility (EPR) framework for batteries takes effect in April 2026, and the EU Packaging and Packaging Waste Regulation introduces new labeling and recycling requirements starting mid-2026. Separately, the U.S. Consumer Product Safety Commission requirement for eFiling of Certificates of Compliance with U.S. Customs and Border Protection becomes effective in July 2026, increasing the importance of automated compliance documentation for high-SKU electronics import flows.
Value Chain Analysis
The value chain starts with consumer-electronics OEMs and component ecosystems that shape availability, specifications, and upgrade timing, then moves through importers, distributors, and retailers that handle merchandising, financing, and service attach. Retailers increasingly lean on standards and interoperability bodies to reduce friction in multi-brand ecosystems and returns, including the Consumer Technology Association (CTA) standards program (over 150 active standards, updated in April 2026) and VESA display-interface standards such as DisplayPort and DisplayHDR supported by a broad membership base.
Downstream execution centers on assortment planning, fulfillment, last-mile delivery, and reverse logistics for trade-in, refurbishment, and recycling, where scale and data capabilities help differentiate leaders. Large retailers and marketplaces mix owned logistics with third-party partners to stabilize flow-through and manage disruptions. Walmart uses 3PL partners such as C.H. Robinson, Hub Group, and RJW Logistics within its consolidated network, while Amazon applies internal AI models (including Frida) for demand and assortment planning. Policy advocacy and regulatory monitoring run in parallel through sector bodies such as the Consumer Electronics Retailers Coalition (CERC) and the European Consumer Electronics Retail Council (EuCER), reflecting how product, packaging, and e-waste rules are increasingly shaping retail economics.
Competitive Landscape
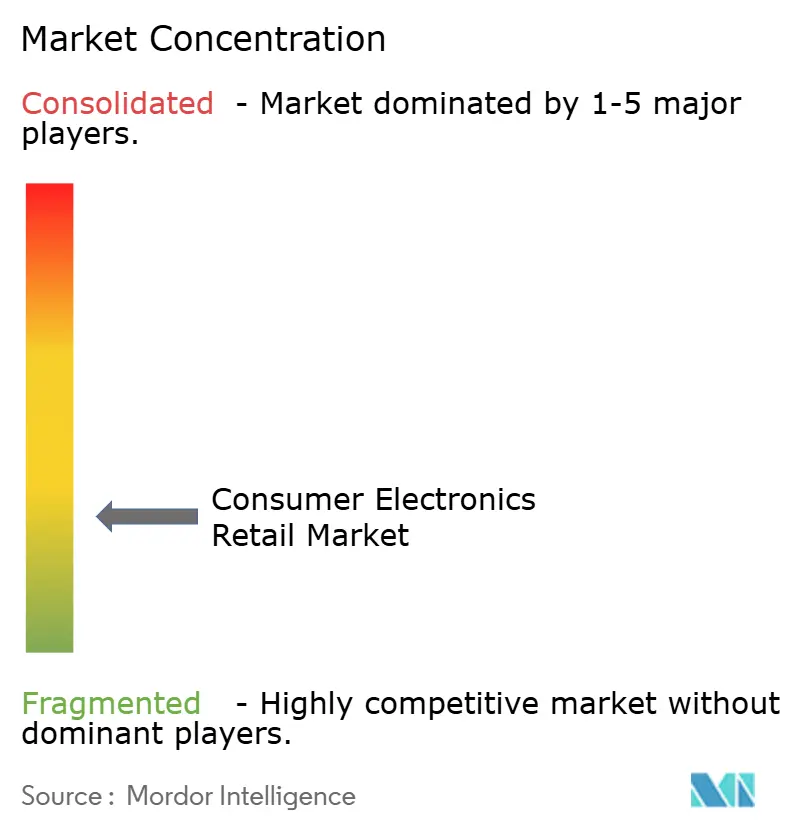
The Consumer Electronics Retail market shows moderate fragmentation, with the top five players collectively holding a notable portion of global market share. This structure leaves substantial room for specialized retailers and regional leaders to capture niche segments through tailored offerings and local market understanding. Amazon leads globally, benefiting from the scalability of its marketplace model and robust logistics infrastructure. Meanwhile, Walmart remains a strong contender, utilizing its extensive physical store network and supply chain capabilities to compete effectively in electronics. Competitive dynamics vary widely by region and sales channel, influenced by factors such as consumer behaviour, regulatory environments, and market maturity.
Strategic differentiation in the market is shifting away from purely transactional retail models toward experiential and service-oriented formats. As online platforms become increasingly dominant in product pricing and convenience, brick-and-mortar retailers are investing in added-value services to retain customer loyalty. Best Buy’s Geek Squad and Apple’s Genius Bar exemplify this shift, offering technical support and post-sale engagement that create switching costs and deepen brand relationships. These service layers help traditional retailers defend against both direct-to-consumer brands and international e-commerce players that bypass conventional distribution systems. In this landscape, building emotional and service-based loyalty is becoming just as important as offering competitive pricing.
Technological innovation continues to accelerate, with AI-powered personalization, chat-based customer support, and augmented reality product demos now expected rather than exceptional. As digital tools become standard across leading platforms, the focus is turning toward execution excellence and seamless integration of online and offline experiences. Growth opportunities are also emerging in underserved geographies and niche product segments where customer needs remain unmet by mass-market players. Additionally, increasing regulatory pressure on sustainability is driving demand for services like certified refurbishing, recycling, and trade-in programs areas that require strong operational capabilities and compliance expertise. Retailers that can navigate these complexities while maintaining customer trust are likely to gain long-term competitive advantages.
Consumer Electronics Retail Industry Leaders
Amazon.com, Inc
Walmart Inc.
Best Buy Co., Inc.
JD.com Inc.
MediaMarktSaturn Retail Group
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A near-term opportunity is supply-chain-enabled assortment expansion and faster availability, especially for retailers that can translate logistics investments into broader online selection and dependable delivery promises. Walmart has been applying AI and digital-twin approaches to test logistics scenarios, and as of February 2026, was retrofitting 23 of its 42 U.S. regional distribution centers with automation. In May 2026, Walmart launched its Prepaid Consolidation program to simplify inbound logistics by letting suppliers ship to a single point for national distribution, which supports electronics retailers in reducing inbound complexity, improving in-stock performance, and sustaining online growth without proportionally increasing store inventory.
Another opportunity is the platformization of fulfillment and marketplaces as competitive tools in consumer electronics retail, where selection breadth and delivery speed influence conversion. In May 2026, Amazon introduced Amazon Supply Chain Services, opening its freight, fulfillment, and delivery capabilities to third-party businesses. It has also pursued large-format physical retail concepts tied to robotic fulfillment (Project Kobe) that link store experience with automated back-end operations. Together, these moves raise delivery reliability and SKU breadth, while creating partnership and service layers for brands and smaller retailers that want access to higher-performing logistics and multichannel fulfillment without building comparable infrastructure.
Recent Industry Developments
- June 2026: Amazon entered a multiyear, multibillion-dollar agreement with Corning Incorporated to supply optical fiber, cable, and connectivity solutions to expand its data center infrastructure. The agreement expands Amazon's data center capacity with upgraded fiber and connectivity. It also creates 1,000 manufacturing jobs in North Carolina, strengthening the domestic supply chain.
- June 2026: Best Buy launched the national rollout of RGB LED TVs across its stores and digital channels. The rollout solidifies exclusive partnerships with Samsung, Sony, LG, TCL, and Hisense. The initiative strengthens Best Buy's display capabilities and consumer choice, supporting its hardware ecosystem strategy.
- April 2026: Walmart expanded its marketplace platform by introducing a dedicated Premium Electronics category to capture higher-margin tech and specialty inventory. The move enhances Walmarts electronics assortment on the marketplace. It strengthens competitive positioning against online-only players by targeting higher-margin products.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the value of consumer electronics sold to end customers by retailers through stores and online channels, where revenue is recognized at the point of retail sale and includes product-related retail income.
Scope exclusions: It excludes upstream manufacturing value, pure B2B distribution that does not touch retail checkout, and second-hand peer-to-peer sales that bypass retailers.
Segmentation Overview
- By Retail Channel
- Standalone Stores
- Shopping Malls
- Brand-owned Websites
- Third-party E-commerce Platforms
- Omni-Channel Retailers
- Other Retail Channels
- By Application
- Residential
- Commercial
- By Distribution Channel
- Offline
- Online
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South-East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk work was used to build the starting structure of the market and to keep our assumptions anchored to observable retail activity. We reviewed public government statistics for retail trade and consumer spending, along with trade and customs releases that help explain import-led supply swings for big categories.
We also referenced reputable sources such as U.S. Census Bureau retail trade series, Eurostat retail turnover data, UN Comtrade trade statistics, OECD household consumption indicators, and central bank inflation and exchange-rate data. To connect these macro series to retailer-level reality, we used annual reports and investor presentations, filings where available, and credible press coverage on store counts, omnichannel mix, and category trends. In a few spots, paid subscriptions were used for company financials, shipment-level import and export checks, and patent activity signals tied to device refresh cycles. These desk sources are illustrative and not exhaustive, and many other public and paid references were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on converting broad retail signals into usable assumptions on channel mix, category attachment, and pricing behavior during promotions and new-product launches. We spoke with retailer-side leaders, brand-facing sales roles, supply chain contacts, and category managers across major regions so gaps in public reporting could be filled and then cross-checked.
Inputs from these discussions were used to test what was learned from desk research, align on realistic demand drivers (like replacement cycles and financing uptake), and confirm that our final totals match what market participants see in their own operating plans.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 33% | CXOs: 15% | APAC: 49% |
| Mid tier: 46% | Functional/Unit leaders: 25% | EMEA: 30% |
| Smaller Players: 21% | Managers: 60% | Americas: 21% |
Market-Sizing & Forecasting
Sizing starts from a top-down reconstruction of the retail demand pool by linking electronics and appliance retail activity to consumer spending and retail trade output, which is then translated into category and channel splits using measured mix indicators. Only after those totals are built do we corroborate them with selective bottom-up approximations like sampled revenue roll-ups from disclosed retailer filings, store-count and productivity checks, and an ASP times volume sense-check for major device groups.
A few inputs that matter in this market include retail turnover for electronics and appliance outlets, e-commerce penetration in electronics, inflation-adjusted ticket size movement during promotional periods, currency conversion timing for reported revenues, and device replacement cadence for phones, PCs, TVs, and major appliances. Where data is thin for smaller countries or informal retail, gaps are handled by using proxy indicators like imports of finished goods, regional per-capita electronics spend, and retailer footprint signals, followed by primary checks to avoid overstating demand.
Forecasts are built using scenario analysis supported by simple multivariate relationships between disposable income trends, inflation, promotional intensity, and product refresh cycles, with assumptions reviewed with interviewees to keep the forward view realistic rather than optimistic or overly conservative.
Data Validation & Update Cycle
Outputs are validated through several rounds of checks so the totals behave like a real retail market. We compare modeled revenue movement against independent signals like retail trade growth, company-reported same-store sales direction, and trade flow shifts for key device categories, and then investigate any large variances before sign-off.
When an anomaly is found, the logic is re-run with refreshed inputs and, if needed, follow-up questions are sent back to selected interviewees to confirm whether the change is structural or temporary. Reports are refreshed annually, with interim updates triggered by material events such as major pricing shocks, demand slowdowns, or large channel shifts. Before delivery, an analyst performs a final pass so clients receive the latest updated view.
麻豆视频's Consumer Electronics Retailers Market Sizing Compared With Other Published Estimates
Published market values for consumer electronics retailers can look far apart because the definition of retail revenue is not handled the same way by every publisher, and the channel boundaries can shift quickly. Differences also come from timing, because fast-moving pricing and currency swings can change the same underlying sales volume into a different USD number.
The biggest gaps usually come from what is counted as a retailer sale versus a marketplace pass-through, how refurbished and open-box revenue is treated, and whether services like warranties and device financing fees are included inside the total. Another driver is the base case stance, where some figures lean into aggressive upgrade-cycle assumptions, while others smooth demand using slower replacement curves and fewer promotional spikes, and those choices can move the 2026 size meaningfully in either direction for 麻豆视频.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 1.08 T (2026) | |
| Global Consultancy A | USD 1.12 T (2025) | Uses an earlier base year and applies a higher assumed online growth path, and it appears to include marketplace GMV that can overstate true retailer-recognized revenue. |
| Industry Association B | USD 0.98 T (2026) | Tracks consumer technology sales using category shipments and retail-value proxies, which can undercount multi-category retailers and may exclude warranty and accessory attach revenue. |
Across the three figures, the spread is mainly explained by channel accounting choices and by whether the estimate starts from retail revenue recognition or from product-level sales proxies. By keeping variables like channel mix, pricing movement, and currency timing explicit, the result becomes easier to reconcile and to reuse for planning across regions and time periods.


Key Questions Answered in the Report
How large is the Consumer Electronics Retail market in 2026?
The Consumer Electronics Retailers Market size is expected to reach USD 1.08 trillion in 2026 and grow at a CAGR of 2.74% to reach USD 1.24 trillion by 2031.
Which retail channel is growing the fastest for electronics?
Brand-owned websites lead growth with a projected 9.92% CAGR through 2031, driven by manufacturers seeking direct customer engagement.
What region delivers the highest growth rate for electronics sales?
Middle East & Africa is expected to post a 7.61% CAGR, benefiting from young demographics and expanding digital infrastructure.
How are retailers addressing chip supply shortages?
Retailers deploy AI forecasting, diversify supplier bases, and secure pre-paid allocation contracts to stabilize product availability.
Why is BNPL important to electronics retail?
BNPL lifts conversion rates by fragmenting large-ticket payments into interest-free installments, making premium devices accessible to credit-averse shoppers
Page last updated on:



