
Cycle Tourism Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 160.97 Billion |
| Market Size (2031) | USD 251.43 Billion |
| Growth Rate (2026 - 2031) | 9.32 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | Europe |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Cycle Tourism Market Analysis by 麻豆视频
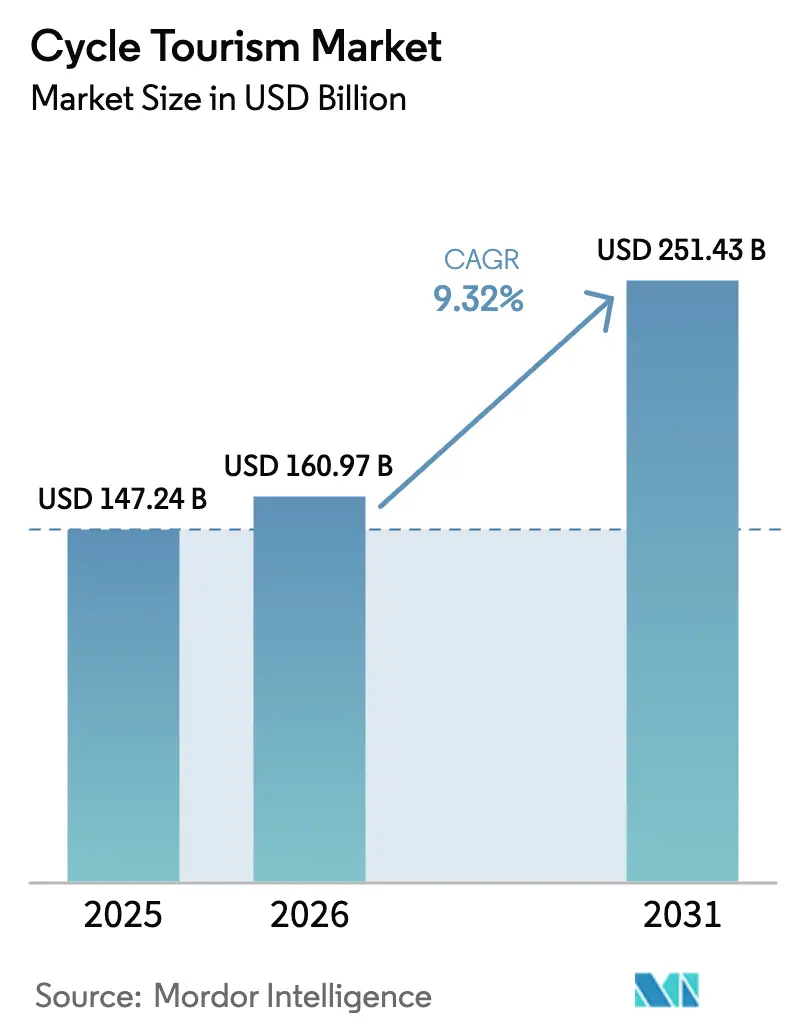
The Cycle Tourism Market size was valued at USD 147.24 billion in 2025 and estimated to grow from USD 160.97 billion in 2026 to reach USD 251.43 billion by 2031, at a CAGR of 9.32% during the forecast period (2026-2031).
Network-wide infrastructure spending, expanding e-bike fleets, and government sustainability mandates converge to lengthen average trip distances and compress booking windows into mobile-friendly transactions. Operators report stronger cross-selling of luggage transfers and premium lodging as travelers trade up for comfort on longer routes, while destination management organizations subsidize signage and safety amenities to capture spillover spending from adjacent leisure sectors. Consolidation remains limited because route knowledge, localized partnerships, and brand intimacy still trump pure scale advantages, although digital marketplaces narrow the visibility gap between global and niche brands. As a result, the cycle tourism market increasingly rewards differentiated itineraries such as culinary trails and corporate wellness retreats that command 18-25% higher per-capita spending than standard departures. The Asia-Pacific corridor, where governments link climate goals to active mobility, demonstrates how targeted incentives can compress years of demand buildup into a single planning cycle.
Key Report Takeaways
- By group type, couples held 35.82% revenue share in 2025, while solo travelers are projected to grow at a 12.15% CAGR through 2031.
- By booking mode, direct channels captured 56.63% of 2025 revenue in the cycle tourism market; marketplace platforms are forecast to advance at a 15.05% CAGR to 2031.
- By age bracket, participants aged 31-50 years accounted for the largest slice at 41.05% in 2025, but the 18-30 years cohort shows the highest 12.88% CAGR through 2031.
- By geography, Europe led with 43.10% of the cycle tourism market share in 2025, whereas Asia-Pacific is expanding at a 13.74% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Global Cycle Tourism Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of dedicated cycling infrastructure | +2.8% | Global; EU and North America lead | Long term (≥ 4 years) |
| Rising popularity of e-bikes | +2.1% | Global; strongest in Asia-Pacific | Medium term (2-4 years) |
| Government sustainability initiatives | +1.9% | Europe and North America, emerging in Asia-Pacific | Long term (≥ 4 years) |
| Digital booking platforms and social media | +1.6% | Global; higher penetration in developed markets | Short term (≤ 2 years) |
| Bike-with-wine or food trails | +0.8% | Core in Europe, gaining ground elsewhere | Medium term (2-4 years) |
| Corporate wellness offsites | +0.5% | North America and Europe, early Asia-Pacific | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Rapid Expansion of Dedicated Cycling Infrastructure
Investments such as the 90,000-kilometer EuroVelo network, valued at USD?51.30?billion (EUR 44 billion), illustrate how contiguous routes convert rural byways into high-yield tourism corridors[1]European Cyclists’ Federation, “EuroVelo Cycling Tourism Data,” ecf.com.. National initiatives amplify that effect: the Netherlands earmarked USD 20.99 million (EUR 18 million) in 2024 for cycling highways, and Quebec’s 2025-2030 plan links cultural hubs, lodging clusters, and way-finding technologies to turn linear trails into economic ecosystems[2]Government of the Netherlands, “18 Million Euros for Cycling Highways,” government.nl. . Multi-day itineraries, once limited to elite cyclists, now entice casual riders who perceive new paths as safe, sign-posted, and serviceable. Operators respond by introducing luggage-forwarding and on-call mechanical support, services that boost ancillary revenue and retention. The infrastructure wave also lowers entry barriers for small regional firms because fixed-route visibility reduces marketing costs. Over the long term, route density and cross-border connectivity will keep average trip lengths and spend per traveler on an upward slope.
Rising Popularity of E-bikes Across Age Groups
Global production surpassed 40 million e-bikes in 2025, and mid-drive motors now dominate tourism fleets due to superior hill-climbing torque and battery life[3]University of Twente, “New Warning System for E-bikes to Prevent Accidents,” utwente.nl. . The technology flattens terrain barriers, opening mountain passes to less-fit travelers and extending viable season windows in alpine regions where snow clearance is prompt. Operators that embrace e-bike inventory witness broader demographic uptake: riders over 50 years, once marginal, now account for nearly one-quarter of participation and display above-average spend on gourmet lodging and spa addons. Competitive segmentation is also evolving, with companies like Backroads rolling out “Unplugged” itineraries for purists who reject motor assistance, thereby positioning manual and electric tours as complementary rather than cannibalistic products. These parallel tracks enable brands to fine-tune price ladders and yield management throughout the forecast horizon.
Government Sustainability Initiatives Promoting Active Mobility
Policy levers from carbon taxes to highway toll reallocations push governments to bankroll cycling infrastructure as a low-emission transport alternative. The EU Declaration on Cycling obliges member states to raise cycling budgets by 50% by 2030, a directive already visible in Slovenia’s Green Wellness Route linking thermal spas via bike paths to diversify rural economies. Grants often bundle way-finding tech, parking hubs, and public-private marketing campaigns, thus absorbing fixed costs that individual operators could not shoulder alone. Over time, such frameworks standardize safety norms, signage, and quality ratings, lowering perceived risk for international visitors and elevating baseline service expectations.
Digital Booking Platforms & Social Media Inspiration
Direct bookings remain dominant, yet aggregator momentum reshapes the marketing calculus. GetYourGuide’s USD 187.2 million revenue underscores venture appetite for scalable activity marketplaces, and its SEO heft delivers long-tail visibility that previously demanded high ad spend. Social platforms like Strava convert segment times into brag-worthy content, funneling users toward paid tours that replicate viral routes. Operators now embed GPX files and Instagram hotspots in trip dossiers, shifting value from pure guiding to curated storytelling. Younger cohorts, whose trip discovery often begins on mobile, fuel double-digit growth but also pressure suppliers to streamline check-out flows and offer flexible cancellation.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Safety concerns on mixed-traffic routes | ?1.8% | Global; higher severity in developing markets | Long term (≥ 4 years) |
| Seasonality and weather dependence | ?1.2% | Temperate regions, notably Europe and North America | Medium term (2-4 years) |
| Micro-mobility substitutes | ?0.9% | Urban centers worldwide | Short term (≤ 2 years) |
| E-bike charging logistics in remote areas | ?0.6% | Rural zones worldwide | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Safety Concerns on Mixed-Traffic Routes
Traffic safety represents the primary barrier to market expansion, with cyclist fatalities rising 11.4% in Germany during 2024 to 441 deaths, highlighting infrastructure gaps that deter novice participants[4]German Federal Statistical Office, “Road Traffic Accidents 2024,” destatis.de. . New York City recorded increasing bicycle deaths despite infrastructure investments, indicating that safety concerns persist even in markets with dedicated cycling infrastructure. These safety perceptions disproportionately impact family segments and older demographics, limiting market expansion beyond core cycling enthusiasts. The University of Twente's development of e-bike warning systems represents technological solutions to safety challenges, yet widespread adoption requires regulatory frameworks and standardization that may take years to implement.
Seasonality & Weather Dependence
Weather dependence constrains revenue generation in temperate markets, with operators reporting occupancy drops exceeding 40% during off-peak seasons. Climate change introduces additional volatility, with extreme weather events disrupting established seasonal patterns and forcing operators to develop more flexible itinerary management systems. Spain's tourism sector demonstrates adaptation strategies through shoulder season promotion and indoor activity integration, yet these approaches require significant operational restructuring and marketing investment. The seasonality challenge particularly affects European operators, where the 43.74% market share concentration amplifies weather-related revenue volatility across the industry.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Group: Couples Drive Revenue While Solo Growth Accelerates
Couples represent 35.82% of cycle tourism bookings in 2025, reflecting the activity's appeal as a shared adventure experience that balances physical challenge with romantic destination exploration. Solo travelers, despite holding 18.44% current market share, exhibit the strongest growth trajectory at 12.15% CAGR through 2031, driven by increasing comfort with independent travel and digital tools that reduce solo journey complexity. Group/Friends bookings account for 34.12% of the cycle tourism market, benefiting from social media sharing dynamics and group discount structures that operators use to fill capacity during shoulder seasons. Family segments, while smaller at 11.62% share, show resilience through multi-generational appeal and school holiday timing that provides revenue stability during traditional off-peak periods. The demographic shift toward solo travel reflects broader lifestyle changes, with operators like G Adventures adding 25 new Active trips in 2025 specifically targeting independent travelers seeking structured yet flexible itineraries. Corporate wellness adoption represents an emerging opportunity, with companies increasingly selecting cycling retreats for ESG-aligned team building that combines physical activity with sustainable travel practices. This trend particularly benefits premium operators who can provide full-service logistics and safety management that corporate risk policies require.


By Booking Mode: Direct Channels Dominate Despite Marketplace Growth
Direct bookings maintain 56.63% cycle tourism market share in 2025, reflecting customer preference for specialized operator expertise and customized itinerary development that marketplace platforms cannot easily replicate. Marketplace booking channels, growing at 15.05% CAGR through 2031, capitalize on convenience and price comparison capabilities that appeal particularly to younger demographics and first-time cycle tourists. Travel agent bookings hold a 16.55% share, concentrated in luxury segments where complex logistics and destination expertise justify intermediary fees. The marketplace acceleration reflects GetYourGuide's success in standardizing activity booking processes while maintaining local operator relationships, creating distribution efficiency that benefits both suppliers and consumers. However, direct booking retention indicates that cycle tourism's complexity and safety requirements favor specialized operators who can provide detailed route guidance, equipment support, and emergency response capabilities that generalist platforms struggle to match. This dynamic creates a bifurcated market where simple day tours migrate to marketplaces while multi-day expeditions remain direct-booked.

By Age Group: Prime Demographics Expand Through Technology
The 31-50 years segment commands 41.05% of the cycle tourism market share in 2025, representing peak earning power combined with physical capability and discretionary time for multi-day cycling adventures. The 18-30 years cohort, despite a 35.48% current share, drives growth at 12.88% CAGR through 2031, fueled by social media inspiration and digital-native booking behaviors that reduce traditional barriers to adventure travel participation. Participants over 50 years hold 23.47% share but benefit significantly from e-bike technology that extends participation years and enables access to challenging terrain. E-bike adoption particularly transforms the over-50 demographic by eliminating fitness barriers that previously limited participation to elite cyclists. Operators report that e-bike tours enable 20-30% longer daily distances while reducing physical strain, expanding the addressable market size, and enabling premium pricing for technology-enhanced experiences. The age distribution evolution suggests market maturation, with younger participants driving volume growth while older segments contribute disproportionate revenue through luxury positioning and extended trip durations.

Geography Analysis
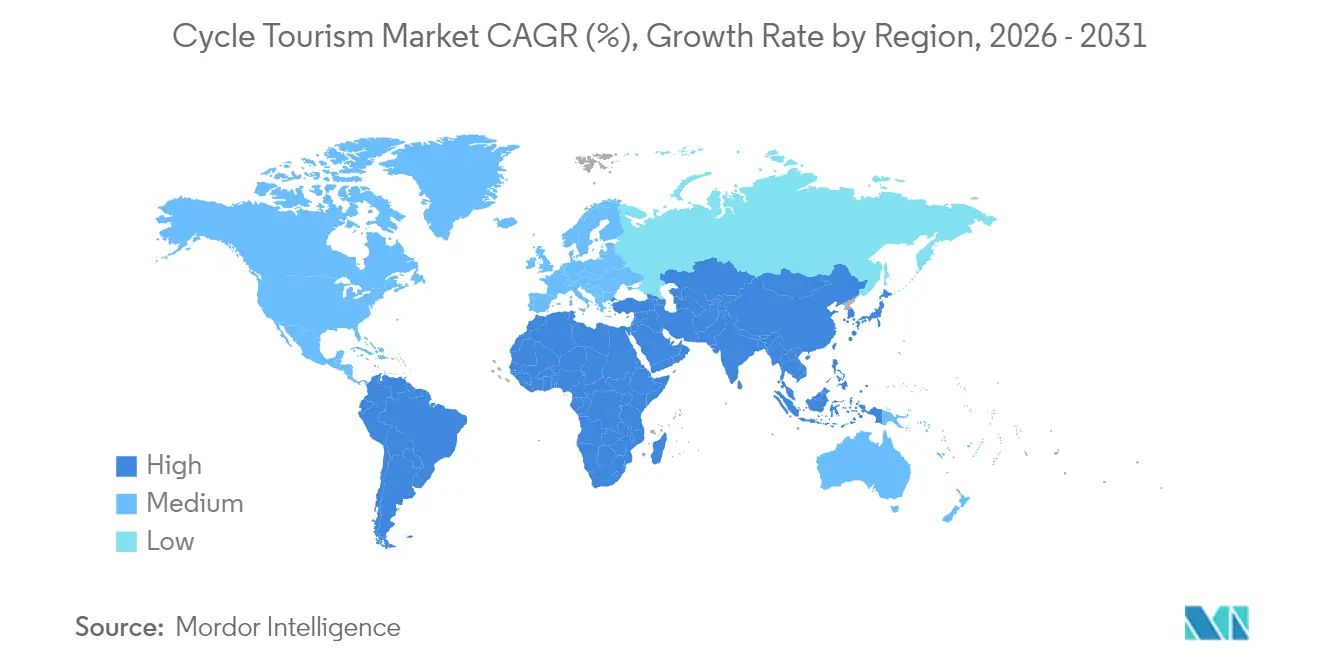
Europe retains 43.10% of 2025 revenue, buoyed by interlinked infrastructure, cultural bike affinity, and policy incentives like the EU’s cycling budget escalation. Germany’s mature operator base leverages thirty-year route curation to maintain steady margins even as competition intensifies. Nonetheless, Europe’s 7.86% CAGR signals deceleration relative to frontier regions, compelling incumbents to introduce multi-modal packages that blend rail segments with trans-border bike loops to refresh value propositions. Asia-Pacific, posting a 13.74% CAGR, benefits from China’s green transport subsidies and India’s growing middle class that views cycling holidays as status symbols. Taiwan’s YouBike expansion and Japan’s Shimanami Kaido marketing funnel illustrate how infrastructure, branding, and hospitality training can accelerate route adoption. Rural Japan, in particular, integrates cycle trails with farm-stay programs, channeling tourism receipts into local revitalization.
North America accounts for 25.35% of the cycle tourism market, with a projected 8.62% CAGR through 2031. This growth is driven by Rails-to-Trails conversions and state-level efforts to promote cycling tourism. Increasing health consciousness and interest in outdoor recreation are further fueling demand. Luxury tour operators like Backroads capitalize on these trends with premium pricing and comprehensive service offerings. Corporate wellness initiatives are also playing a key role, as companies seek ESG-aligned team-building activities. This has created a high-revenue market segment that outperforms traditional leisure bookings in per-participant value.

Regulatory Landscape
Cycle tourism is shaped by tourism governance, active-mobility safety rules, and sustainability reporting frameworks that influence product design and whether destinations can access public support. In Europe, policy direction has tightened around sustainable and integrated tourism, with the Council of the European Union emphasizing decarbonization, circularity, and conservation. This has fed into destination funding for route signage, safety amenities, and low-emission transport links for cycling visitors.
On measurement and compliance, 2026 brought stronger standardization signals for tourism-wide sustainability metrics through ISO 18060:2026, which defines indicators for organizations across the tourism value chain, and through the OECD Tourism Committee indicator approach cited in OECD Tourism Trends and Policies 2026. These frameworks move operator communication away from marketing-led claims toward auditable reporting, which can influence how operators choose lodging, transport partners, and local suppliers when incentives or promotion eligibility depend on documented environmental and social performance.
Value Chain Analysis
The cycle tourism value chain combines destination-side infrastructure and governance with operator-led product assembly and logistics execution. Upstream inputs include public cycling infrastructure (routes, signage, safety features), bike and e-bike manufacturing and rental provisioning, accommodation and food service partners, and insurance and permitting where required. Midstream, tour operators and destination management organizations bundle routes, guiding (or self-guided roadbooks), safety protocols, and ancillary services such as luggage transfers, on-call mechanical support, and local experiences (culinary trails and spa stops), then distribute inventory through direct websites, travel agents for high-touch itineraries, and marketplaces.
Downstream fulfillment is operationally intensive and increasingly tech-enabled. It depends on local support networks, transfer vehicles, and apps for navigation, service coordination, and guest communication. Eurofun Touristik (Eurobike/Eurohike) shows how vertical coordination works in Europe via a branch-office model and owned or closely managed regional entities, supporting transfers and service consistency at scale. Sustainability measurement frameworks such as ISO 18060:2026 and evolving GSTC-aligned practices also feed into the chain by pushing operators and suppliers toward trackable inputs (energy, transport, procurement) rather than isolated measures like basic recycling.
Competitive Landscape
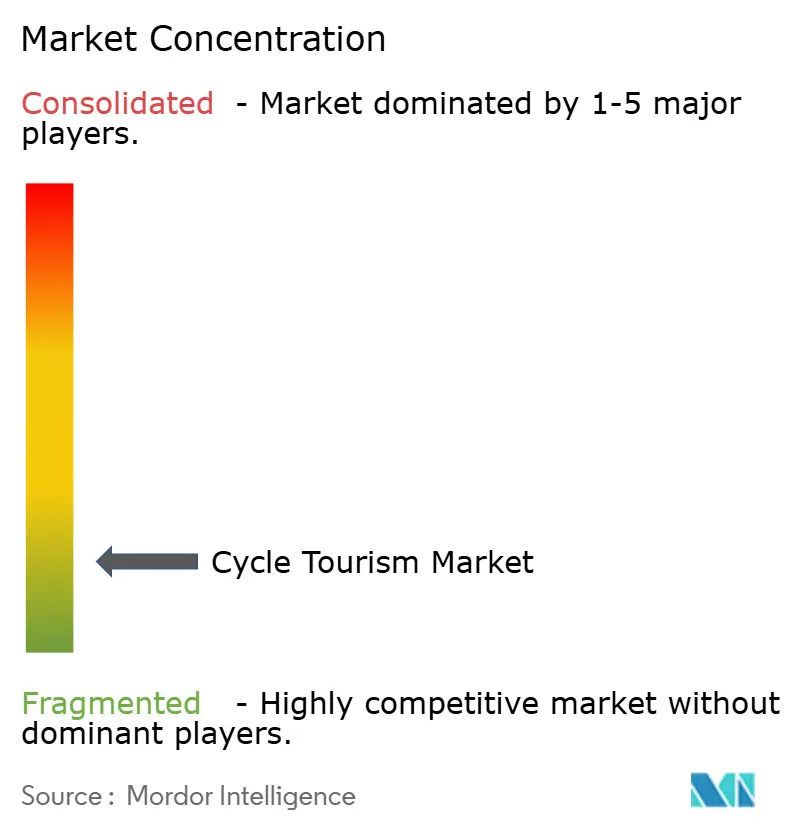
The cycle tourism market is highly fragmented, with the top five operators collectively holding just 16% of the total market share. This fragmentation opens the door for consolidation while also allowing smaller players to differentiate through niche positioning. Leading companies such as TUI Group (with a 4.2% share via Eurobike) and Intrepid Travel (3.7% share) benefit from economies of scale in route development, equipment sourcing, and marketing. However, smaller operators remain competitive by leveraging local expertise and focusing on specialized offerings. The diverse geography of the industry limits standardization, making destination-specific knowledge a key competitive asset. As a result, large-scale consolidation remains complex despite market share opportunities.
Technology adoption and vertical integration are emerging as key strategic trends among operators. Companies are increasingly investing in digital booking systems, GPS-enabled navigation, and e-bike fleet management to streamline operations and enhance customer experience. These technological advancements not only reduce costs but also help create more personalized and efficient tour offerings. Larger players use their scale to adopt these innovations faster, but smaller operators are also finding success with targeted tech solutions. Intrepid Travel’s $100 million acquisition of Sawadee Reizen highlights a consolidation strategy aimed at expanding geographic coverage and customer base. Meanwhile, G Adventures demonstrates an organic growth approach with the launch of 25 new Active trips planned for 2025.
Looking ahead, significant white-space opportunities are emerging in niche segments such as corporate wellness programs, gastro-cycling tours, and underdeveloped international markets. Companies that tap into these segments early can gain a first-mover advantage, particularly in regions where infrastructure is improving but established operators are scarce. Corporate wellness travel offers especially high revenue potential due to the growing demand for ESG-aligned, health-focused team experiences. Gastro-cycling, combining culinary tourism with active travel, also presents strong appeal for premium travelers. As infrastructure expands in emerging markets, there is increasing demand for operators who can provide reliable, high-quality experiences in less-explored destinations. These evolving dynamics point to a market ripe for innovation, specialization, and strategic expansion.
Cycle Tourism Industry Leaders
TUI Group (Eurobike/Eurohike division)
Intrepid Travel
G Adventures
Backroads
Exodus Travels (Travelopia)
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A clear opportunity is the operational scale-up of supported self-guided and semi-guided products. Logistics capacity and digital coordination help convert route density into higher throughput and broader demographic reach. Eurofun Touristik describes a service model built around 12 branch offices across Europe, support for about 40,000 active holidaymakers per season, and a fleet of 75+ vehicles for luggage and passenger transfers. This makes transfer infrastructure and local coverage a differentiator for multi-day cycling holidays, and it provides a reference model for expanding into additional corridors and shoulder-season operations.
Sustainability reporting and destination governance also create whitespace for standardized, measurable cycling holidays that can be promoted through official channels. ISO 18060:2026 sustainability indicators and the OECD 2026 emphasis on value-based tourism models (integrating social and environmental considerations into planning) support more comparable disclosure across the tourism value chain. That structure can be translated into carbon-labeled, rail-plus-ride, and low-impact itineraries where public bodies prioritize decarbonization and circularity. Commercially, marketplace growth and mobile-first trip planning raise the value of operator apps and real-time service coordination (for example, navigation and guest-information tools used by Eurobike and Eurohike), helping convert late booking windows while keeping service quality and safety management on longer routes.
Recent Industry Developments
- May 2026: TUI Group confirms its revised 2026 fiscal year outlook in a half-year results update, noting the shifting of consumer demand toward western Mediterranean destinations like Spain and Greece. The update signals strategic readjustment to capture cycling-related travel demand. The shift broadens demand forecasts and diversifies product mix.
- April 2026: G Adventures commences departures for 14 new itineraries developed with National Geographic Expeditions (multi-region Asia and Europe). The launch expands cycling-adventure offerings tied to premium experiences. The partnership strengthens brand association and geographic coverage through a high-profile collaboration.
- February 2026: Intrepid Travel announces Buffalo Ride Colombia cycling fundraiser trip (Aug 28 - Sep 4, 2026). The product adds a fundraising cycling focused option in active-travel segment. The initiative demonstrates integration of social impact with cycling itineraries, expanding customer base.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the cycle tourism market covers traveler spending linked to leisure trips where cycling is a main activity. This includes guided and self planned itineraries, bicycle rentals, route services, lodging tied to cycling stays, and trip packages booked through tour operators or travel platforms.
Scope exclusions: We exclude daily commuting, bicycle manufacturing and retail sales, and purely competitive racing events that are not tourism led.
Segmentation Overview
- By Group
- Group/Friends
- Couples
- Family
- Solo
- By Booking Mode
- Direct
- Travel Agent
- Marketplace Booking
- By Age Group
- 18 to 30 Years
- 31 to 50 Years
- More Than 50 Years
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South-East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
We start with public travel and mobility evidence to anchor the demand pool and typical spend per trip. Sources used include UN tourism statistics, national tourism boards and visitor surveys, transport and cycling infrastructure agencies, EuroVelo and other cycling route bodies, and peer reviewed studies on the economic impact of cycling tourism.
Next, we map how money flows across the trip to avoid double counting between components. We reviewed company annual reports, investor decks, and reputable press to understand packaged tour mix, pricing changes, and booking patterns. Where public reporting was thin, paid subscriptions for company financials and a shipment level import export view were used selectively. This desk list is indicative only, and many other sources were used to collect data, validate assumptions, and clarify gaps.
Primary Interviews and Surveys
To make the sizing practical, we spoke with tour operators, destination bodies, bike rental and service providers, and travel intermediaries. The goal was to confirm what is counted as a cycle tourism trip versus what is treated as general leisure travel.
Respondent input also helped adjust for seasonality, guided versus self guided mix, and the share of spending captured inside the destination versus before departure. We kept coverage across the major tourism regions so weak data in one area did not drive the total.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 15% | APAC: 43% |
| Mid tier: 49% | Functional/Unit leaders: 27% | EMEA: 35% |
| Smaller Players: 16% | Managers: 58% | Americas: 22% |
Market-Sizing & Forecasting
The core model is built with a top-down approach where tourism trip volumes and cycling participation signals are reconstructed by region, then converted into value using spend per trip benchmarks. We also corroborate totals through selective bottom-up checks, including sampling operator price lists, comparing packaged tour revenue pools, and applying realistic volume assumptions to common trip formats, before final adjustments are applied.
The inputs that most affect the model include inbound and domestic visitor nights, cycling route usage and permit counts where available, guided tour share versus self planned travel, typical rental days per trip, and average daily spend differences between urban and rural routes. Forecasts are driven using scenario analysis supported by expert views on infrastructure additions, airfare and lodging price direction, and consumer preference for low impact travel, and then translated into region specific growth paths. When bottom-up data is missing for smaller destinations, we fill gaps with proxy ratios from comparable markets and then sanity check the result against tourism receipts and known capacity constraints.
Data Validation & Update Cycle
Our validation combines cross source comparisons with boundary checks so the number stays aligned with observed travel behavior. Model outputs are compared against independent signals such as tourism receipts trends, operator booking momentum, route usage growth, and lodging performance in cycling corridors. Where there are variances, we review the drivers with a second analyst before sign-off.
The report is refreshed annually, and interim updates are triggered when material events show up, including major infrastructure openings, policy changes, or sharp travel demand shocks. Before delivery, we do a final pass to confirm the latest public data and recent interview notes are reflected in the totals and the forecast.
麻豆视频's Cycle Tourism Market Size Compared Against Other Published Estimates
Published market sizes for cycle tourism can differ because the market boundary is not always treated the same. Some models blend economic impact style totals with spend directly tied to cycling trips. Differences also come from the base year, how inflation is applied to trip pricing, and how the timing of regional tourism recovery is reflected.
Route usage indicators, tourism receipt trends, and operator booking feedback are used as checks to keep 麻豆视频 focused on cycling led trip demand rather than a broader recreation spend pool. As a result, some published totals can look larger or smaller even when they cite the same year.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 147.24 B (2025) | |
| Global Consultancy A | USD 172.00 B (2024) | This estimate appears to use a broader definition that can blend general adventure travel and cycling recreation spend into tourism, and it also starts from a different base year that changes the inflation and recovery effect. |
| Industry Association B | USD 47.83 B (2012) | This figure is an EU economic impact style value for an older year, so it reflects a regional footprint and a legacy price level, and it is not directly comparable to a current global market sizing model. |
The spread in the table mainly comes from scope and timing, not just growth assumptions. By keeping the count tied to cycling centered trips and by applying repeatable trip volume and spend logic by region, the estimate stays explainable and easier to update as new travel and route signals become available.


Key Questions Answered in the Report
What is the projected value of the cycle tourism market in 2031?
The cycle tourism market is expected to reach USD 251.43 billion by 2031, growing at a 9.32% CAGR from 2026.
Which region is expanding the fastest in cycle tourism?
Asia-Pacific leads growth with a projected 13.74% CAGR through 2031 as e-bike adoption and infrastructure budgets surge.
How large is Europe’s share of cycle-based travel revenue?
Europe accounted for 43.10% of global spending in 2025, underpinned by dense cross-border networks and supportive policies.
What booking channel dominates multi-day cycling holidays?
Direct booking channels hold 56.63% of revenue because travelers seek operator expertise on routes, equipment, and safety.
Which traveler segment is growing quickest?
Solo riders show the strongest momentum, expanding at a 12.15% CAGR through 2031 thanks to app-based navigation and flexible itineraries.
Page last updated on:



