
Europe Metal Precision Turned Product Manufacturing Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 18.97 Billion |
| Market Size (2026) | USD 19.94 Billion |
| Market Size (2031) | USD 25.52 Billion |
| Growth Rate (2026 - 2031) | 5.11 % |
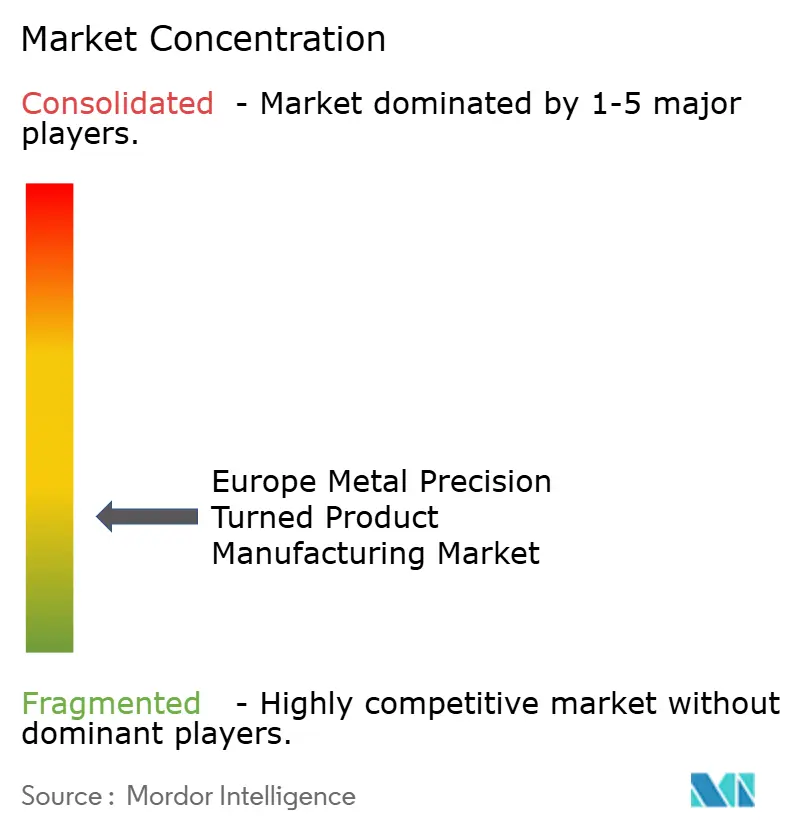
| Market Concentration | Low |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Europe Metal Precision Turned Product Manufacturing Market Analysis by 麻豆视频
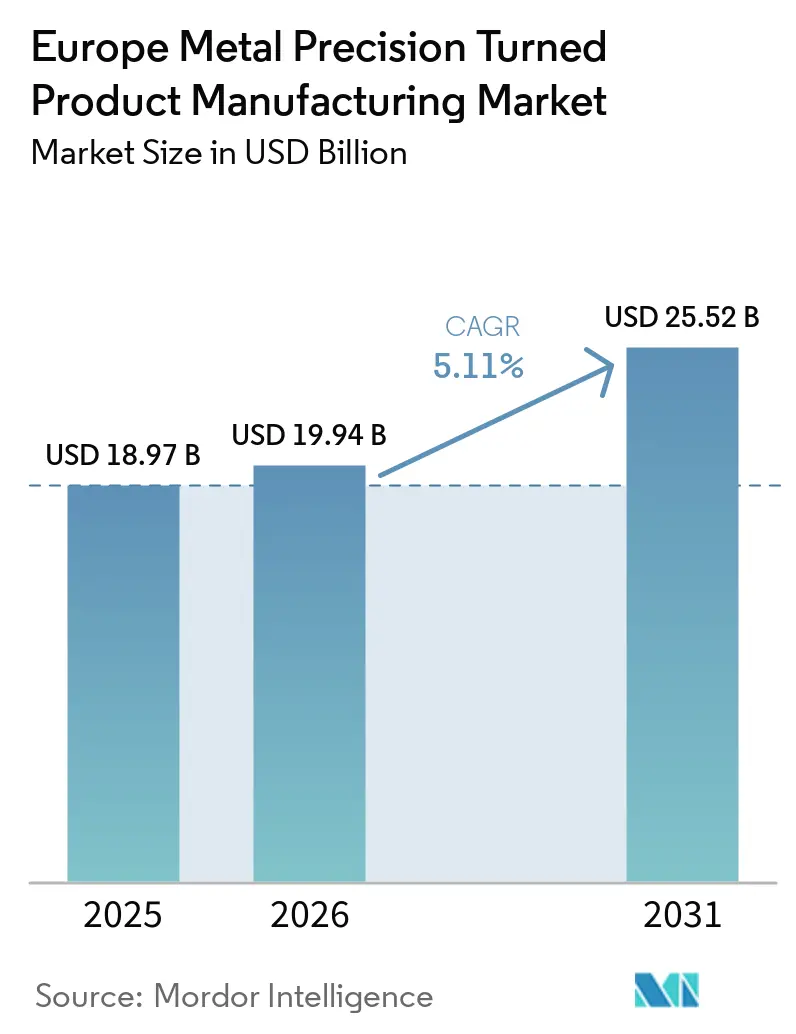
The Europe metal precision turned product manufacturing market size was valued at USD 18.97 billion in 2025, and is projected to grow from USD 19.94 billion in 2026 to reach USD 25.52 billion by 2031, at a 5.11% CAGR over 2026–2031. Electrification is changing the mix of parts ordered by automotive customers, with demand moving from conventional engine components toward motor shafts, battery hardware, e-axle housings, and power-electronics parts. These applications require more precise dimensions, dependable surface finishes, and repeatable production across long runs. Medical and dental manufacturing also supports demand, as implant makers require titanium components produced under tightly controlled quality systems. European procurement strategies are placing greater weight on reliable regional supply, documented material provenance, and shorter lead times. These conditions favor suppliers that combine multi-axis machining, quality documentation, and automated handling in a single production process.
Key Report Takeaways
- By operation, CNC operations held 82.37% of the European metal precision turned product manufacturing market share in 2025 and is projected to grow at a 6.28% CAGR through 2031.
- By machine type, CNC lathes and turning centers accounted for 48.26% of the European metal precision turned product manufacturing market share in 2025, while CNC multi-axis turning machines are forecast to grow at an 8.47% CAGR through 2031.
- By product type, bushings and sleeves held 24.18% of the European metal precision turned product manufacturing market share in 2025, while medical and dental components are projected to expand at an 8.84% CAGR through 2031.
- By material, steel and stainless steel accounted for 43.27% of the European metal precision turned product manufacturing market share in 2025, while titanium and titanium alloys are forecast to grow at a 9.16% CAGR through 2031.
- By end user, automotive held 31.42% of the European metal precision turned product manufacturing market share in 2025, while medical and dental are expected to advance at an 8.67% CAGR through 2031.
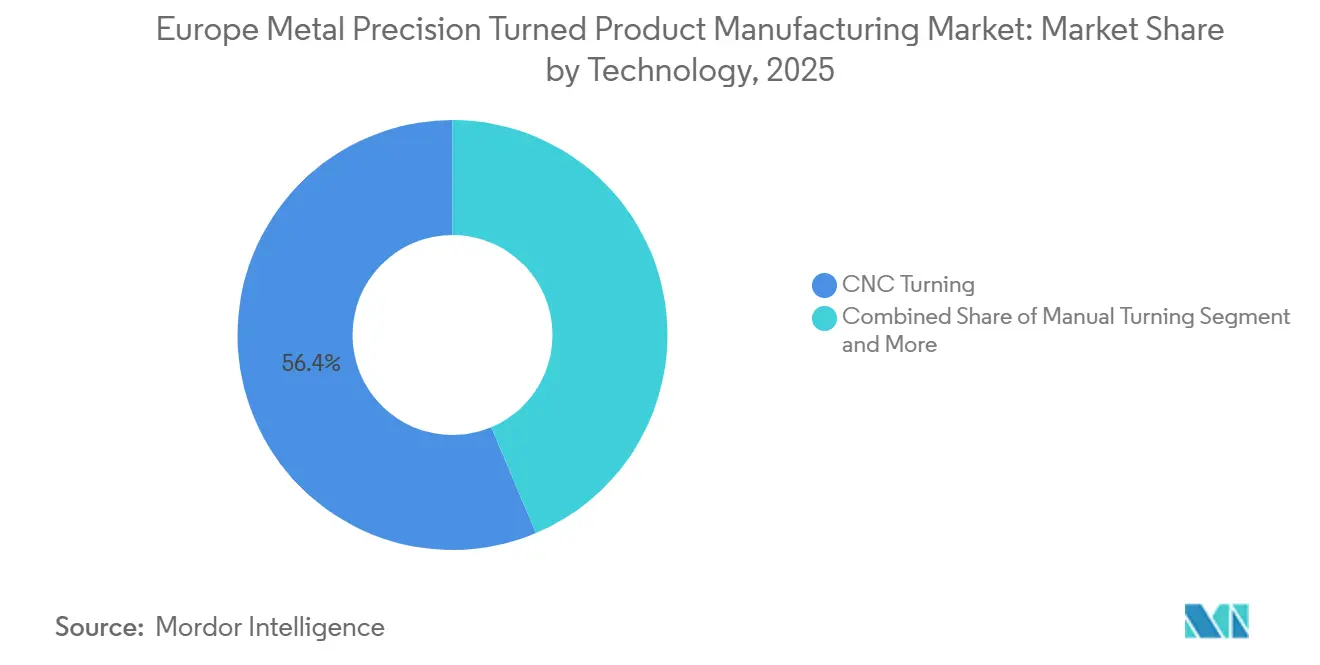
- By technology, CNC turning accounted for 56.35% of the European metal precision turned product manufacturing market share in 2025, while multi-axis turn-mill machining is forecast to grow at an 8.38% CAGR through 2031.
- By production scale, high-volume production held 46.28% of the European metal precision turned product manufacturing market share in 2025 and is projected to grow at a 6.17% CAGR through 2031.
- By geography, Germany held 25.36% of the European metal precision turned product manufacturing market share in 2025, while Poland is forecast to grow at a 7.28% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Worldwide, activity is shaped by contributions from multiple regions, with Europe representing one of the more structurally developed among them. The global report on metal precision turned product manufacturing market by 麻豆视频 reflects how these regional layers combine into a single system.
Market Trends and Insights
Drivers Impact Analysis of Europe Metal Precision Turned Product Manufacturing Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Automotive Electrification and Lightweight Component Demand | +1.2% | Germany, France, Italy, Spain, Poland, Czechia | Short term (≤ 2 years) |
| Expansion of Medical, Dental, and Implant Manufacturing | +0.9% | Switzerland, Germany, Italy, France, United Kingdom | Medium term (2-4 years) |
| Rising Adoption of Multi-Axis and Swiss-Type CNC Turning | +0.8% | Europe, concentrated in Switzerland, Germany, France | Short term (≤ 2 years) |
| Aerospace Production and Tight-Tolerance Component Requirements | +0.6% | France, Germany, United Kingdom, Poland | Medium term (2-4 years) |
| Digital Product Passports and Traceable Material Provenance | +0.4% | European Union, early gains in Germany, France, Netherlands | Long term (≥ 4 years) |
| Nearshoring of Critical Components Within European Supply Chains | +0.3% | Poland, Czechia, Romania, Hungary, Germany | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Automotive Electrification and Lightweight Component Demand
Battery-electric vehicle production is changing the requirements for parts in the European metal precision-turned parts market. Traditional ferrous powertrain volumes are declining in some applications, but motor shafts, battery-module end caps, e-axle housings, and power-electronics substrates create new requirements. The VDA reported that 40% of cars manufactured in Germany in 2025 were electric [1]"New record: 40% electric share of passenger car production in 2025," VDA, vda.de. Copper-alloy bus bars require controlled surface quality, while aluminum motor housings must maintain accurate interference fits through thermal cycling. Suppliers that formerly focused on manual-transmission parts need stronger machining and measurement capability to compete for this work. The change does not produce a uniform replacement pattern across suppliers. It rewards companies that can translate new vehicle designs into stable, repeatable machining routes before production volumes rise.
Expansion of Medical, Dental, and Implant Manufacturing
Medical and dental demand supports the European metal precision-turned parts market, as implants require consistent geometry and traceable manufacturing. Production is concentrated in established precision turning areas, including Switzerland’s Jura Arc and southern Germany. Eurostat reported that people aged 65 or older accounted for more than 22% of Europe’s population in 2025 [2]"Population structure and aging," Eurostat, ec.europa.eu. This demographic profile supports demand for orthopedic revisions, dental replacements, and related implant procedures. ISO 13485 quality requirements raise the barrier for smaller suppliers and favor established specialists with validated processes. For contract manufacturers, the commercial value lies in maintaining a validated process over the full life of an implant program. This makes reliable inspection, batch records, and material control as important as cutting capacity.
Rising Adoption of Multi-Axis and Swiss-Type CNC Turning
The European metal precision-turned product manufacturing market is shifting from basic CNC turning to multi-axis turn-mill centers and Swiss-type sliding-headstock machines. These systems can complete complex geometries with fewer setups and reduce the likelihood of errors between operations. Aerospace customers increasingly specify complete machining in one setup during supplier qualification. Medical device producers also place great importance on stable processes when assessing potential failures. A multi-axis cell can remove downstream deburring and grinding stages for suitable medium-series parts. The higher equipment cost makes access to capital important, but the technology can improve repeatability, lead time, and documented process control. The practical benefit is strongest when several critical features must align on the same part. Suppliers can reduce handling without sacrificing the ability to document the completed manufacturing sequence.
Nearshoring of Critical Components Within European Supply Chains
Regional sourcing is giving the European metal precision turned product manufacturing market a stronger role in supply chains that value resilience and responsive delivery. Automotive and aerospace assemblers are seeking qualified suppliers closer to assembly locations and engineering teams. This change benefits Polish machining clusters that combine lower operating costs with expanding quality certification. Robotic loading, unattended machining, and production data systems are central to this model because they reduce the labor-cost gap between locations. Suppliers that can provide both capacity and proof of quality are better placed to qualify as regional alternatives. A closer supplier relationship also makes engineering changes easier to manage. It gives purchasers a shorter route for resolving quality issues, qualifying replacements, and responding to changes in production schedules.
Restraints Impact Analysis of Europe Metal Precision Turned Product Manufacturing Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Scarcity of Skilled CNC Programming and Metrology Talent | -0.8% | Germany, Italy, France, Switzerland, Poland | Short term (≤ 2 years) |
| High Energy, Compliance, and Equipment-Conversion Costs | -0.6% | Germany, Netherlands, Belgium, Italy | Medium term (2-4 years) |
| Volatility in Aluminum, Steel, Brass, and Titanium Input Costs | -0.4% | European Union, most acute in Germany and France | Short term (≤ 2 years) |
| Long Validation Cycles for Regulated Medical Components | -0.3% | Switzerland, Germany, France, United Kingdom | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Scarcity of Skilled CNC Programming and Metrology Talent
The shortage of experienced CNC programmers and metrology specialists limits capacity across the European metal precision turned product manufacturing market. Shops need employees who can program multi-axis machines, interpret dimensional results, and manage process changes without compromising the quality of parts. This requirement is more demanding than operating a conventional lathe or handling a single production task. Older workers in precision engineering clusters also create replacement needs that apprenticeship programs may not meet quickly enough. Automation can reduce manual handling, but it increases the demand for mechatronics and process control skills. The constraint affects both quality and output because advanced work depends on programming judgment and careful interpretation of measurement results. Staffing pressures are therefore most severe in operations serving regulated or aerospace customers.
High Energy, Compliance, and Equipment-Conversion Costs
High operating and investment costs can slow modernization in the European metal precision turned parts market. Eurostat reported that the EU non-household electricity price averaged EUR 18.37 per 100 kWh in the second half of 2025[3]"Non-household electricity prices in 2nd half of 2025: -3.5%," Eurostat, ec.europa.eu. Precision turning uses energy for spindle operation, coolant management, high-pressure delivery, and measurement equipment. A move from a conventional cell to a robot-tended multi-axis system can require a substantial capital commitment. The German turning-parts association reported weak investment conditions after lower revenue in 2025, even as incoming orders showed signs of stabilization. Smaller shops may delay upgrades when order visibility is limited, widening the capability gap with well-financed competitors—these costs influence which projects receive investment first. Shops often prioritize upgrades that solve a clear customer requirement or provide measurable savings in handling, scrap, and inspection time.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Europe Metal Precision Turned Product Manufacturing Market Segment Analysis
By Operation:
CNC Production Expands Its Lead Over Manual WorkCNC operations accounted for 82.37% of the European metal precision-turned product manufacturing market share in 2025 and are forecast to grow at a 6.28% CAGR through 2031. The share reflects its central role in automotive, medical, aerospace, and industrial orders that require repeatable tolerances. Manual operation remains relevant for repair, legacy work, and bespoke jobs with limited volumes. Its role is likely to remain narrow as new capacity is built around programmable equipment. Digital programs reduce setup time for repeat orders and enable more consistent first-article inspection. This makes CNC production more practical, even for smaller suppliers serving recurring customer programs. Customers also benefit from programs that can be stored, reviewed, and reused when an order is returned. That continuity is difficult to achieve through manual adjustments alone, especially where tolerances are critical.
CNC systems also support traceable production records, which are increasingly important for regulated and high-value applications. The European metal precision-turned parts industry benefits when shops can link tool data, inspection results, and production history to a specific order. Mixed fleets can be harder to staff because apprentices often train primarily on modern CNC systems. New facilities in Poland, Czechia, and Romania are adopting advanced equipment as they expand capacity.
By Machine Type:
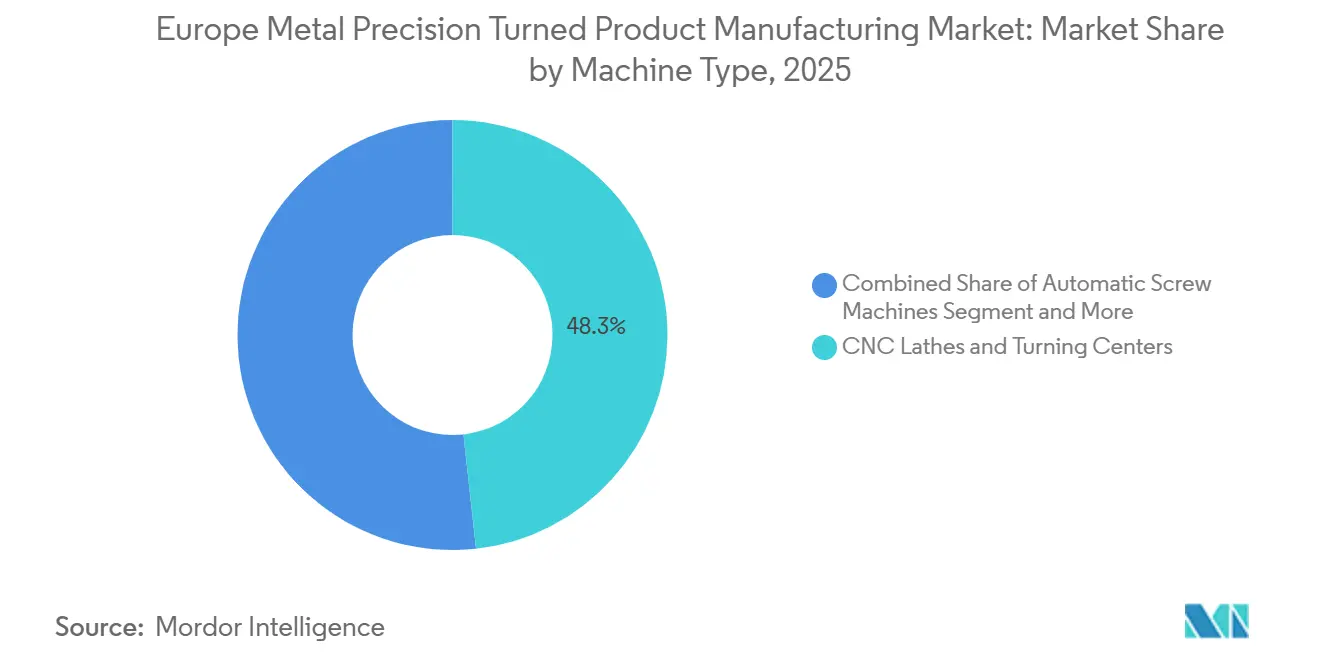
Multi-Axis Systems Gain Importance in Complex WorkCNC lathes and turning centers accounted for 48.26% of the European metal precision turned product manufacturing market share in 2025. Horizontal and vertical centers continue to handle a large share of automotive shafts, housings, and general industrial work. Swiss-type machines serve small, complex components for which close support near the cutting tool is important. CNC multi-axis turning machines are forecast to grow at an 8.47% CAGR through 2031. Aerospace subcontractors use them for parts that require several features to be completed within a tightly controlled sequence. Automatic screw machines and rotary transfer machines remain useful for high-volume standard components. Machine selection is therefore increasingly tied to the part's features rather than to the legacy equipment available in a shop. This favors suppliers that can match process capability to product complexity early in the quotation stage.
The machine mix is changing because customers increasingly request complex parts with fewer handoffs between operations. A multi-axis machine can combine turning, milling, drilling, and finishing operations in a single controlled cycle. This reduces refactoring and improves the consistency of features that relate to one another. Investment in multi-axis equipment can continue during periods of weaker production because it prepares suppliers for more demanding future orders. Schaeffler Aerospace uses WFL MILLTURN machining centers to machine components from Inconel 718, M50NiL, and Cronidur 30, including work requiring fine-turning and milling tolerances. Standard lathes remain essential for many applications, but they cannot meet every specification in aerospace and medical work.


By Product Type:
Bushings Lead Volume While Medical Components Grow FasterBushings and sleeves accounted for 24.18% of the European metal precision-turned product manufacturing market share in 2025. Their position reflects recurring demand from hydraulic equipment, vehicles, and industrial machinery. Screws and bolts remain important high-volume products, although price competition is strong in common steel grades. Shafts, pins, and axial components are used where dimensional consistency must be maintained over extended production runs. Threaded inserts support composite aerospace structures that need accurately formed metallic interfaces. Hydraulic and pneumatic components, turned-milled parts, and other products serve energy, rail, and machinery customers. The contrast between these groups is clear in the purchasing process. Standard products emphasize reliable output and cost control, while medical products emphasize validated capability and long-term quality assurance.
Medical and dental components are forecast to grow at an 8.84% CAGR through 2031. Root implants, gingiva formers, dental abutments, and orthopedic screws use titanium components with strict concentricity requirements. Their specifications place greater emphasis on validated processes than on unit price alone. The EU Medical Devices Regulation requires manufacturers of implantable devices to meet documented verification and validation obligations. These requirements make qualification periods lengthy and can concentrate production among companies with established quality systems. This product mix gives specialist suppliers a route to higher-value, recurring work. This pattern reinforces the importance of careful process planning, documented quality checks, and supplier communication throughout a production program.
By Material:
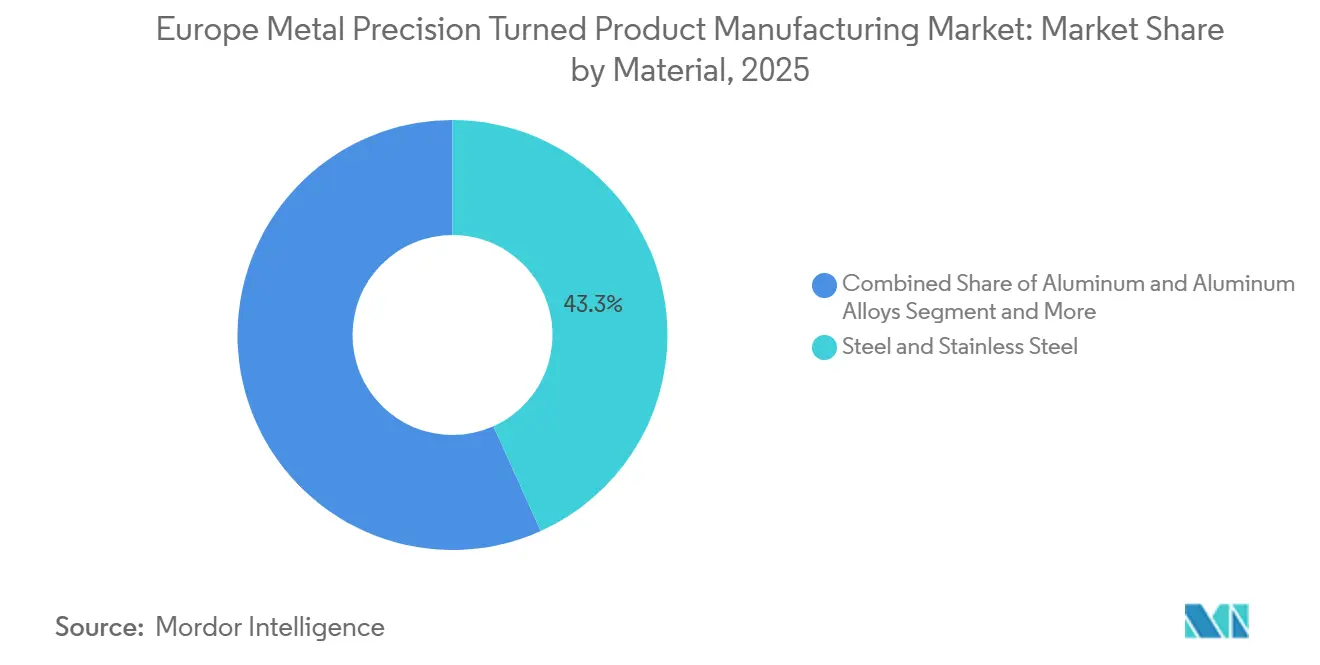
Steel Retains Scale While Titanium Grows FastestSteel and stainless steel accounted for 43.27% of the European metal precision-turned product manufacturing market share in 2025. Automotive, hydraulic, and industrial machinery applications continue to use these grades because of their structural performance and established supply chains. Aluminum alloys are increasingly used in motor housings and battery-module components where lower weight is important. Brass and copper alloys remain well-suited for connectors, fittings, and electrical bushings that require electrical conductivity. Nickel-based and high-temperature alloys are used in aerospace applications, where heat resistance matters more than ease of machining. Engineering plastics and other materials remain limited to specialized housings, bearing surfaces, and food-related applications. Material choice also shapes the production method and the supplier base capable of serving the order. The resulting mix ranges from established steelwork with familiar processes to titanium work requiring specialized technical knowledge.
Titanium and titanium alloys are forecast to grow at a 9.16% CAGR through 2031, the strongest rate among materials. Ti-6Al-4V bar stock is used in dental implants, orthopedic components, and aerospace fasteners. It requires specialized machines, high-quality cutting tools, and carefully controlled coolant delivery. This machining difficulty can concentrate titanium work in experienced Swiss and German facilities. Aerospace and medical programs can compete for access to similar titanium supplies, European metal precision-turned, increasing the importance of dependable procurement arrangements. The European metal precision-turned parts market, therefore, gains from titanium demand, while suppliers without supply agreements may face greater exposure to input costs.
By End User:
Automotive Remains Largest While Medical and Dental Leads GrowthAutomotive accounted for 31.42% of the European metal precision turned product manufacturing market share in 2025. Germany, France, Italy, and Spain provide a broad base of vehicle manufacturers and component suppliers. The electric-vehicle transition changes the parts mix rather than removing the need for precision turning. Motor shafts, bus-bar inserts, and thermal-management fittings require controlled dimensions and reliable finishing. Industrial machinery and automation also consume turned components for gearboxes, actuators, and manufacturing cells. Electronics, hydraulics, energy equipment, rail, maritime equipment, and appliances provide further demand diversity. This mix prevents the supplier base from depending entirely on vehicle production. It also gives qualified workshops a reason to develop specialized processes that can serve multiple customer groups.
Medical and dental are forecast to grow at an 8.67% CAGR through 2031. Its demand is linked to demographic needs and the high degree of precision required for implants. Certified parts can be more resilient to raw-material pass-through pressure because customers prioritize a qualified component over commodity pricing. Aerospace and defense are also becoming more visible customers for European workshops with the right documentation. The Arve Valley cluster is broadening its customer base beyond automotive toward medical and defense work. This diversification can reduce reliance on any single end-user cycle and reward suppliers with sector-specific certifications.
By Technology:
Turn-Mill Integration Reduces Process RiskCNC turning accounted for 56.35% of the European metal precision turned product manufacturing market share in 2025. Its installed base supports a wide range of bar sizes and product geometries. Swiss machining occupies the ultra-precision end of the technology range for implants and connectors. Multi-spindle machining is used for high-volume components such as pins, sleeves, and fasteners. Manual turning remains concentrated in repair and small bespoke applications. Hybrid additive-subtractive systems remain in their early stages, primarily for aerospace repair and titanium work. Technology decisions are closely linked to the inspection burden placed on a finished component. A completed part with fewer transfers offers a clearer production record and fewer opportunities for dimensional variation.
Multi-axis turn-mill machining is forecast to grow at an 8.38% CAGR through 2031. One-setup production removes some of the quality risk associated with moving a part through several fixtures. It can also reduce lead times for medium-series production where a part requires numerous operations. Automation through bar feeders and robot loading can further support high-mix production. Programming complexity remains a constraint, which reinforces the need for trained multi-axis specialists.
By Production Scale:
High-Volume Production Supports Revenue GrowthHigh-volume production accounted for 46.28% of the European metal precision turned product manufacturing market share in 2025. Automotive suppliers in Germany, France, Italy, and Spain produce large runs of fasteners, bushings, shafts, and inserts. Medium-series work is important for aerospace, industrial, and medical customers where qualification costs must be spread across a meaningful number of parts. Small-batch production and prototypes remain important at the beginning of product-development programs. Digital quoting platforms have shortened the ordering process for some of these requirements. Xometry Europe expanded the maximum dimensions available for CNC machining to 1,200 mm. Production scale also shapes the level of automation that makes financial sense. Large, stable programs can justify dedicated equipment, while smaller programs need flexibility and rapid setup changes.
High-volume production is also forecast to grow at a 6.17% CAGR through 2031. Robotic tending, bar feeders, and in-line measurement allow selected cells to run with less direct labor across multiple shifts. This improves cost control for standardized components and strengthens the case for regional production. Eastern European additions are particularly relevant for standard-tolerance automotive work. Protolabs reported 25% year-over-year growth in CNC machining revenue in the fourth quarter of 2025, SEC.GOV. Digital manufacturing platforms can therefore complement rather than replace traditional high-volume suppliers by connecting qualified capacity with new orders.
Geography Analysis
Germany Metal Precision Turned Product Manufacturing Market
Germany held 25.36% of the European metal precision turned product manufacturing market share in 2025. Its position reflects the country’s automotive base and dense network of established machining companies. Electrification is reducing demand for some conventional powertrain components while creating demand for e-motor shafts, battery housings, and high-voltage connectors. Germany remains important for high-precision work despite cost pressure on more standardized production. The geographic pattern reflects a balance between established technical clusters and newer capacity centers. Buyers can use this spread to match demanding work with specialist suppliers and standardized work with competitive regional capacity. This keeps technical capability, supplier qualification, and operational responsiveness closely connected in purchasing decisions across the region.
Western Europe Metal Precision Turned Product Manufacturing Market
Switzerland and France remain major centers of precision turning in Europe. Switzerland’s Jura Arc has a dense concentration of companies serving automotive, aerospace, defense, and medical customers. France’s Arve Valley combines long experience in bar turning with a varied customer base. The United Kingdom continues to serve medical and aerospace customers that value specialized engineering capability. Shared aerospace and medical quality infrastructure helps Western European suppliers move between sectors as customer demand changes. This keeps technical capability, supplier qualification, and operational responsiveness closely connected in purchasing decisions across the region.
Central and Eastern Europe Metal Precision Turned Product Manufacturing Market
Poland is forecast to grow at a 7.28% CAGR through 2031, making it the fastest-growing country in the European metal precision turned parts market. Automotive and aerospace buyers are qualifying more Polish suppliers to shorten lead times and strengthen regional sourcing options. Workshops are investing in ISO 9001, ISO 3834, and EN 1090 certification to meet purchaser requirements. The Rzeszów investment by Collins Aerospace and Pratt & Whitney supports Poland’s titanium-machining profile. Czechia and Romania also support automotive and electronics production, especially as cost-sensitive work moves east. Hungary, Austria, Belgium, and the Netherlands retain smaller positions in specialized medical, electronics, and hydraulics work. This keeps technical capability, supplier qualification, and operational responsiveness closely connected in purchasing decisions across the region.
Competitive Landscape
The European metal precision turned parts market remains fragmented at the production level. Hundreds of small and medium-sized workshops operate across the Arve Valley, southern Germany, and the Jura Arc. Many are family-owned businesses with deep knowledge of specific parts, materials, and customer specifications. Digital platforms are beginning to change how orders are found and allocated, but they do not eliminate the need for physical production capability.
The market structure leaves room for both independent specialists and service platforms. Their roles differ because platforms improve visibility and coordination, while workshops remain responsible for actual process capability and finished-part quality. This keeps technical capability, supplier qualification, and operational responsiveness closely connected in purchasing decisions across the region.
Competition increasingly depends on the ability to demonstrate quality through data as well as through delivered parts. Buyers can value dimensional reports, material records, process timestamps, and machine data when they select a supplier. This creates an opportunity for workshops that pair precision machining with dependable digital documentation. The European metal precision turned parts industry can use these platforms to support sourcing, while specialist workshops retain control of the machining process. This keeps technical capability, supplier qualification, and operational responsiveness closely connected in purchasing decisions across the region.
Europe Metal Precision Turned Product Manufacturing Industry Leaders
-
VASCHUK ltd.
-
Bulmac Engineering Ltd.
-
ELIRI SA.
-
INDUSTRUM GROUPE
-
DMG MORI CO., LTD.
- *Disclaimer: Major Players sorted in no particular order
Europe Metal Precision Turned Product Manufacturing Market Companies Covered in this Report
- DMG MORI CO., LTD.
- Xometry Europe GmbH
- Protolabs, Inc.
- Grieshaber GmbH & Co. KG
- PREFAG Carl Rivoir GmbH & Co. KG
- Zannini S.p.A.
- Schuler Prazisionstechnik AG
- Decovi SA
- Neida Bartschi AG
- Benoit Jolivet SAS
- SABNER Sp. z o.o.
- Hardy's Precision Engineering Ltd
- Bulmac Engineering Ltd
- INDUSTRUM GROUPE
- VASCHUK LTD.
- ELIRI SA
- DANI 151 LTD
- UAB Kiruna
- Sargasas UAB
- GMO Precision Turned Parts GmbH
- J. E. Gerhardt GmbH
Read Analysis of Europe Metal Precision Turned Product Manufacturing Companies

Recent Industry Developments in Europe Metal Precision Turned Product Manufacturing Market
- June 2026: DMG MORI expanded its Stipshausen facility by 1,400 m? to support production, logistics, and R&D activities. The facility enables precision machining of hard, brittle materials and serves high-technology sectors, including medical and aerospace.
- November 2025: Xometry Europe increased the maximum CNC part dimension available through its Instant Quoting Engine from 1,000 mm to 1,200 mm across its UK and European operations, expanding access to larger industrial components.
- July 2025: Xometry launched Teamspace in Europe, the United Kingdom, and Turkey, enabling enterprise customers to collaborate on projects and custom part orders.


Europe Metal Precision Turned Product Manufacturing Market Report Scope
Precision-turned parts are those that have undergone exceptionally precise machining. The bulk of precision-turned parts is created using the straightforward yet crucial method of CNC turning.
The European metal precision-turned parts market is segmented by operation, machine type, product type, material, end user, technology, production scale, and country. By operation, the market is segmented into manual operation and CNC operation; by machine type, it is segmented into automatic screw machines, rotary transfer machines, CNC lathes and turning centers, and other machine types; by product type, it is segmented into screws and bolts, bushings and sleeves, shafts, pins, and axial components, threaded inserts and fastening components, hydraulic and pneumatic components, turned-milled complex components, medical and dental components, and other metal precision turned products; by material, it is segmented into steel and stainless steel, aluminum and aluminum alloys, brass and copper alloys, titanium and titanium alloys, nickel-based and high-temperature alloys, and engineering plastics and other materials; by end user, it is segmented into automotive, industrial machinery and automation, electronics and electrical engineering, medical and dental, aerospace and defense, hydraulics and pneumatics, energy and power equipment, rail, maritime, and transportation equipment, appliances and consumer products, and other end users; by technology, it is segmented into CNC turning, Swiss machining, multi-axis turn-mill machining, multi-spindle machining, manual turning, and hybrid additive-subtractive machining; by production scale, it is segmented into prototype and one-off production, small-batch production, medium-series production, and high-volume production; and by country, it is segmented into Germany, France, the United Kingdom, Italy, Spain, Switzerland, the Netherlands, Belgium, Austria, Poland, Czechia, Romania, Hungary, Russia, and the Rest of Europe.
The report offers the market sizes and forecasts for Europe's metal precision turned product manufacturing market in value (USD) for all the above segments.
| Manual Operation |
| CNC Operation |
| Automatic Screw Machines | |
| Rotary Transfer Machines | |
| CNC Lathes and Turning Centers | Horizontal Turning Centers |
| Vertical Turning Centers | |
| CNC Swiss-Type or Sliding-Headstock Lathes | |
| CNC Multi-Axis Turning Machines | |
| CNC Multi-Spindle Turning Machines | |
| Other Machine Types |
| Screws and Bolts |
| Bushings and Sleeves |
| Shafts, Pins, and Axial Components |
| Threaded Inserts and Fastening Components |
| Hydraulic and Pneumatic Components |
| Turned-Milled Complex Components |
| Medical and Dental Components |
| Other Metal Precision Turned Products |
| Steel and Stainless Steel |
| Aluminum and Aluminum Alloys |
| Brass and Copper Alloys |
| Titanium and Titanium Alloys |
| Nickel-Based and High-Temperature Alloys |
| Engineering Plastics and Other Materials |
| Automotive |
| Industrial Machinery and Automation |
| Electronics and Electrical Engineering |
| Medical and Dental |
| Aerospace and Defense |
| Hydraulics and Pneumatics |
| Energy and Power Equipment |
| Rail, Maritime, and Transportation Equipment |
| Appliances and Consumer Products |
| Other End Users |
| CNC Turning |
| Swiss Machining |
| Multi-Axis Turn-Mill Machining |
| Multi-Spindle Machining |
| Manual Turning |
| Hybrid Additive-Subtractive Machining |
| Prototype and One-Off Production |
| Small-Batch Production |
| Medium-Series Production |
| High-Volume Production |
| Germany |
| France |
| United Kingdom |
| Italy |
| Spain |
| Switzerland |
| Netherlands |
| Belgium |
| Austria |
| Poland |
| Czechia |
| Romania |
| Hungary |
| Russia |
| Rest of Europe |
| By Operation | Manual Operation | |
| CNC Operation | ||
| By Machine Type | Automatic Screw Machines | |
| Rotary Transfer Machines | ||
| CNC Lathes and Turning Centers | Horizontal Turning Centers | |
| Vertical Turning Centers | ||
| CNC Swiss-Type or Sliding-Headstock Lathes | ||
| CNC Multi-Axis Turning Machines | ||
| CNC Multi-Spindle Turning Machines | ||
| Other Machine Types | ||
| By Product Type | Screws and Bolts | |
| Bushings and Sleeves | ||
| Shafts, Pins, and Axial Components | ||
| Threaded Inserts and Fastening Components | ||
| Hydraulic and Pneumatic Components | ||
| Turned-Milled Complex Components | ||
| Medical and Dental Components | ||
| Other Metal Precision Turned Products | ||
| By Material | Steel and Stainless Steel | |
| Aluminum and Aluminum Alloys | ||
| Brass and Copper Alloys | ||
| Titanium and Titanium Alloys | ||
| Nickel-Based and High-Temperature Alloys | ||
| Engineering Plastics and Other Materials | ||
| By End User | Automotive | |
| Industrial Machinery and Automation | ||
| Electronics and Electrical Engineering | ||
| Medical and Dental | ||
| Aerospace and Defense | ||
| Hydraulics and Pneumatics | ||
| Energy and Power Equipment | ||
| Rail, Maritime, and Transportation Equipment | ||
| Appliances and Consumer Products | ||
| Other End Users | ||
| By Technology | CNC Turning | |
| Swiss Machining | ||
| Multi-Axis Turn-Mill Machining | ||
| Multi-Spindle Machining | ||
| Manual Turning | ||
| Hybrid Additive-Subtractive Machining | ||
| By Production Scale | Prototype and One-Off Production | |
| Small-Batch Production | ||
| Medium-Series Production | ||
| High-Volume Production | ||
| By Country | Germany | |
| France | ||
| United Kingdom | ||
| Italy | ||
| Spain | ||
| Switzerland | ||
| Netherlands | ||
| Belgium | ||
| Austria | ||
| Poland | ||
| Czechia | ||
| Romania | ||
| Hungary | ||
| Russia | ||
| Rest of Europe | ||


Key Questions Answered in the Report
What is the forecast for Europe metal precision turned parts market revenue?
Europe metal precision turned product manufacturing market revenue is projected to increase from USD 19.94 billion in 2026 to USD 25.52 billion by 2031, at a 5.11% CAGR through 2031.
Which operation holds the largest share in European precision turning?
CNC operation held a 82.37% share in 2025 and is forecast to grow at a 6.28% CAGR through 2031.
Which material is expected to grow fastest in European precision turning?
Titanium and titanium alloys are forecast to grow at a 9.16% CAGR through 2031, supported by medical and aerospace requirements.
Which end user creates the strongest growth opportunity for precision-turned parts?
Medical and dental is projected to grow at an 8.67% CAGR through 2031, driven by implant demand and strict qualification requirements.
Which country is growing fastest for precision-turned parts in Europe?
Poland is forecast to grow at a 7.28% CAGR through 2031 as regional automotive and aerospace sourcing expands.
Page last updated on:



