
Europe Non-Destructive Testing Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Historical Data Period | 2020 - 2024 |
| Market Size (2026) | USD 7.02 Billion |
| Market Size (2031) | USD 10.42 Billion |
| Growth Rate (2026 - 2031) | 8.22 % |
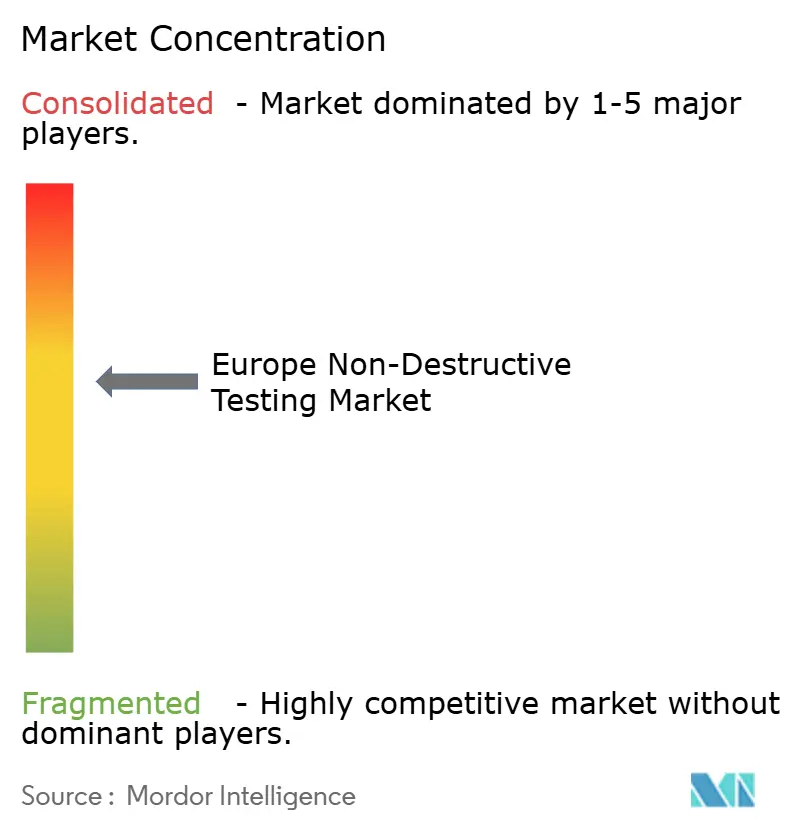
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Europe Non-Destructive Testing Market Analysis by 麻豆视频
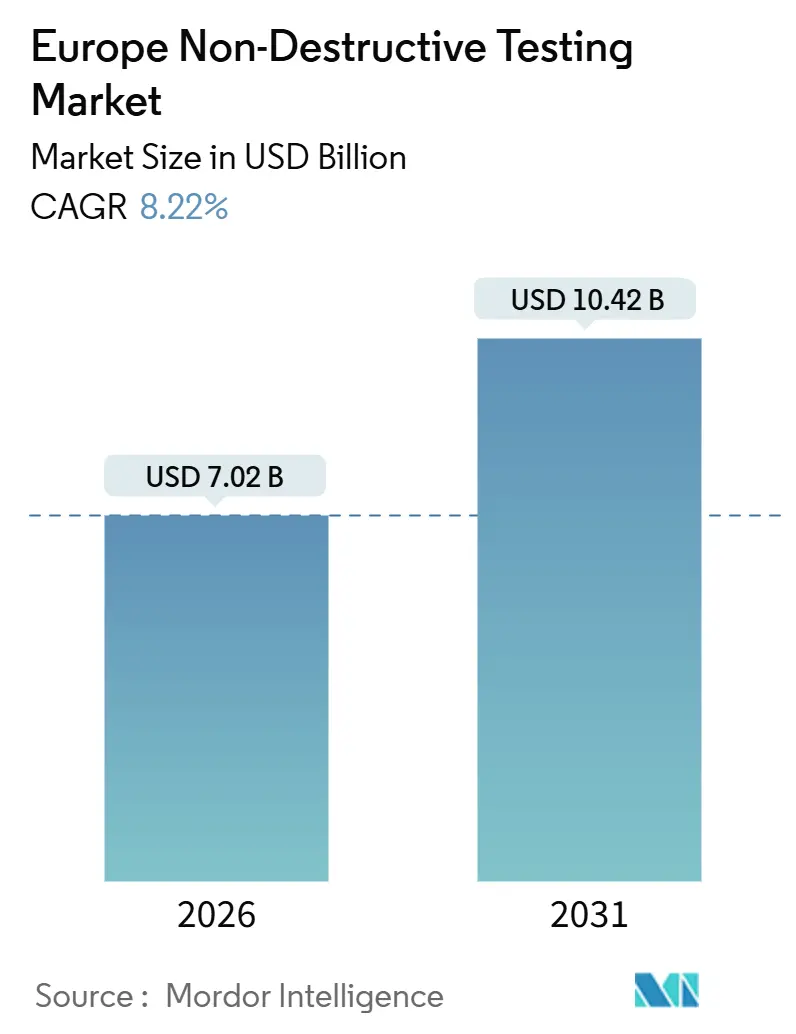
The Europe Non-Destructive Testing Market size is estimated at USD 7.02 billion in 2026, and is expected to reach USD 10.42 billion by 2031, at a CAGR of 8.22% during the forecast period (2026-2031).
Robust regulatory enforcement, heavy aerospace and defense maintenance activity, and life-extension programs for North Sea energy assets are sustaining inspection volumes while digitization pushes operators toward data-rich ultrasonic, radiographic, and eddy-current platforms. Outsourcing remains the dominant service model, yet rental arrangements and cloud analytics subscriptions are widening access to advanced technologies. German automotive electrification, United Kingdom nuclear new-builds, and additive-manufacturing part qualification are among the highest-growth demand pockets, encouraging vendors to bundle portable hardware with artificial-intelligence analytics for faster defect classification. Competitive intensity is moderate as five multinational service providers hold just under 40% share, but specialized equipment makers are expanding niches in phased-array ultrasonics and portable computed-tomography solutions, reshaping value capture along the inspection workflow.
Key Report Takeaways
- By testing method, ultrasonic techniques led with 30.11% of Europe Non-Destructive Testing market share in 2025, while emerging techniques are forecast to expand at an 8.92% CAGR through 2031.
- By component type, services held 49.57% share of the Europe Non-Destructive Testing market size in 2025, whereas software and analytics platforms are projected to grow at 9.14% CAGR to 2031.
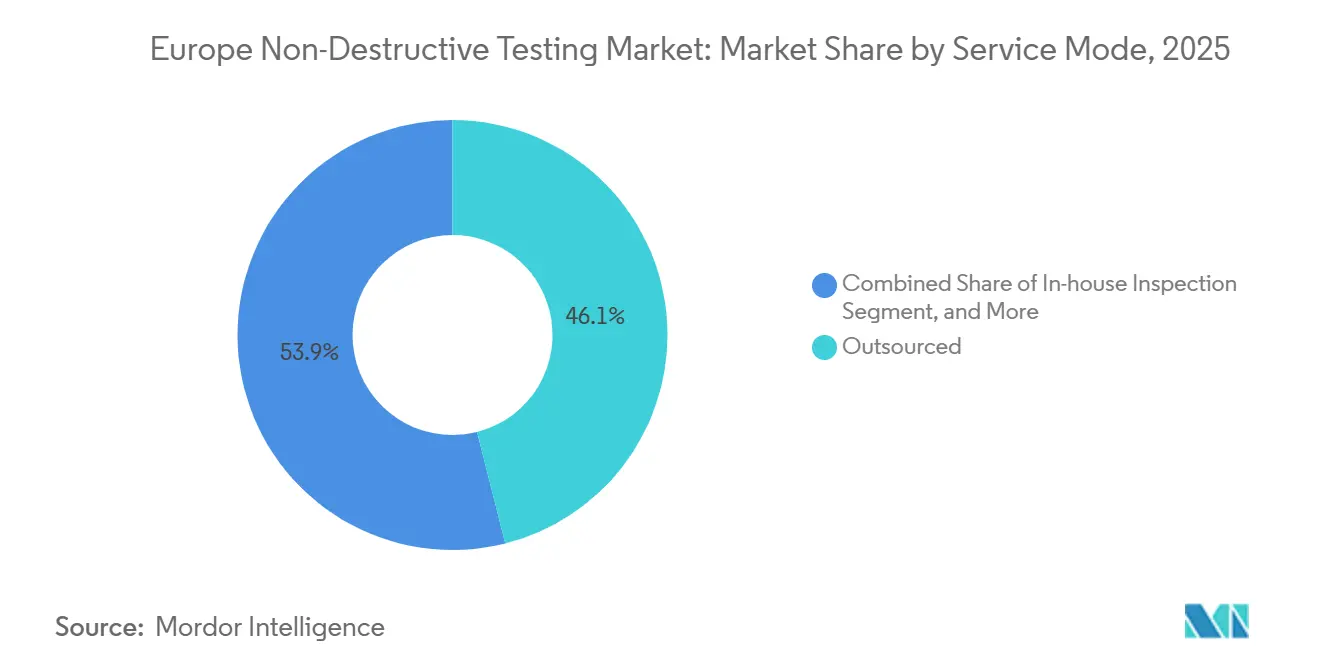
- By service mode, outsourced inspection captured 46.06% of Europe Non-Destructive Testing market size in 2025; rental and leasing are the fastest segment at an 8.52% CAGR.
- By end-user, oil and gas accounted for 23.92% share of the Europe Non-Destructive Testing market size in 2025, while industrial manufacturing is advancing at a 9.01% CAGR through 2031.
- By country, Germany commanded 23.88% share of the Europe Non-Destructive Testing market size in 2025, and the United Kingdom is poised for the quickest expansion at a 9.63% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Europe Non-Destructive Testing Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent EU Directives On Industrial Safety and Product Liability | +1.8% | Pan-European, with concentrated enforcement in Germany, France, United Kingdom | Medium term (2-4 years) |
| Rising Capital Expenditure In European Aerospace and Defence MRO Facilities | +1.5% | United Kingdom, France, Germany, with spill-over to Spain and Italy | Medium term (2-4 years) |
| Ageing Oil and Gas Assets In The North Sea Demanding Life-Extension Inspections | +1.3% | United Kingdom, Norway (North Sea basin), with indirect demand in Netherlands | Long term (≥ 4 years) |
| Mandatory Periodic Testing Of On-Road Commercial Vehicles Under EU Roadworthiness Package | +1.2% | Pan-European, with early adoption in Germany, France, Spain | Short term (≤ 2 years) |
| Surge In Additive-Manufacturing (AM) Part Qualification Requiring Novel NDT Protocols | +1.0% | Germany, United Kingdom, France (aerospace and industrial hubs) | Medium term (2-4 years) |
| Investments In Small Modular Nuclear Reactors (SMRs) Driving Advanced In-Service Inspection | +0.9% | United Kingdom, France, with exploratory projects in Czech Republic, Romania | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Stringent EU Directives on Industrial Safety and Product Liability
Revisions to the Pressure Equipment Directive, Machinery Regulation, and the Roadworthiness Package have widened the scope and tightened the cadence of mandatory inspections. Commercial vehicles older than 12 years now face annual structural checks, adding roughly 1.2 million inspections across Germany, France, and Spain each year.[1]European Commission, “Roadworthiness Testing and Technical Roadside Inspections,” ec.europa.eu Updated product-liability rules shift the burden of proof onto manufacturers, compelling the creation of auditable, non-destructive testing records in aerospace and medical-device production lines. As compliance becomes non-negotiable, Europe Non-Destructive Testing market demand remains insulated from macro-economic slowdowns and pricing pressure on legacy techniques.
Rising Capital Expenditure in European Aerospace and Defense MRO Facilities
Between 2024 and 2026, GE Aerospace, Safran, and other maintenance organizations committed more than USD 1.25 billion to expand ultrasonic and computed-tomography capacity, shortening engine overhaul cycles and enabling same-shift re-inspection of additive-manufactured parts. The spending wave aligns with Airbus forecasts indicating USD 130 billion in cumulative European MRO outlays to 2031, with NDT accounting for 8% of total costs.[2]Airbus, “Global MRO Forecast 2024-2031,” airbus.com High throughput facilities that integrate inspection data into enterprise asset-management systems now enjoy preferential contract terms, accelerating software adoption and pushing the Europe Non-Destructive Testing market toward predictive analytics.
Ageing Oil and Gas Assets in the North Sea Demanding Life-Extension Inspections
More than 60% of United Kingdom Continental Shelf platforms had served for 30 years or more in 2024, prompting intensified ultrasonic thickness surveys and intelligent-pigging campaigns under revised safety-case regulations. Operators have extended decommissioning timelines by up to 15 years, particularly where carbon-capture retrofits are viable, anchoring long-run inspection workloads. Updated pipeline guidelines from the Energy Institute recommend dual techniques - inline pigs plus external corrosion mapping - shifting spending toward remotely operated vehicle-mounted phased-array probes.
Mandatory Periodic Testing of On-Road Commercial Vehicles under EU Roadworthiness Package
Directive 2014/45/EU has evolved from spot visual checks to compulsory ultrasonic or magnetic-particle examinations of brake systems and chassis components. Germany, France, and Spain adopted the tighter schedules first, raising aggregate annual inspection volume and heightening demand for portable flaw detectors that can deliver pass-or-fail decisions within minutes at roadside stations.
Restraints Impact Analysis*
| Restraint | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Persistent Shortage Of Level-III Certified NDT Personnel | -1.1% | Pan-European, acute in United Kingdom, Germany, France | Short term (≤ 2 years) |
| High Ownership Cost Of Phased-Array Ultrasonic and DR Systems For SMEs | -0.8% | Spain, Italy, Eastern European member states | Medium term (2-4 years) |
| Fragmented EU Standards Harmonisation Delaying Cross-Border Acceptance Of Results | -0.6% | Pan-European, with friction at Germany-Poland, France-Belgium borders | Medium term (2-4 years) |
| Limited Field-Use Robustness Of Emerging Terahertz NDT Solutions | -0.3% | Research-intensive regions: Germany, United Kingdom, France | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Persistent Shortage of Level-III Certified NDT Personnel
Pan-European demand for Level-III ultrasonic and radiographic specialists outstrips supply by 15%, pushing day rates near USD 870 and delaying complex weld inspections.[3]British Institute of Non-Destructive Testing, “NDT Personnel Shortage Report 2024,” bindt.org The five-year experiential requirement embedded in ISO 9712 prolongs the talent gap, while competition from the nuclear sector intensifies scarcity. Automation mitigates routine tasks, but regulatory frameworks still mandate human sign-off, constraining throughput and nudging Europe Non-Destructive Testing market participants to invest in internal academies.
High Ownership Cost of Phased-Array Ultrasonic and Digital Radiography Systems for SMEs
Portable phased-array units start at USD 130,000 and require annual maintenance equaling up to 12% of purchase value. For small firms generating less than EUR 2 million in test revenue, capital intensity is prohibitive, forcing reliance on dated film radiography or subcontracting. Rental programs are expanding, yet the lack of favorable financing in Southern and Eastern Europe sustains a technology gap and caps the addressable base for high-margin software upgrades.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Testing Method: Ultrasonic Techniques Retain a One-Third Hold
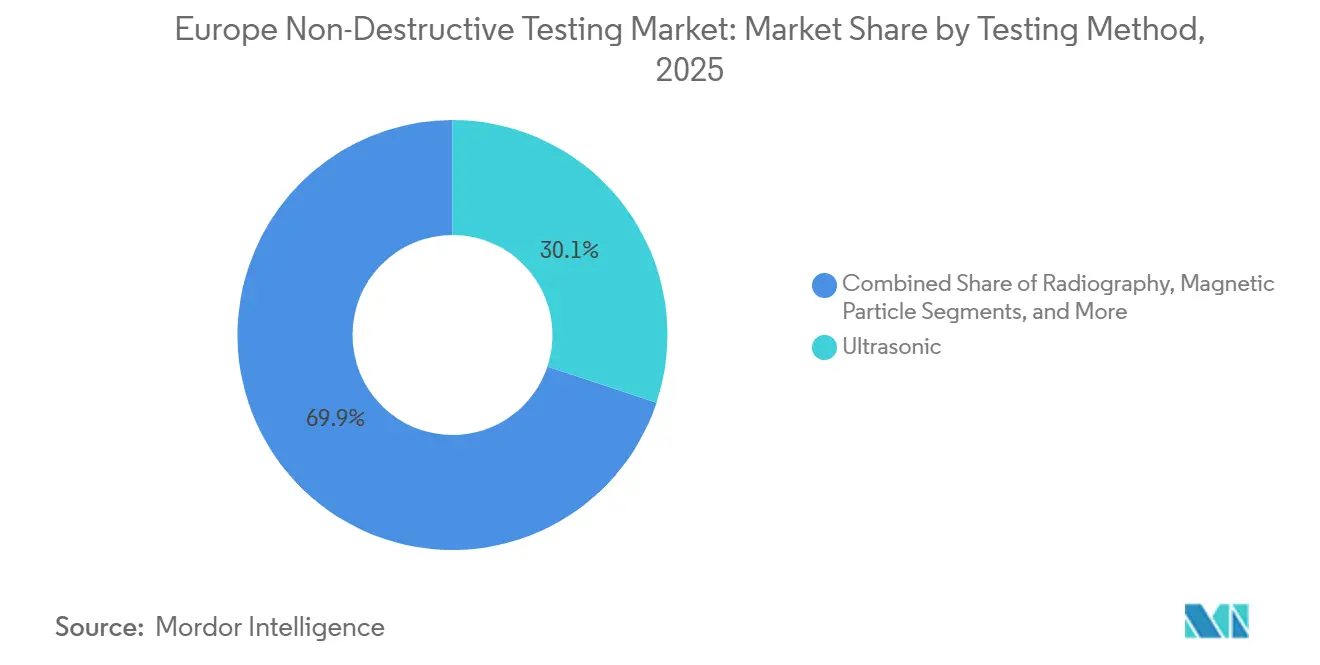
Ultrasonic solutions accounted for 30.11% of Europe Non-Destructive Testing market share in 2025, favored for detecting subsurface flaws in thick welds, composites, and aged pipeline walls. Large aerospace shops now scan turbine disks in 12 minutes using 128-element phased-array heads, down from 45 minutes with legacy pulse-echo probes.[4]Safran, “Phased-Array Ultrasonic Efficiency Gains,” safran-group.com Radiography remains indispensable for nuclear welds and additive-manufactured parts, while computed tomography is gaining traction to meet EASA Part 21 volumetric mandates. Emerging techniques - terahertz imaging, laser ultrasonics, and AI-assisted thermography - are forecast at an 8.92% CAGR, making them the fastest slice of the Europe Non-Destructive Testing market.
Increasingly, inspection protocols combine modalities. A single wind-turbine tower campaign might deploy drone-based visual surveys, ultrasonic spot checks, and eddy-current arrays for bolt-thread inspections. Vendors able to integrate data from these sources into unified dashboards stand to capture the expanding software layer of the Europe Non-Destructive Testing market.


By Component Type: Services Still Dominate but Software Grabs Margins
Services delivered 49.57% of 2025 revenue as asset owners continued to outsource compliance and liability to accredited providers. Bureau Veritas alone logged USD 1.3 billion in European NDT services during 2024. However, software and analytics platforms are rising at 9.14% CAGR, even as the broader Europe Non-Destructive Testing market advances at 8.22%. Instruments such as Evident’s OmniScan X4 ship with embedded neural networks that classify weld flaws with 92% accuracy, reducing Level-III sign-off time. Gross margins on subscription analytics hover near 70%, double those of labor-intensive services, incentivizing incumbent service giants to acquire niche software firms.
When software is bundled with rental hardware- an approach championed by Zetec and Olympus- customers sidestep upfront capital, while vendors lock in recurring revenue. This inversion of the traditional equipment-sale model is reshaping the profit pool within the Europe Non-Destructive Testing market.
By Service Mode: Outsourcing Remains the Anchor While Rental Gains Momentum
Outsourced inspection services commanded 46.06% of Europe Non-Destructive Testing market share in 2025 as asset owners continued to shift liability for regulatory compliance toward accredited third parties, a strategy that lets operators focus scarce capital and internal talent on core production targets. Multinational providers have reinforced this preference by embedding indemnity clauses and performance dashboards into framework contracts, providing customers with transparent defect-detection metrics across multiple facilities. In-house inspection models persist inside large aerospace and petrochemical groups, yet even these vertically integrated players increasingly subcontract peak-load work to avoid idle equipment during maintenance lulls. Outsourced specialists also leverage dense regional office footprints that cut mobilization costs for offshore campaigns and bridge rehabilitation projects, an advantage unattainable for single-site in-house teams. This structural edge stabilizes pricing power and underpins the services slice of the Europe Non-Destructive Testing market size through the forecast horizon.
Rental and leasing programs are the fastest growing service mode, expanding at an 8.52% CAGR to 2031 as small and medium enterprises in Spain, Italy, and Eastern Europe sidestep six-figure equipment investments and pay weekly or monthly fees instead. Olympus, Zetec, and T?V Rheinland now bundle rental hardware with cloud analytics subscriptions, transforming one-off equipment hires into recurring revenue streams while giving users access to the newest phased-array and digital-radiography platforms without ownership risk. The model is particularly attractive for episodic projects such as offshore platform decommissioning or high-speed rail weld surveys, where utilization drops sharply after completion. As more suppliers copy this hybrid approach, rental penetration is expected to lift the recurring-revenue mix within the Europe Non-Destructive Testing market size and reduce technology gaps between tier-one contractors and regional specialists.
By End-User Industry: Energy Assets Underpin Demand While Manufacturing Accelerates
Oil and gas applications retained 23.92% of Europe Non-Destructive Testing market share in 2025, buoyed by North Sea life-extension campaigns that mandate ultrasonic wall-thickness checks and intelligent-pig runs every five to seven years to satisfy updated safety-case rules. Subsea pipeline operators are layering external phased-array corrosion mapping onto inline data to refine corrosion-growth models, increasing the inspection spend per kilometer of pipe. Refinery turnarounds reinforce baseline volumes by requiring radiographic weld examinations and ultrasonic nozzle scans each maintenance cycle, even when crude prices soften. This entrenched workload gives service providers predictable revenue and justifies offshore logistics hubs in Aberdeen, Stavanger, and Rotterdam, locking in a resilient core for the Europe Non-Destructive Testing market size.
Industrial manufacturing is projected to grow at a 9.01% CAGR as additive-manufacturing part qualification, electric-vehicle battery-weld integrity, and Industry 4.0 traceability mandates embed non-destructive testing directly on production lines. Automotive plants in Germany now run inline phased-array checks on every battery-pack enclosure, in response to stricter fire-safety scrutiny following several high-profile incidents in 2024. Aerospace suppliers must document computed-tomography scans of powder-bed fusion parts to meet EASA Part 21 requirements, pushing inspection demand beyond traditional MRO cycles into day-to-day fabrication. Together with steady contributions from power generation, transportation, and infrastructure rehabilitation, these drivers diversify revenue streams and lessen reliance on the cyclical oil and gas segment within the broader Europe Non-Destructive Testing market.
Geography Analysis
Germany held 23.88% of the Europe Non-Destructive Testing market size in 2025, underpinned by battery-pack weld inspection across Bavarian and Baden-Württemberg automotive plants and stringent T?V requirements that embed third-party testing in machinery certification. Fraunhofer’s laser-ultrasonic breakthroughs lifted scan speeds tenfold, positioning domestic vendors for export opportunities.
The United Kingdom is forecast to grow at a 9.63% CAGR through 2031 on the back of Rolls-Royce small modular reactor investments and 5 GW of offshore wind projects that rely on remotely operated vehicle-mounted phased-array probes. Nuclear Advanced Manufacturing Research Centre partnerships are fastening laser-ultrasonic protocols onto compact reactor vessels, carving out a high-margin niche.
France’s 56-reactor nuclear fleet enforces a drumbeat of pressure-vessel and steam-generator tube inspections, anchoring demand for eddy-current and ultrasonic techniques. Safran’s EUR 1 billion MRO upgrade consolidates computed-tomography capacity in Toulouse and Villaroche, accelerating turnaround times for composite fan blades.
Italy and Spain see episodic spikes tied to bridge rehabilitation and high-speed rail expansion, yet smaller industrial footprints temper sustained growth. Poland, Czech Republic, and Romania offer lower labor costs and ISO 17020 accreditation, attracting cross-border contracts but also dispersing qualified personnel, which intensifies the already acute Level-III shortage across the Europe Non-Destructive Testing market.
Regulatory Landscape
Europe non-destructive testing (NDT) activities are governed by a mix of EU safety directives and harmonized technical standards that shape mandatory inspection frequency, documentation, and competence requirements. The Pressure Equipment Directive (2014/68/EU), the Machinery Regulation transition, and the Roadworthiness Package for commercial vehicles collectively reinforce periodic checks and auditable test records across member states.
On the standards side, CEN/TC 138 steers European NDT standardization, and when ISO documents are adopted as EN ISO, member states must withdraw conflicting national standards, which reduces cross-border protocol divergence. Personnel qualification continues to center on EN ISO 9712:2022, while method-specific updates continue to refresh equipment and verification requirements, including the release of BS EN ISO 15548-1:2026 for eddy-current examination equipment characteristics and verification. Standardization work visible in 2026 within CEN/TC 138 working groups also includes revisions around active thermography (EN 17119), which influences how emerging techniques are qualified and accepted in regulated inspections.
Value Chain Analysis
The Europe NDT value chain starts with sensor, detector, probe, and source components, including ultrasonic transducers and phased-array modules, digital radiography detectors and X-ray sources, eddy-current probes, robotics, and embedded compute. OEM integration then spans inspection systems and software layers for data capture, defect classification, and traceability, while distribution runs through direct OEM sales, specialist distributors, and rental and leasing channels that broaden access to high-cost PAUT and digital radiography systems for SMEs.
Downstream, accredited service providers deliver outsourced inspections, often bundling equipment, certified operators, procedure qualification, and reporting. Demand is anchored by regulated end users across energy, aerospace and defense MRO, manufacturing, and infrastructure. Value capture is shifting toward NDE 4.0 workflows that connect instruments to cloud analytics and asset-management systems, expanding the role of data platforms, cybersecurity controls, and interoperability. Policy-driven requirements around data access and system security in the EU, including the EU Data Act, AI Act, and Cyber Resilience Act, affect how equipment makers and software vendors design connected products and manage customer access to inspection data, pushing proprietary formats and encouraging managed-service offerings that include software subscriptions and training. Industry consolidation is also reshaping the chain as service groups and technology providers acquire niche capability to secure qualified labor, customer access, and specialized methods, including ININ Group expanding its Nordic inspection footprint into Finland in June 2025 and Bureau Veritas acquiring UK-based Advanced Inspection Technologies in November 2024.
Competitive Landscape
Multinational service houses- Bureau Veritas, Intertek, SGS, Applus, and T?V Nord- collectively hold just under 40% share, translating to a moderate concentration score. Their edge rests on multi-country accreditation, site density that reduces mobilization costs, and proprietary digital platforms that integrate ultrasonic, radiographic, and eddy-current data. Equipment specialists such as Eddyfi Technologies are vertically integrating through acquisitions, including Magnifi, to merge phased-array and eddy-current portfolios.
Smaller innovators exploit white spaces. Sonatest’s 1.8 kg handheld phased-array device reaches confined spots in offshore rigs, while NOVO DR’s lightweight digital panels fit wing-box inspections where standard detectors cannot. The Europe Non-Destructive Testing market thus balances scale players with agile specialists, and differentiation is shifting from hardware features to software-driven, real-time defect analytics.
Europe Non-Destructive Testing Industry Leaders
Baker Hughes Company
Bureau Veritas SA
Applus Servicios Tecnológicos S.L.U.
Intertek Group plc
Olympus Corporation
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A key opportunity area is expanding digital and automated inspection workflows that reduce Level-III bottlenecks while improving traceability for regulated assets, especially as inspections move from periodic campaigns to data-rich, system-integrated programs. Recent market activity supports this direction: the NDE Value Alliance was launched at ECNDT 2026 to address NDE 4.0 data sovereignty and interoperability and to tackle friction in multi-vendor inspection stacks where data formats and liability concerns slow enterprise-scale deployment.
Another whitespace is sector-specific capability buildout in automotive, aerospace structures, and welding inspection, with momentum coming from consolidation and targeted investment rather than incremental tool upgrades. ScanMaster Systems Group acquired VOGT Ultrasonics GmbH in February 2026 to strengthen robotic spot-weld and AI-driven ultrasonic inspection, aligning with high-volume manufacturing requirements. In services, CDL Group completed the acquisition of Ultraflux NDT in June 2026 to expand UK welding inspection and certification capacity, and Testia secured an Airbus Helicopters inspection services contract in June 2026 covering operations across France, Germany, and Spain. Together, these actions reinforce demand for advanced NDT on composite structures and create pull-through for portable ultrasonic platforms and analytics-enabled reporting.
Recent Industry Developments
- April 2026: Hexagon signed a definitive agreement to acquire Waygate Technologies from Baker Hughes for about USD 1.45 billion. The deal places a major NDT equipment portfolio under a metrology and digital-reality player, tightening links between inspection hardware, software, and industrial data workflows across Europe.
- February 2026: Eddyfi Technologies announced a definitive agreement to join ESAB. The combination consolidates advanced NDT technologies and strengthens the buyer's position in equipment-led NDT offerings that increasingly bundle software and automated defect analysis.
- July 2024: SPIE signed an agreement to acquire French NDT companies ABC, ETC, and SIRAC (GIE HORUS), adding nuclear-focused inspection capabilities. The acquisition expands service density in France's regulated power value chain, where recurring outage and in-service inspection requirements support long-duration demand for certified NDT services.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers revenues earned in Europe from non-destructive testing used to inspect materials, parts, and assets without damaging them, spanning equipment, related software, and delivered services, and applying across key industrial end users where safety and integrity checks are routine.
Scope exclusions: We exclude destructive testing, lab-only material characterization performed outside NDT workflows, and general maintenance work that does not include an NDT inspection step.
Segmentation Overview
- By Testing Method
- Radiography (Film, Digital, CT)
- Ultrasonic (Conventional, PAUT, TOFD)
- Magnetic Particle
- Liquid Penetrant
- Visual and Remote Visual
- Electromagnetic and Eddy- Current
- Emerging Techniques
- By Component Type
- Equipment
- Software and Analytics Platforms
- Services
- By Service Mode
- In-house Inspection
- Outsourced/Third-Party Inspection
- Rental and Leasing
- By End-User Industry
- Oil and Gas
- Aerospace and Defense
- Automotive and Transportation
- Power Generation
- Industrial Manufacturing
- Construction and Infrastructure
- Other End-User Industries
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Other Countries
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts with public data that helps map where inspection demand comes from across Europe and how it tends to move by sector. We refer to sources such as Eurostat industrial production and construction series, European Union Aviation Safety Agency publications, the European Pipeline Research Group materials, and national regulators that publish pressure equipment or industrial safety guidance.
We also review annual reports and investor presentations of listed inspection and industrial services groups, plus trade press and association websites that discuss testing practices and certification norms. To complete the inputs, our analysts use paid subscriptions for company financials, patents, and shipment level import and export checks when a specific equipment category needs a sanity check. The sources listed here are illustrative, and we draw on other public references to collect inputs, validate assumptions, and clarify gaps.
Primary Interviews and Surveys
Primary work focused on interviews and structured surveys with NDT service providers, OEM and distributor side participants, asset owners, and quality and maintenance teams in industries such as oil and gas, aerospace, automotive, power, and industrial manufacturing. Since we are sizing Europe as a whole, inputs were cross-checked across major countries and the rest of Europe to confirm adoption patterns by method and the typical split between in-house work and outsourced inspections.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 31% | CXOs: 12% |
| Mid tier: 55% | Functional/Unit leaders: 38% |
| Smaller Players: 14% | Managers: 50% |
Market-Sizing & Forecasting
Sizing starts from a top-down build where Europe demand is reconstructed by end-user activity and inspection intensity, then split across common NDT methods and delivery modes. In practice, we anchor the demand pool to indicators like industrial production output, installed base of safety-critical assets (for example, pressure equipment and rotating machinery), aircraft and MRO activity, and construction and infrastructure upkeep. These inputs are then translated into inspection frequency and average spend.
Those totals are corroborated through selective bottom-up checks, such as supplier and service-provider revenue sampling, channel feedback on equipment shipments, and volume times ASP approximations for key instruments and consumables where data is available. For forecasting, we run scenario analysis so the model can reflect different paths for energy investment cycles, aerospace build rates, plant maintenance schedules, and the pace of digital inspection adoption, including software and analytics attach rates. Where company reporting does not break out Europe or NDT cleanly, gaps are handled through allocation keys based on geographic mix, end-market exposure, and the method mix shared during interviews, then adjusted to remain consistent with the demand-side indicators.
Data Validation & Update Cycle
Model outputs are checked against multiple independent signals, such as country-level industrial momentum, major capex and turnaround cycles, and method-level adoption feedback from field calls, before the final number is signed off. Variances are flagged when growth or method shares move outside what respondents describe as feasible, and assumptions are revisited. A second pass review by another analyst follows after the updates.
The report is refreshed annually, and interim updates are triggered when material changes affect demand visibility, such as sharp shifts in energy projects, aerospace output, or new inspection requirements. Right before delivery, we review recent public releases again and recalibrate any inputs that have clearly moved, so clients receive the latest consistent view.
麻豆视频's Europe Non Destructive Testing Market Size Compared Against Other Published Estimates
Published market sizes for Europe NDT can differ because the boundary is not always set the same way, and the same label may include different revenue streams. Differences also come from how firms treat equipment versus services, whether software and analytics are counted, and how country coverage is grouped within Europe.
The table shows a spread that is mainly explained by scope and what gets counted as NDT revenue. In 麻豆视频's model, the total includes equipment, software and analytics platforms, and delivered services, and it is segmented across methods and service modes rather than using only a services-only view or an equipment-only proxy.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 7.02 B (2026) | |
| Trade Journal A | USD 6.11 B (2026) | Often reported as services and outsourcing revenues only, which can exclude equipment sales and software platforms, and it may apply a single Europe-wide utilization assumption without method-level splits. |
| Regional Consultancy B | USD 8.35 B (2026) | May bundle adjacent inspection and certification activities into NDT, and it can use aggressive ASP progression for digital tools without matching it to method adoption and country-level industrial activity. |
Across the three figures, the main takeaway is that the highest and lowest numbers usually come from counting different things, not from a true disagreement on inspection demand. By tying the model to observable industrial activity and then cross-checking with provider-side inputs, we keep the result traceable to clear variables that a reader can follow and replicate.


Key Questions Answered in the Report
How large is the Europe Non-Destructive Testing market in 2026?
The market reached USD 7.02 billion in 2026 and is forecast to rise to USD 10.42 billion by 2031 at an 8.22% CAGR.
Which testing method commands the biggest share?
Ultrasonic techniques held 30.11% of 2025 revenue, thanks to their versatility in aerospace, pipeline, and composite inspections.
What end-user sector is growing fastest?
Industrial manufacturing is expanding at a 9.01% CAGR as additive-manufacturing part qualification and battery-pack weld testing accelerate demand.
Why is the United Kingdom the fastest-growing country market?
Nuclear new-build projects, offshore wind foundation monitoring, and Rolls-Royce small modular reactor manufacturing drive a 9.63% CAGR through 2031.
How are vendors addressing the Level-III inspector shortage?
Service providers are investing in internal academies and deploying AI-enabled instruments that automate defect classification, reducing reliance on scarce experts.
Page last updated on:



