
EV Charging Cable Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 1.99 Billion |
| Market Size (2031) | USD 4.28 Billion |
| Growth Rate (2026 - 2031) | 16.51 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | Asia Pacific |
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? Â鶹ÊÓƵ. Reuse requires attribution under CC BY 4.0. |
|
EV Charging Cable Market Analysis by Â鶹ÊÓƵ
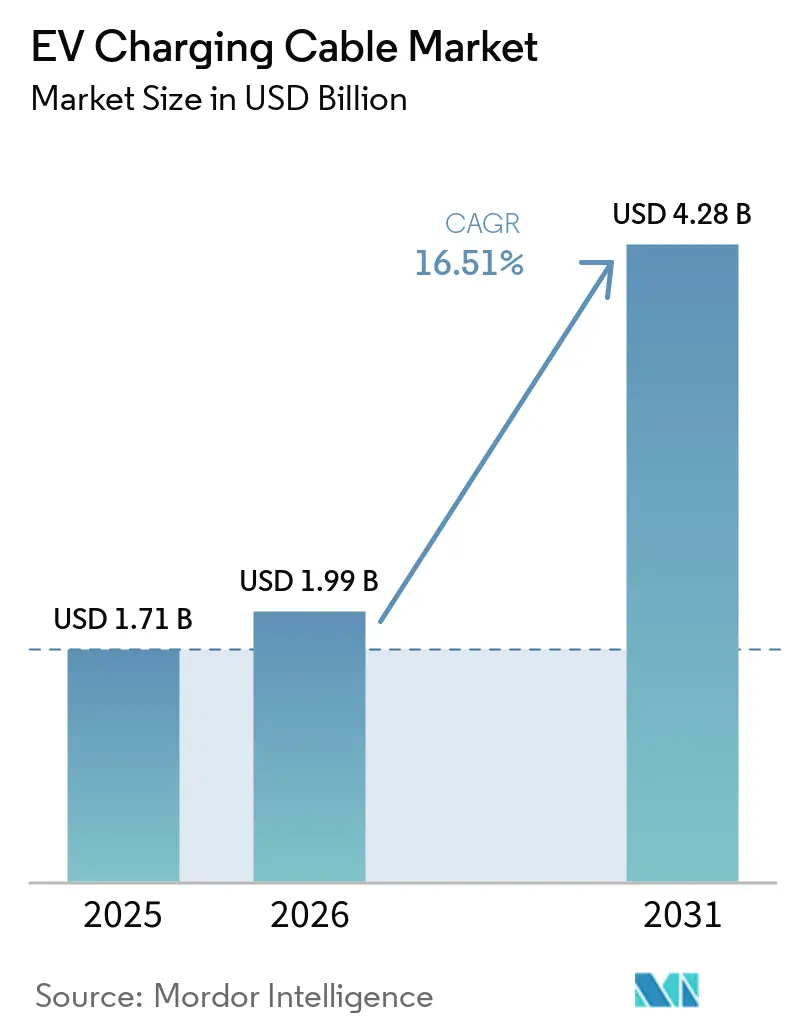
The EV charging cable market size was valued at USD 1.71 billion in 2025, is estimated at USD 1.99 billion in 2026, and is projected to reach USD 4.28 billion by 2031, growing at a CAGR of 16.51% over 2026-2031. A significant portion of new public fast-charger ports installed globally now adheres to unified connector standards, primarily the North American Charging Standard (NACS) and CCS Type 2. Suppliers that focus their production on these dominant interfaces have achieved notable unit cost reductions as annual volumes reach substantial levels. The Asia-Pacific region, led by China's GB/T and CCS2 dual-compatibility mandate, continues to serve as both the revenue driver and the technological leader. At the same time, the development of megawatt-class truck charging has introduced a new category of liquid-cooled cables capable of handling high continuous currents. However, the industry faces immediate challenges, including fluctuations in copper and elastomer prices and stricter grid-harmonics regulations in major cities, which could slightly impact the expected growth rate.
Key Report Takeaways
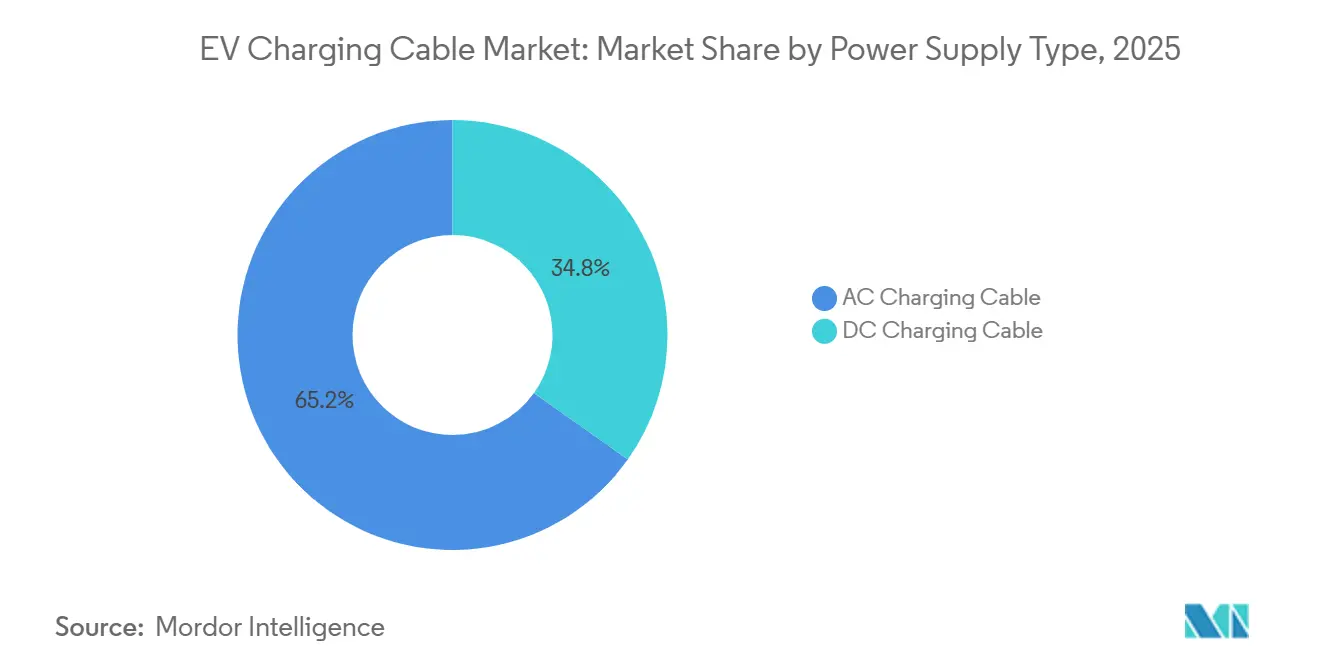
- By power-supply type, AC assemblies commanded 65.16% of the Electric Vehicle Charging Cable market share in 2025, while DC lines are projected to grow the fastest, at a 16.98% CAGR, through 2031.
- By cable length, products below 5 m led with 45.73% of 2025 revenue, while cables longer than 10 m are forecast to expand at a 16.85% CAGR through 2031.
- By charging level, Level 2 units accounted for 52.19% of the 2025 Electric Vehicle Charging Cable market. In contrast, Level 3 DC fast charging is projected to grow at a 16.72% CAGR over the forecast period.
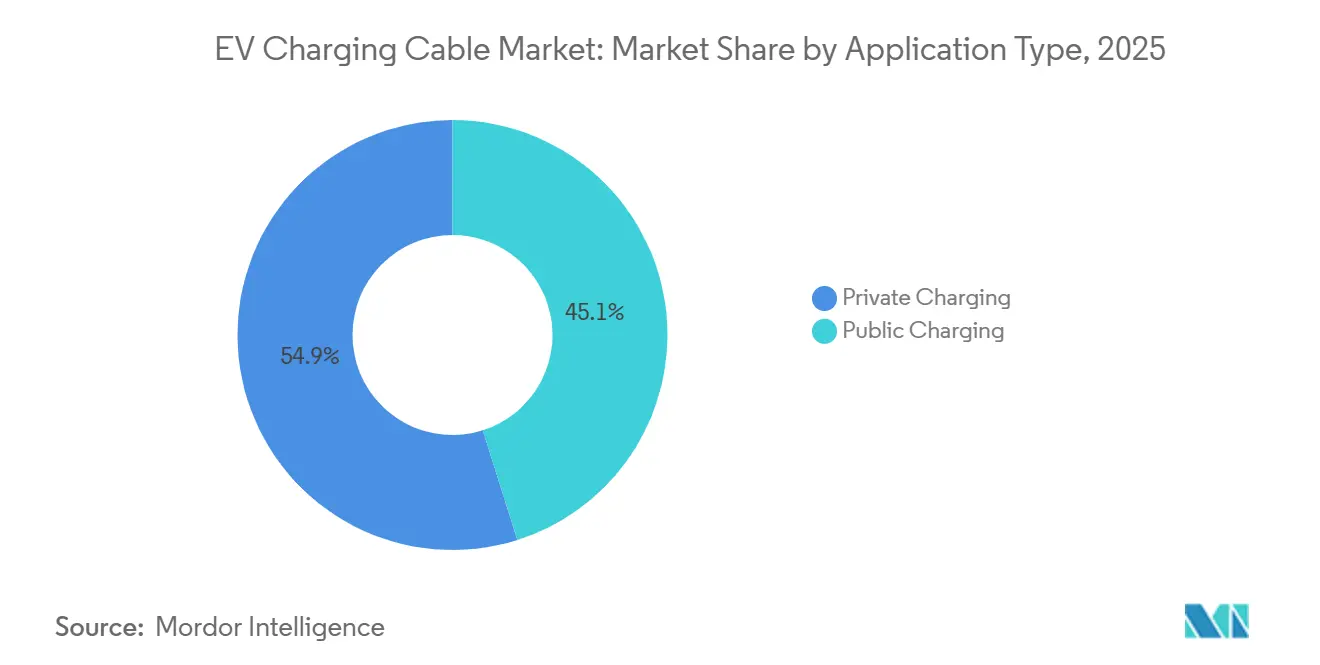
- By application, private installations accounted for 54.89% of 2025 revenue, yet public charging is expected to record the fastest 16.66% CAGR to 2031.
- By connector, Type 2 dominated with 42.22% share in 2025, while NACS is the fastest-growing format at a 16.83% CAGR and already leads new North American fast-charger ports.
- By geography, Asia-Pacific held the largest 47.41% revenue share in 2025 and is also poised for the strongest regional growth at a 16.94% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Â鶹ÊÓƵ¡¯s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Global EV Charging Cable Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Liquid-Cooled High-Amp Cables: Lower Costs, Longer Life | +3.2% | North America and EU, expanding to Asia Pacific | Long term (¡Ý 4 years) |
| Public DC Fast-Charging Corridors: Faster Rollout | +2.8% | Global, with NEVI program leadership in North America | Medium term (2-4 years) |
| Global Shift: CCS and NACS Standards | +2.1% | Global, with NACS adoption concentrated in North America | Short term (¡Ü 2 years) |
| Megawatt Charging: Emerging Trend | +1.9% | North America and EU core, early pilots in China | Medium term (2-4 years) |
| Fleet Models: "Cable-as-a-Service" | +1.8% | Global, with early adoption in fleet-dense markets | Medium term (2-4 years) |
| Recycled Cu/Al Alloys: Mitigating Risks | +1.5% | Global, with regulatory drivers in EU and China | Long term (¡Ý 4 years) |
| Source: Â鶹ÊÓƵ | |||
Falling Cost and Longer Life of Liquid-Cooled High-Amp Cables
Unit prices for liquid-cooled assemblies decreased significantly as Phoenix Contact, Huber+Suhner, and others achieved large-scale production. Phoenix Contact¡¯s cable now offers an extended lifespan, making it more usable than air-cooled counterparts [1]¡°High Power Charging portfolio,¡±, Phoenix Contact, phoenixcontact.com. Huber+Suhner integrates PT1000 sensors into its RADOX HPC500 plug, enabling real-time thermal management to prevent overheating. ChargePoint employs a similar liquid-cooling system to maintain high-power delivery to battery packs, substantially reducing charging times. New IEC test cycles now subject cables to elevated current levels for prolonged periods, a challenge that liquid-cooled products meet without requiring oversized conductors.
Accelerated Rollout of Public DC Fast-Charging Corridors
The United States added 18,000 DC fast-charge ports in 2025, a 30% lift driven by USD 5 billion of National Electric Vehicle Infrastructure (NEVI) funding. California alone installed more than 1,200 stations, while Texas and Florida added 850 and 720, respectively, creating coast-to-coast highway coverage. Europe¡¯s Alternative Fuels Infrastructure Facility earmarked EUR 600 million to build 3,000 DC chargers along priority freight corridors by 2027 [2]"EU awards over €600 million", European Commission, ec.europa.eu. Tesla opened 6,786 additional Supercharger ports in 2025 and began welcoming non-Tesla cars that use CCS1 adapters, monetizing idle capacity. EVgo secured a USD 1.25 billion federal loan to deploy about 7,500 fast chargers across 1,100 grocery-anchored sites, tightening its urban-core footprint. Corridor projects are standardizing on 5-10 meter cable lengths for highway bays, whereas curbside sites opt for sub-5 meter lines to curb vandalism.
Global Convergence Toward CCS and NACS Connector Standards
NACS has captured a significant share of North America's DC ports, overtaking CCS1 and CHAdeMO. Major automakers, including Ford, GM, Volkswagen, Toyota, and Stellantis, have transitioned to NACS inlet hardware for their latest models. SAE J3400, a pivotal standard, eliminated licensing fees and enabled all suppliers to manufacture NACS, thereby reducing cable costs. Meanwhile, Europe, under the Alternative Fuels Infrastructure Regulation, firmly supports CCS2 for chargers exceeding a specific power threshold. Suppliers, previously catering to multiple connector families, are now streamlining to two connector families, effectively reducing lead times for bulk orders.
Emergence of Megawatt Charging for HD Trucks
Scania unveiled a solution enabling heavy trucks to achieve a significant charge in under an hour. ABB's prototype, offering higher power and current, is already undergoing pilot tests in Europe. CharIN's Megawatt Charging System standardization advocates for cables with specific conductor dimensions and a defined coolant flow. Volvo is testing Al-Cu clad conductors, which reduce cable mass while maintaining most of pure copper's conductivity. Given the variability in depot layouts, the industry tends toward longer cables or pantograph overhead dispensers to trim time per plug-in cycle.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Copper and Elastomer Volatility | -1.2% | Global, with particular impact on price-sensitive markets | Short term (¡Ü 2 years) |
| Grid-Harmonics Limit Cable Current | -0.9% | Urban centers in North America and EU, expanding to Asia Pacific | Medium term (2-4 years) |
| Safety Recalls from Thermal-Runaway | -0.8% | Global, with stricter enforcement in developed markets | Medium term (2-4 years) |
| OEMs Shift to Wireless Charging | -0.7% | Premium vehicle segments globally, pilot programs in developed markets | Long term (¡Ý 4 years) |
| Source: Â鶹ÊÓƵ | |||
Copper and Elastomer Price Volatility
Copper prices surged to record levels, driven by mine disruptions in Chile and Peru. This significantly increased costs and cut gross margins as hedge windows expired. Meanwhile, EPDM and TPE elastomers experienced notable price hikes, driven by refinery outages that tightened the supply of low-Shore-hardness grades, which are essential for liquid-cooled jackets. In response to these market dynamics, small European assemblers held back on capacity expansions. A majority of surveyed firms chose to defer tooling orders, citing significant cost spikes as the primary reason. While aluminum-copper-clad wire offers a cost advantage, it also increases cable diameter, complicating bend radius requirements for urban curbside installations.
Safety Recalls Over Thermal-Runaway Incidents
Porsche recalled Taycans, and Audi pulled back e-trons due to overheating issues caused by cables exceeding a certain amperage. The IEC standard now mandates extended trials at higher loads, a benchmark that many air-cooled products struggle to meet unless they have oversized conductors. Meanwhile, UL introduced a new clause requiring elastomer jackets with a higher Limiting Oxygen Index (LOI). This addition, while increasing costs, significantly reduces flame spread. In response to these challenges, automakers are pivoting towards liquid-cooled assemblies, integrating sensors that activate current derating when temperatures exceed a specific threshold.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Power Supply Type: DC Cables Drive Infrastructure Evolution
DC products grew 16.98% annually and are closing on AC¡¯s 65.16% 2025 lead as fleets pursue 350 kW-plus depot solutions that cut charge times to sub-20 minutes. As the market for DC electric vehicle charging cables grows, Phoenix Contact has achieved a significant cost reduction in its 500-amp assembly. Meanwhile, Megawatt systems are carving out a premium niche for trucks; for instance, ABB's cable, priced accordingly, offers a payback due to enhanced vehicle utilization. Not to be outdone, Leoni's EcoSense Nxt family, leveraging AC technology, has achieved reduced mass, facilitating quicker cable pulls through tight conduits.
Liquid-cooled DC assemblies boast higher gross margins than AC, and these profits are reinvested in R&D. With the convergence of NACS and CCS2, DC vendors are strategically positioned to capitalize on their growing market share in the electric vehicle charging cable sector, aiming to secure design partnerships with both automakers and charging-equipment OEMs.


By Cable Length: Flexibility Demands Drive Longer Configurations
Below-5-meter products led with 45.73% of 2025 revenue, due to curbside and garage installs that prioritize low trip-hazard risk. Yet lines over 10 meters are growing at a 16.85% CAGR as highway plazas reconfigure to add pull-through bays serving pickups and trailers.
Tesla's V4 standard highlights the growing dominance of the mid-range segment, which now holds a significant share of the electric vehicle charging cable market. To counteract resistive loss penalties on extended runs, larger conductors are used, which adds to the per-cable cost. In megawatt truck depots, the adoption of pantograph overhead mounts has made longer lengths the standard, alleviating drivers from manual handling.
By Charging Level: Level 3 Transforms Commercial Applications
Level 2 retained 52.19% of the electric vehicle charging cable market share in 2025 because overnight dwell times align with 7 kW-19 kW AC supply. Yet Level 3 DC solutions, growing at a 16.72% CAGR, are benefiting from grocery-anchored retail dwell times of 15-25 minutes and from government highway mandates requiring minimums of 150 kW-350 kW. Liquid-cooled cables, rated for high amperage, can handle significant power bursts. This capability enables batteries to charge from a low to a high percentage in a short time, setting a new benchmark for consumer expectations.
While Level 1 charging remains a niche, primarily reserved for emergencies, Level 2 vendors are streamlining costs. By adopting standardized protocols, manufacturers can produce larger batches and secure supplier discounts. Meanwhile, DC suppliers are turning the risk of fragmentation into a lucrative opportunity. With one standard gaining traction in North America and another leading in Europe, production is consolidating into high-volume lines, ensuring reduced lead times and enhanced quality control.
By Application Type: Public Infrastructure Accelerates Growth
Private settings¡ªsingle-family homes and gated corporate sites¡ªaccounted for 54.89% of 2025 revenue, but public charging is catching up with a projected 16.66% CAGR as governments bankroll corridor coverage every 50 miles. California has seen the installation of numerous DCFC stations, each utilizing liquid-cooled lines with high power capacity. This technology not only reduces dwell time but also encourages repeat visits.
The electric vehicle charging cable market, especially those linked to public contracts, is experiencing a boost from cable-as-a-service models. Companies like BP Pulse and Electrada are taking on hardware capital expenditures (capex) and offering guaranteed uptime. This approach allows fleets to electrify their depots without the delays associated with utility upgrades. While public operators face challenges with vandalism¡ªwhere a significant percentage of cables in dense metropolitan areas require annual replacement¡ªthey offset these losses against their volume throughput and demand-charge revenues. On the other hand, private multi-family complexes are opting for the lighter EcoSense Nxt cables. These cables not only reduce installation labor but also fit seamlessly within retrofit conduits.
By Connector Type: NACS Standardization Reshapes Market
Type 2 led the 2025 landscape with 42.22% share, thanks to mandatory CCS2 adoption across Europe and parts of Asia-Pacific. At the same time, NACS posted a 16.83% CAGR and overtook CCS1 in new North American DC sites by January 2026, driven by automaker alignment and SAE J3400 standardization, which eliminated licensing fees.
While CCS1 continues to energize the legacy infrastructure in the U.S., its dominance is waning as adapters transition away. CHAdeMO has seen its share of new installations dip to a minimal level. Meanwhile, GB/T, though primarily focused on China, has been upgraded with CCS2 backward compatibility, making it suitable for export vehicles. The electric vehicle charging cable market is increasingly dominated by NACS and CCS2. This concentration allows manufacturers to consolidate multiple distinct production lines, significantly reducing the average lead time for large orders. Additionally, liquid-cooled NACS cables are lighter than earlier CCS1 versions. This is achieved through a compact pin layout in the standard, which shortens conductor paths and reduces copper mass while maintaining robust continuous capacity.
Geography Analysis
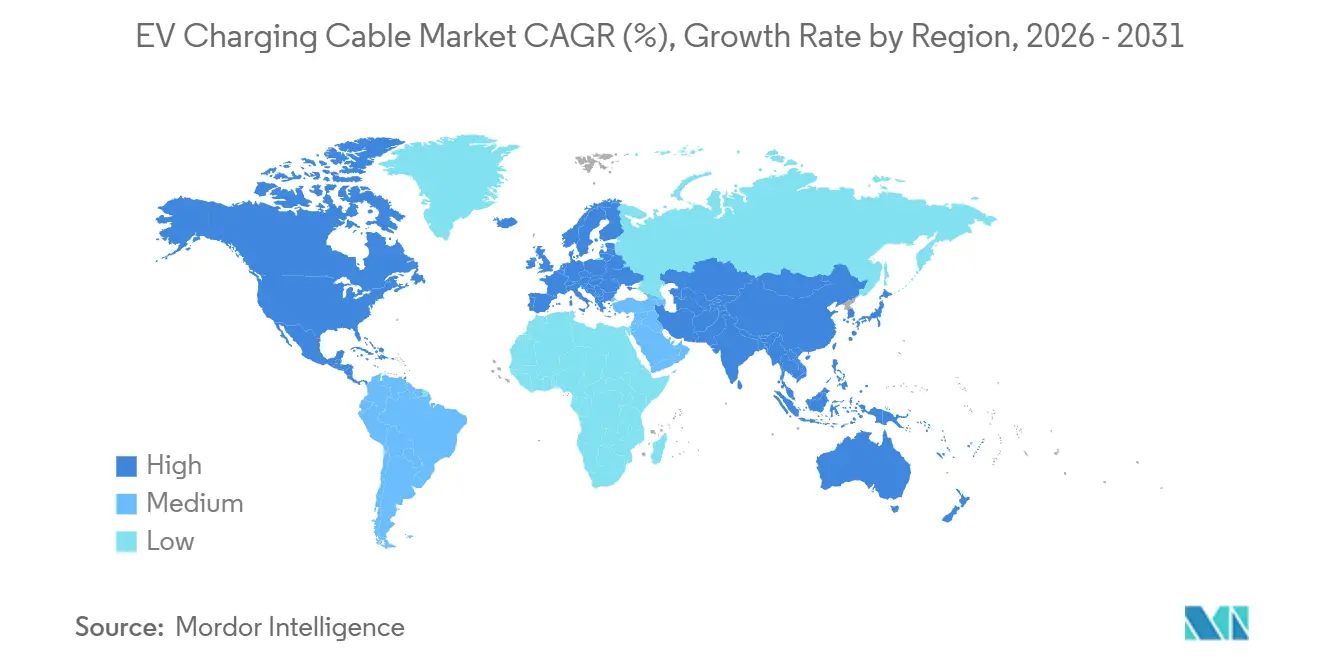
Asia-Pacific maintained 47.41% revenue share in 2025. It will log a 16.94% CAGR through 2031 as China enforces GB/T compatibility with CCS2, stimulating local vendors like Woer New Energy, which shipped 1.5 million GB/T plugs last year. Southeast Asia is set to install new charging points annually, according to the International Energy Agency. This surge is expected to significantly increase demand for 32-amp cables each quarter. Meanwhile, Japan's gradual shift from the CHAdeMO standard to CCS2 necessitates the use of dual-protocol inlets. This transition not only underscores the country's unique position but also highlights the sustained demand for multi-standard cables, even as the industry trends towards broader standardization.
North America leads the charge in standardizing electric vehicle (EV) charging cables, with the adoption of the North American Charging Standard (NACS) now covering a significant share of new ports. Bolstered by the NEVI initiative and Tesla's ambitious expansion of ports, key corridors are becoming denser, predominantly featuring high-capacity cables. Meanwhile, EVgo's rollout of units is set to blanket urban grocery hubs, establishing predictable dwell times that favor high-amp, liquid-cooled lines.
Europe, supported by AFIR regulations, is set to gain additional DC chargers through significant AFIF grants. The competition for premium urban sites is evident in ACCIONA Energ¨ªa's acquisition of Cable Energ¨ªa's network. While Latin America and the Middle East & Africa together account for a small share of revenues, Brazil's investment in the Clean Fuels Infrastructure fund and the UAE's ambitious charger initiatives indicate growing demand.

Competitive Landscape
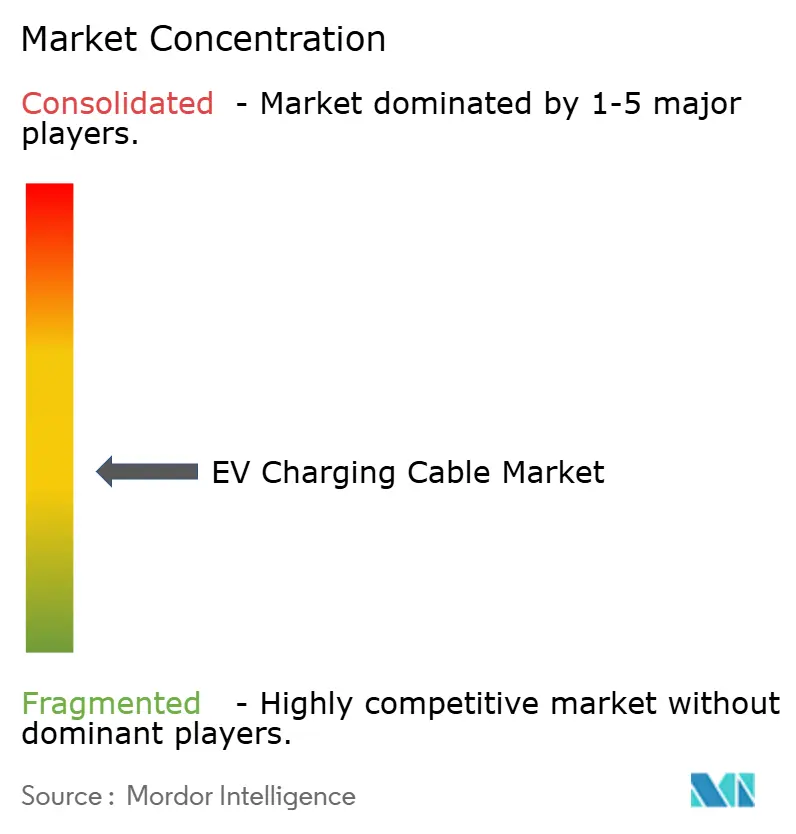
With no single vendor commanding a significant share of global revenue, the electric vehicle charging cable market remains fragmented, yet is on a path to consolidation. In a strategic move, TE Connectivity acquired Phoenix Contact¡¯s inlet business, ensuring a steady pipeline for OEMs ahead of the industry's full shift to NACS[3]¡°TE signs agreement to acquire Phoenix Contact e-Mobility,¡±, TE Connectivity, te.com. Meanwhile, LAPP bolstered its position by acquiring Cableforce Electronics, catering to both European and Asian automakers. BizLink's acquisitions of Alpha in Switzerland, along with EASYS and Cable Connection in Slovakia, have not only verticalized connector design but also introduced a significant margin headroom.
Huber+Suhner stands out with its lightweight, liquid-cooled RADOX HPC500 lines, which reduce the structural load on pedestals. Leoni is championing bio-based jackets for environmentally conscious housing projects. L-Charge, an off-grid specialist, is leveraging renewable gas and hydrogen gensets to sidestep grid limitations and carve out opportunities in rural logistics.
In a shift towards cable-as-a-service, operators like BP Pulse and Electrada are pre-purchasing high-volume lots at discounts. They then bundle these with hardware, energy, and warranties for their fleet clients. While compliance updates, such as UL 2251¡¯s new flame-retardant rule, introduce added costs, they also elevate technical standards. This shift disproportionately benefits larger players, who can spread certification costs across their scale.
EV Charging Cable Industry Leaders
-
Leoni AG
-
TE Connectivity Ltd.
-
Aptiv PLC
-
Sinbon Electronics
-
Phoenix Contact
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- April 2026: Philatron Wire and Cable is set to showcase its cutting-edge EV charging cable technologies at ACT Expo 2026, responding to the surging demand for advanced charging infrastructure. Their offerings feature ultra-flexible subzero cables, UL-listed power cables, and innovative liquid-cooled solutions, all tailored for ultra-fast and next-gen megawatt charging systems, especially for commercial vehicles.
- August 2025: Everged, LLC has chosen i-charging as its partner to roll out i-charging's DC fast charging hardware, integrating it into Everged's suite of EV charging solutions. Through this collaboration, Everged is set to install around 1,000 DC fast charging stations nationwide. These chargers come equipped with advanced cable management systems, enhancing operational convenience.


Global EV Charging Cable Market Report Scope
The EV charging cable market report is segmented by power supply type (AC charging cable and DC charging cable), cable length (below 5 m, 5¨C10 m and above 10 m), charging level (level 1, level 2, and level 3), application type (private charging and public charging), connector type (type 1, type 2, CCS, CHAdeMO, and tesla NACS), and geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa). The market forecasts are provided in terms of value (USD).
| AC Charging Cable |
| DC Charging Cable |
| Below 5 m |
| 5¨C10 m |
| Above 10 m |
| Level 1 |
| Level 2 |
| Level 3 |
| Private Charging |
| Public Charging |
| Type 1 |
| Type 2 |
| CCS |
| CHAdeMO |
| Tesla NACS |
| North America | United States |
| Canada | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| Spain | |
| Italy | |
| France | |
| Russia | |
| Rest of Europe | |
| Asia Pacific | India |
| China | |
| Japan | |
| South Korea | |
| Rest of Asia Pacific | |
| Middle East and Africa | United Arab Emirates |
| Saudi Arabia | |
| Turkey | |
| Egypt | |
| South Africa | |
| Rest of Middle East and Africa |
| By Power Supply Type | AC Charging Cable | |
| DC Charging Cable | ||
| By Cable Length | Below 5 m | |
| 5¨C10 m | ||
| Above 10 m | ||
| By Charging Level | Level 1 | |
| Level 2 | ||
| Level 3 | ||
| By Application Type | Private Charging | |
| Public Charging | ||
| By Connector Type | Type 1 | |
| Type 2 | ||
| CCS | ||
| CHAdeMO | ||
| Tesla NACS | ||
| By Region | North America | United States |
| Canada | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| Spain | ||
| Italy | ||
| France | ||
| Russia | ||
| Rest of Europe | ||
| Asia Pacific | India | |
| China | ||
| Japan | ||
| South Korea | ||
| Rest of Asia Pacific | ||
| Middle East and Africa | United Arab Emirates | |
| Saudi Arabia | ||
| Turkey | ||
| Egypt | ||
| South Africa | ||
| Rest of Middle East and Africa | ||


Key Questions Answered in the Report
What is the 2026 value of the electric vehicle charging cable market?
The electric vehicle charging cable market size stands at USD 1.99 billion in 2026 and is projected to reach USD 4.28 billion by 2031.
How fast are DC charging cables growing compared with AC?
DC cables are expanding at a 16.98% CAGR through 2031, while AC still held 65.16% of 2025 revenue but grows more slowly.
Which region commands the largest share of cable revenue?
Asia-Pacific accounted for 47.41% of global revenue in 2025 and should log a 16.94% CAGR through 2031.
Why are cables over 10 m in length attracting attention?
Longer cables enable single-pedestal layouts in bus and truck depots, driving a 16.85% CAGR as fleet operators prioritize flexible stall design.
How does the NEVI program affect sourcing strategies for cable suppliers?
Buy America clauses incentivize U.S. assembly lines, prompting European and Asian manufacturers to add domestic capacity to secure federal contracts.
Page last updated on:



