
Fluorinated Polyimide Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 1.28 Billion |
| Market Size (2031) | USD 1.65 Billion |
| Growth Rate (2026 - 2031) | 5.21 % |
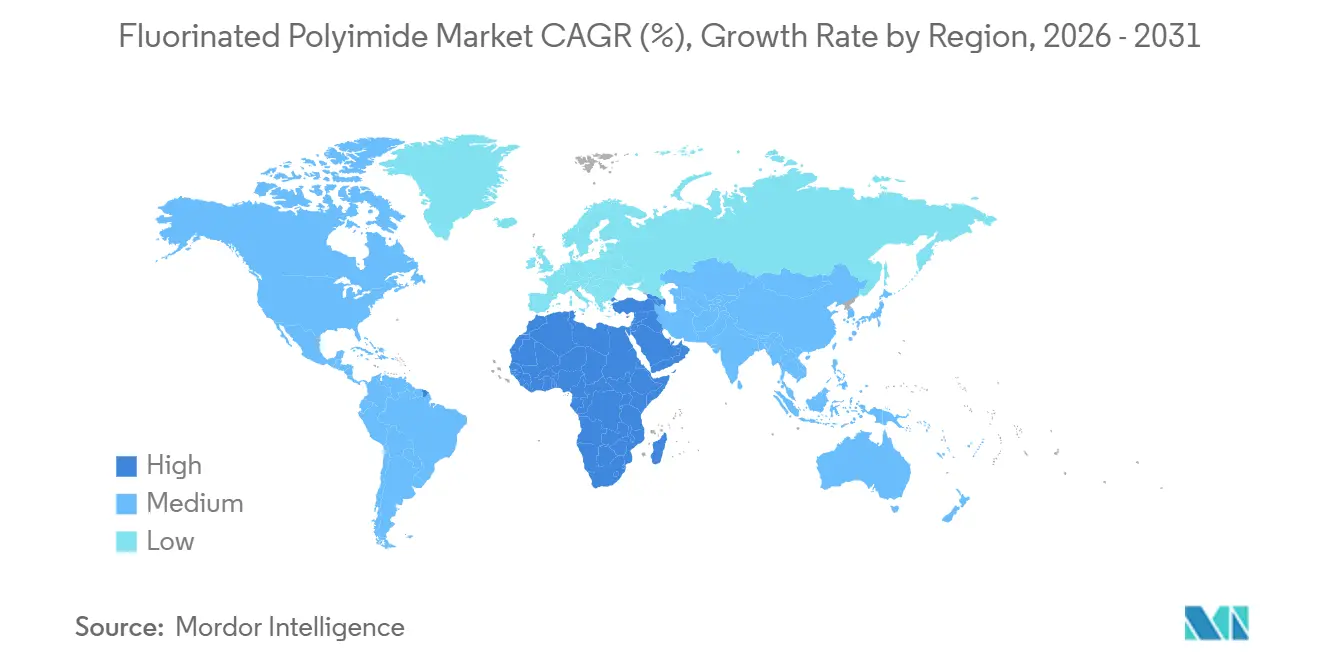
| Fastest Growing Market | Middle East and Africa |
| Largest Market | Asia Pacific |
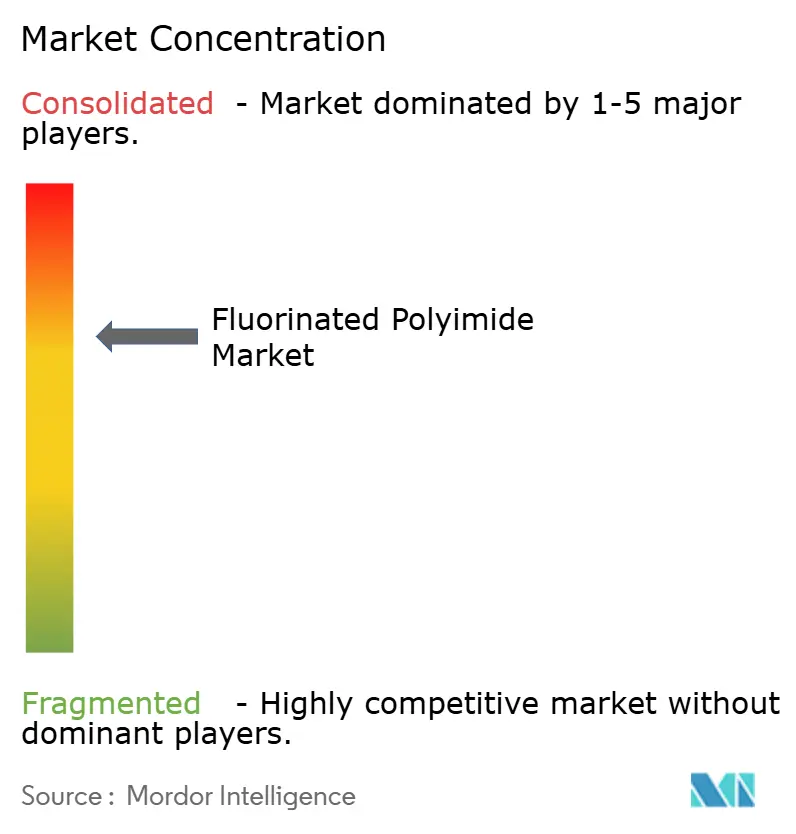
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Fluorinated Polyimide Market Analysis by 麻豆视频
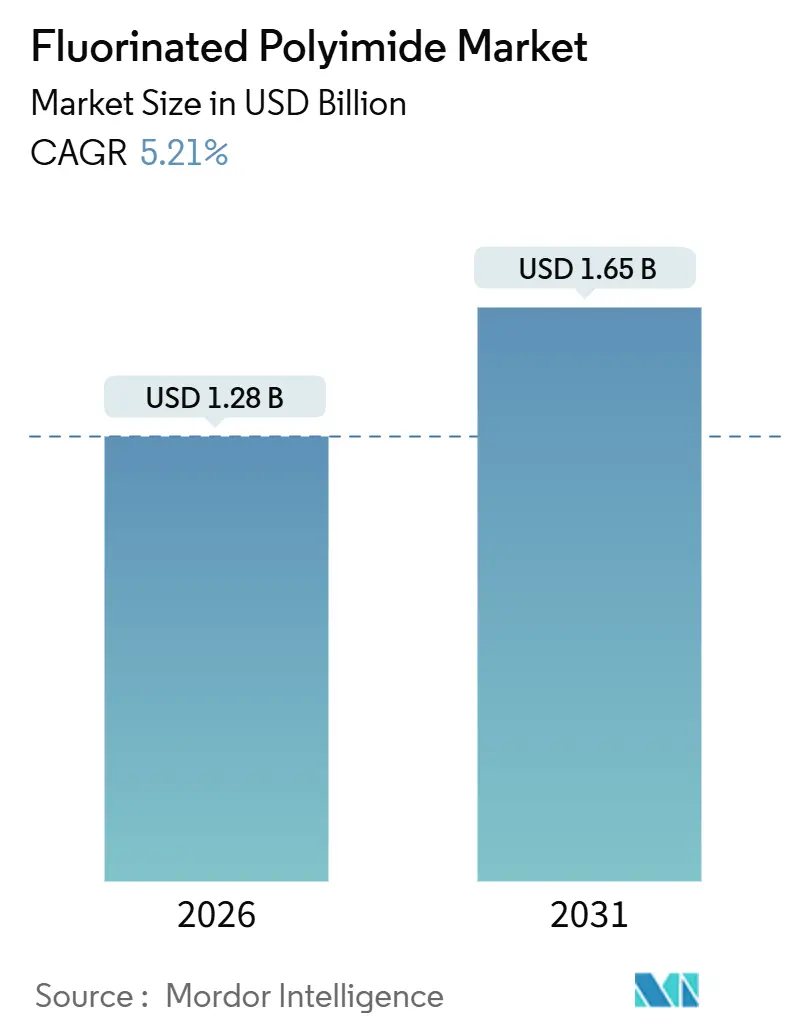
The Fluorinated Polyimide Market size is estimated at USD 1.28 billion in 2026, and is expected to reach USD 1.65 billion by 2031, at a CAGR of 5.21% during the forecast period (2026-2031). A measured headline number masks a strategic shift from rigid substrates toward ultra-thin, heat-stable films that underpin foldable displays, millimeter-wave antennas, and radiation-tolerant solar arrays. Unit growth in smartphones is leveling off, yet display makers are widening the design envelope to rollable televisions, foldable laptops, and curved automotive dashboards, all of which sustain substrate demand. Semiconductor packaging houses have moved to finer line-and-space architectures, pulling through low-dielectric-constant fluorinated grades that survive 400 °C reflow processes. Meanwhile, commercial satellite constellations and Saudi-led solar megaprojects amplify demand for radiation-hardened and UV-resistant films, offsetting slower momentum in Europe and North America, where PFAS regulations inflate compliance costs.
Key Report Takeaways
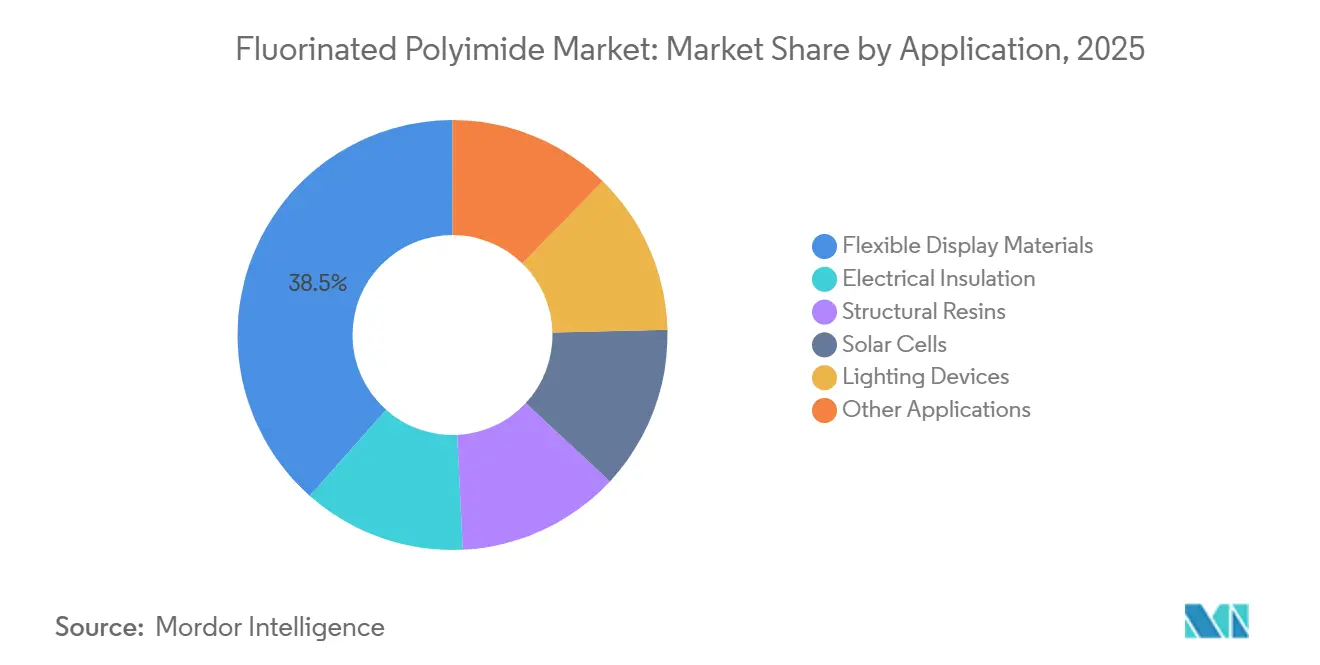
- By application, flexible display materials led with a 38.46% revenue share of the fluorinated polyimide market in 2025, while solar cells are advancing at a 6.34% CAGR through 2031.
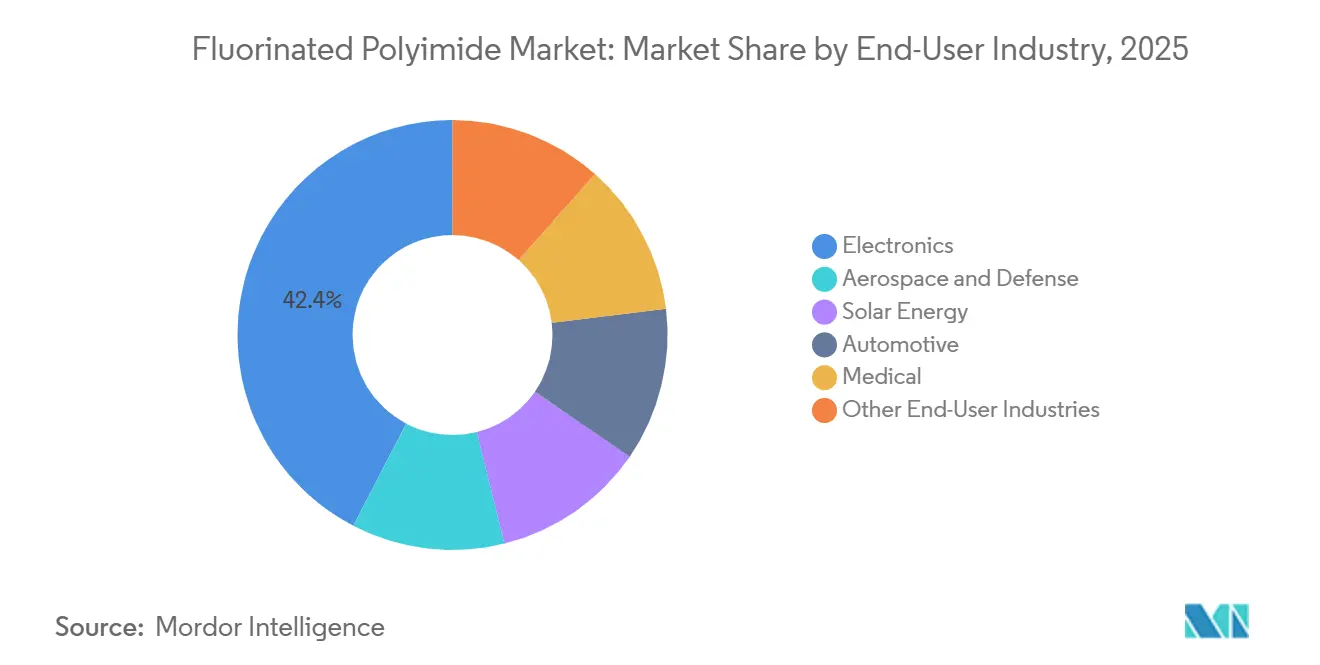
- By end-user industry, electronics accounted for 42.37% of the fluorinated polyimide market share in 2025, whereas solar energy is projected to expand at a 6.41% CAGR to 2031.
- By geography, Asia-Pacific contributed 49.28% of the 2025 value, and the Middle East and Africa region is forecast to post a 5.92% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Fluorinated Polyimide Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in consumer demand for flexible display devices | +1.3% | APAC core (South Korea, China), spill-over to North America | Short term (≤ 2 years) |
| Ramp-up of 5G/high-frequency infrastructure necessitating low-Dk films | +1.2% | Global, with early concentration in APAC and North America | Medium term (2-4 years) |
| Electronics miniaturization demanding ultra-thin, heat-resistant substrates | +0.9% | Global, led by APAC electronics hubs | Medium term (2-4 years) |
| Space-grade solar-array substrates requiring radiation-hardened FPIs | +0.7% | North America, Europe (satellite programs), emerging in Middle East | Long term (≥ 4 years) |
| Additive manufacturing unlocks on-site custom aerospace components | +0.6% | North America, Europe (aerospace clusters) | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Surge in Consumer Demand for Flexible Display Devices
Foldable smartphones have shifted from concept to mainstream, and the installed base of flexible OLED lines now exceeds 15 plants in South Korea and China. Each line consumes colorless fluorinated polyimide films thinner than 50 ?m that must survive 200,000-fold cycles without cracking. Fluorination lowers the refractive index and curbs yellowing, helping devices maintain color gamut across their service life. Samsung’s Galaxy Z series shipped several million units in 2025; by extending foldable form factors to mid-tier price points, panel makers expect to double substrate throughput by 2028. Hybrid stacks combining ultra-thin glass and fluorinated polyimide balance scratch resistance with flexibility, a trend likely to spread to automotive clusters and wearable screens.
Ramp-up of 5G/High-Frequency Infrastructure Necessitating Low-Dk Films
Millimeter-wave antennas operating beyond 24 GHz demand low dielectric constants and dissipation factors. Fluorinated polyimides maintain a high glass-transition temperature, allowing for seamless integration into antenna-in-package modules without the risk of warpage. In 2025, base station deployments surged, and the trend of densifying with small cells further amplified the demand for low-loss flex circuits. IEEE laminate guidelines have shortened qualification cycles, permitting material suppliers to convert pilot-plant output to commercial scale faster than in prior wireless generations.
Electronics Miniaturization Demanding Ultra-Thin, Heat-Resistant Substrates
System-in-package designs are now stacking multiple dies within footprints with high power density. Redistribution layers and die-attach films, made from fluorinated polyimide tapes, can withstand high solder reflow temperatures without outgassing. Fan-out wafer-level packaging, a method embraced by foundries in Taiwan and South Korea, completely does away with rigid substrates. Instead, it utilizes polymer layers for signal routing, significantly increasing the demand for polymers in each package. As chipmakers shift towards chiplet architectures for 2.5-D integration, the anticipated rise in interconnect layers is set to further amplify this demand.
Space-Grade Solar-Array Substrates Requiring Radiation-Hardened FPIs
Fluorinated polyimides have become essential for solar arrays destined for space, thanks to their resilience against proton and electron flux degradation and atomic oxygen attacks. These materials maintain their mechanical strength even after exposure to high-energy electron radiation, surpassing the performance of their non-fluorinated counterparts. Weighing significantly less than rigid panels, the film enables satellite designers to fit larger arrays within fixed payload envelopes. With commercial broadband constellations planning to deploy thousands of satellites by 2030, each designed to carry flexible cells, the demand for radiation-hardened films is poised to grow significantly.
Restraints Impact Analysis of Fluorinated Polyimide Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High production costs and raw-material volatility | -0.8% | Global, acute in regions with limited monomer supply | Short term (≤ 2 years) |
| Stringent PFAS-related environmental regulations | -0.7% | North America, Europe; potential spill-over to APAC | Medium term (2-4 years) |
| OLED image-sticking failures linked to fluoride-ion migration | -0.6% | APAC core (South Korea, China), North America | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
High Production Costs and Raw-Material Volatility
Hexafluoroisopropylidene-based dianhydrides command multiples of conventional aromatics, reflecting multi-step syntheses and specialized containment. An unplanned outage at a single supplier can spike spot prices within weeks, and currency swings magnify volatility because many contracts are denominated in euros or yen. Integrated players such as DuPont and Daikin can buffer disruptions by back-integrating into monomers, but smaller converters lack this hedge and face allocation risk during tight markets.
Stringent PFAS-Related Environmental Regulations
In 2023, the European Chemicals Agency proposed sweeping restrictions on around 10,000 PFAS compounds under REACH[1]European Chemicals Agency, “Annex XV Restriction Report: Per- and Polyfluoroalkyl Substances (PFASs),” ECHA.EUROPA.EU. This move includes high-molecular-weight fluorinated polyimides, compelling companies to demonstrate the absence of safer alternatives for every specific use. Meanwhile, in April 2024, the U.S. EPA classified PFOA and PFOS as hazardous substances under CERCLA. This designation brings about cradle-to-grave liability and necessitates expensive upgrades to wastewater systems. As a result, compliance could increase production costs and postpone the introduction of new grades.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Fluorinated Polyimide Market Segment Analysis
By Application:
Displays Dominate Volume, Solar Cells AccelerateFlexible display materials captured 38.46% of 2025 revenue, mirroring the proliferation of foldable and rollable OLED products. This slice of the fluorinated polyimide market is sustained by South Korean and Chinese fabs expanding Gen-6 lines and by automotive OEMs piloting curved dashboards. Electrical insulation—wire coatings, motor slot liners, transformer tapes—delivers stable volume because utilities favor proven dielectrics over cheaper substitutes.
Solar cells are projected to log a 6.34% CAGR, the highest among applications, as mega-constellations and Middle East concentrator farms demand radiation-hardened and UV-stable backsheets. Lighting devices such as OLED luminaires adopt thin, transparent films for architectural and automotive ambient lighting, a modest but rising outlet. Niche uses—from medical catheters to high-frequency connectors—round out the application mix, underscoring material versatility.


By End-User Industry:
Electronics Leads, Solar Energy SurgesElectronics held 42.37% of 2025 demand, anchored in smartphones, tablets, and laptops. Growth now depends on emerging form factors—foldable laptops, flexible monitors, augmented-reality glasses—rather than incremental handset volume. Aerospace and defense capitalize on flame resistance and dimensional stability; fluorinated grades meet FAA flammability norms without halogens, simplifying end-of-life handling. Additive manufacturing of custom brackets adds an incremental pull as qualified printers spread across maintenance depots.
Solar energy is forecast to post a 6.41% CAGR, the fastest among end users, fueled by orbital power systems and desert-based concentrator farms that require backsheets resilient to UV and particle bombardment. Automotive demand stretches beyond instrument clusters to heating elements, heads-up displays, and battery busbars. Medical applications—catheter liners, implantable electrode carriers—leverage reduced protein adsorption to extend device life, while oil-and-gas sensors and industrial automation labels furnish steady niche consumption.
Geography Analysis
APAC Fluorinated Polyimide Market
Asia-Pacific held 49.28% of the 2025 value on the back of South Korea’s flexible OLED dominance and China’s 5G rollout. Samsung Display, LG Display, and BOE collectively control most of the world’s foldable-panel throughput, consuming large volumes of colorless films. Japan retains expertise in monomer synthesis; suppliers like Kaneka and Ube provide high-purity feedstocks, sustaining a regional ecosystem unbeatable on cost and quality. India is ramping up electronics assembly, though substrates remain largely imported.
North America Fluorinated Polyimide Market
Growth in North America is propelled by aerospace and satellite projects. DuPont’s Circleville, Ohio, expansion added Kapton and Pyralux capacity, targeting EV battery interconnects and 5G antenna modules. Regulatory drag in the United States—where CERCLA liability applies to PFAS—pressures margins and encourages some converters to shift secondary processing offshore.
EMEA and South America Fluorinated Polyimide Market
In Europe, the market is divided between Germany’s in-car electronics, France and the UK’s aerospace composites, and specialized industrial niches. The broad PFAS restriction proposal lengthens approval cycles and deters greenfield investment. Airbus and satellite primes continue to specify fluorinated films, but consumer-electronics manufacturing remains minimal compared with Asia. South America and the Middle East and Africa together account for small revenue; the latter will expand at 5.92% as Saudi Arabia and the UAE roll out gigawatt-scale solar farms that mandate heat-stable, low-outgassing backsheets.

Regulatory Landscape
Fluorinated polyimides operate in a tightening PFAS compliance environment, with the sharpest effects in the European Union and the United States. In Europe, the European Chemicals Agency (ECHA) advanced the REACH PFAS restriction workstream through 2025 updates and 2026 consultations, including a two-month consultation in March 2026 and a further public consultation in April 2026 on the SEAC draft opinion. This keeps qualification and investment decisions closely tied to how high-molecular-weight fluorinated polymers are scoped and whether exemptions apply.
In the United States, fluorinated polyimide chemistries can trigger additional reporting and downstream controls depending on use and form, including Significant New Use reporting pathways under 40 CFR 721.11119 for certain functionalized polyimide/polyamide substances (with cured forms excluded). For applications that reach regulated end markets, polyimide-related resins used in food-contact articles must meet requirements and extraction limits referenced in 21 CFR 177.2450 and 21 CFR 177.1595. For electrical insulation film performance, qualification is commonly aligned with international specifications such as IEC 60674-3-4:2022.
Value Chain Analysis
The value chain starts with fluorinated monomer production, notably hexafluoroisopropylidene-based dianhydrides and high-purity aromatic diamines. This supply base is geographically concentrated and sensitive to outages and logistics disruption. Monomers are converted through poly(amic acid) synthesis and imidization into fluorinated polyimide resins, then processed into films through casting/calendering and stretching. Upgrades continue via surface treatment and downstream converting such as coating, laminating, and copper cladding for flex circuits and advanced interconnects.
Midstream film producers and converters co-develop specifications with electronics, display, and packaging customers, where qualification cycles and performance gatekeeping (often aligned with IPC and SEMI-type benchmarks) influence adoption speed. Downstream routes include colorless films for flexible and foldable OLED stacks, low-Dk dielectric layers for antenna-in-package and semiconductor redistribution architectures, and radiation/UV-resistant films for space-grade solar arrays. Alongside technical qualification, compliance documentation and traceability are increasingly integrated as PFAS-related controls expand across jurisdictions.
Competitive Landscape
The fluorinated polyimide market is moderately consolidated in nature. Integrated players command monomer synthesis, film calendaring, and downstream coating, ensuring end-to-end quality control. Capital intensity is high; DuPont invested USD 220-250 million between 2019 and 2022 to boost Kapton capacity at Circleville, underscoring barriers to entry[2]DuPont, “DuPont Announces Major Investment in Kapton Polyimide Capacity,” DUPONT.COM . Niche converters in South Korea and Taiwan have carved competitive space in ultra-thin, colorless films tailored to specific hinge radii and scratch-resistant overlays. Many operate in close collaboration with panel makers, co-locating pilot coaters inside clean rooms to accelerate iterative design. Emerging opportunities include additive manufacturing feedstocks and bio-based fluorinated polyimides. Aerospace primes seek pellet-fed extruders that avoid nozzle clogging while printing high-temperature parts on demand. Regulatory scrutiny of PFAS is steering research and development toward partially fluorinated or renewable dianhydrides, though current bio-routes still trail incumbents on thermal stability. Chinese newcomers, buoyed by state subsidies, are racing to localize monomer production, potentially eroding incumbent pricing power in commodity display grades.
Fluorinated Polyimide Industry Leaders
DuPont
Kaneka Corporation
Kolon Industries
Sumitomo Chemical Co. Ltd.
Daikin Industries Ltd.
- *Disclaimer: Major Players sorted in no particular order
Fluorinated Polyimide Market Companies Covered in this Report
- AGC Inc.
- Arkema
- Capchem
- CAPCHEM
- Daikin Industries Ltd.
- DuPont
- I.S.T Corporation
- Kaneka Corporation
- Kolon Industries
- Mitsubishi Gas Chemical Company, Inc.
- Nexolve
- SKC
- Solstice Advanced Materials
- Solvay
- Sumitomo Chemical Co. Ltd.
- Taimide Tech. Inc.,
- Toray TCAC Holding B.V.
- UBE Corporation
- Zhuzhou Times New Material Technology Co., Ltd. (TMT)

Market Opportunities and Future Outlook
An opening is emerging at the intersection of high-frequency communications, advanced packaging, and optical interconnects, where fluorinated polyimide design work targets tighter dielectric-loss windows and improved mechanical toughness at ultra-thin gauges. Evidence of this shift appears in 2025-2026 research activity around -CF3 and -OCF3 molecular design to tune refractive index and birefringence for short-distance optical communication waveguides, and to lower dielectric constants for high-frequency chip packaging and antenna modules.
Processing innovation is also creating opportunities beyond classic film supply, particularly photo-patternable and UV-curable fluorinated polyimide dielectrics that support fine-feature fabrication in flexible electronics and dense interconnect architectures. Multifunctional formats, such as fluorinated polyimide aerogels engineered for thermal insulation and ultralow-k performance (reported in 2026 literature), point to an emerging route into aerospace radomes, antenna covers, and other high-reliability insulation use cases where heat management and signal integrity are specified together rather than as separate materials.
Recent Industry Developments in Fluorinated Polyimide Market
- March 2026: Kaneka Corporation announced a price revision for its Apical and Pixeo polyimide film products, raising prices by 20% for shipments from April 16, 2026. The company attributed the increase to higher energy costs and instability in maritime transportation conditions linked to the Middle East, highlighting cost pass-through dynamics in high-performance film supply.
- June 2025: DuPont highlighted advanced interconnect offerings at JPCA Show 2025 in Tokyo, including Pyralux ML laminates and Pyralux AP flexible copper-clad laminate. The update reinforces the focus on materials for dense circuitry and next-generation electronics, where polyimide-based laminates sit close to end-use qualification cycles.
- July 2024: Arkema integrated PI Advanced Materials further into its high-performance materials portfolio following its majority ownership, extending emphasis on polyimide films for electronics and electric mobility value chains. The move supported broader market access for specialized film grades through a larger global materials platform and customer network.


Fluorinated Polyimide Market Report Scope and Research Methodology
Market Definition and Coverage
For this report, we define the fluorinated polyimide market as revenue generated from fluorinated polyimide materials sold for downstream use in electronics, optoelectronics, insulation, and other industrial applications, across all key producing and consuming regions.
Scope exclusions: Excluded from this market are finished consumer devices and non-fluorinated polyimide materials that do not use fluorinated chemistries.
Segments Covered in This Report
- By Application
- Flexible Display Materials
- Electrical Insulation
- Structural Resins
- Solar Cells
- Lighting Devices
- Other Applications
- By End-User Industry
- Electronics
- Aerospace and Defense
- Solar Energy
- Automotive
- Medical
- Other End-User Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to understand how demand forms and where fluorinated polyimide is typically specified, especially in flexible displays, electrical insulation, structural resins, solar cells, and lighting uses. We reviewed public and official sources such as US International Trade Commission data tools, UN Comtrade, national statistical agencies, and trade bodies tied to plastics and electronics value chains. For end-use direction, we also referenced open sources such as government energy agencies for solar installation trends and defense procurement releases where advanced polymers are mentioned as qualifying materials.
To connect this context to revenues, we used general secondary sources like annual reports, investor presentations, press releases, and product brochures that indicate capacity additions, product positioning, and major application shifts (for example, ultra-thin films for foldable form factors). Where available, paid database subscriptions were used only to standardize company financials, track patent activity around fluorinated polyimide formulations, and check shipment and tender signals that can confirm timing. The desk sources listed above are illustrative, and many other public materials were used to collect data points, validate assumptions, and clarify inconsistencies.
Primary Interviews and Surveys
Primary work was used to pressure-test assumptions that are hard to confirm from documents alone, such as application mix, typical pricing movement, and how quickly new display and insulation specifications translate into material orders. We spoke with a mix of material suppliers, compounders, distributors, and downstream users across APAC, EMEA, and the Americas, and then we rechecked any major variance through follow-up questions until a consistent range was reached.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 29% | CXOs: 16% | APAC: 47% |
| Mid tier: 50% | Functional/Unit leaders: 28% | EMEA: 32% |
| Smaller Players: 21% | Managers: 56% | Americas: 21% |
Market-Sizing & Forecasting
Sizing starts from a top-down build that reconstructs the demand pool by application and end-use, using adoption and production indicators that are visible in public series and then corrected with interview inputs. In practice, we map fluorinated polyimide consumption to signals such as flexible display panel output and related material loading, electrical and electronics production trends, solar installation momentum, and aerospace and defense qualification cycles that affect specialty polymer usage.
Those demand anchors are converted into value using an ASP logic that reflects grade differences and typical pricing movement reported by industry participants, followed by adjustments for regional mix and channel markups where distribution is material. To keep the totals grounded, we corroborate the model with selective bottom-up approximations such as supplier revenue splits disclosed in filings, capacity announcements translated into realistic utilization ranges, and sampled price checks for common film and resin grades. When company level details are incomplete, gaps are handled through peer benchmarking and conservative utilization assumptions, and then the implied totals are revalidated against the application split discussed in primary calls.
For forecasting, scenario analysis is used because end markets such as flexible displays and electronics can swing with investment cycles, and experts often provide ranges instead of single-point expectations. The forward view is guided by variables like new foldable device launches, fab expansion schedules, insulation demand tied to electrification, and the pace of qualification in aerospace and defense, which are then reconciled into a single base-case forecast curve.
Data Validation & Update Cycle
Validation is done through triangulation across demand indicators, supply signals, and pricing logic, so that one weak data point does not drive the final number. Our team runs variance checks by region and by application, and any outliers are investigated by revisiting the input series, rechecking currency timing, and confirming whether the value reflects material sales or downstream product revenue.
Before sign-off, the model is reviewed in steps, starting with consistency checks at the application level and ending with an overall sanity check against independent market signals such as capacity movement, trade flows, and major end-use activity. Reports are refreshed on an annual cycle, and interim updates are made when material events occur such as large capacity additions, sharp raw material price moves, or demand shocks. Right before delivery, we do a final pass to ensure the latest publicly available developments are reflected in the narrative and numbers.
麻豆视频's Fluorinated Polyimide Market Sizing Compared With Other Published Estimates
Published market sizes for fluorinated polyimide can look far apart even when they appear to cover the same end uses, because the underlying scope and conversion logic are not always consistent. Differences usually come from what is counted as fluorinated polyimide versus adjacent high-performance polymers, which application buckets are included, and how pricing and utilization are treated across regions.
Finished foldable displays and device level revenues sit outside 麻豆视频's scope, which removes a major inflation point that some estimates unintentionally introduce when translating display growth into material sales. Other gaps often come from assuming full capacity use for specialty films, mixing non-fluorinated polyimide grades into totals, or applying aggressive ASP step-ups without rechecking them with channel feedback and regional mix shifts.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 1.28 B (2026) | |
| Industry Analytics A | USD 1.40 B (2024) | Uses an earlier base year and appears to blend in broader electronics growth assumptions, with limited transparency on whether non-fluorinated polyimide grades are excluded from revenue. |
| Market Tracker B | USD 0.14 B (2024) | Looks closer to a narrow product-type or early-stage supply view, which can undercount downstream uses like insulation and structural resins and miss the effect of value-added grades. |
The spread in the table is mainly explained by scope width and by how demand signals are translated into material revenues rather than device sales. By keeping application mapping, pricing logic, and utilization checks traceable to repeatable inputs, we end up with a midpoint estimate that can be reconciled back to observable industry activity.


Key Questions Answered in the Report
How large is the fluorinated polyimide market in 2026, and what growth rate is expected?
The fluorinated polyimide market size reached USD 1.28 billion in 2026 and is projected to rise to USD 1.65 billion by 2031 at a 5.21% CAGR.
Which application segment leads revenue?
Flexible display materials led with a 38.46% share in 2025, reflecting heavy use in foldable and rollable OLED products.
Which end-user industry is expanding the fastest?
Solar energy shows the highest growth, forecast to post a 6.41% CAGR through 2031 as orbital and desert solar projects multiply.
Why is Asia-Pacific dominant in fluorinated polyimide demand?
Co-location of OLED panel facilities, semiconductor packaging hubs, and 5G network rollouts gives Asia-Pacific 49.28% of the 2025 value and a continuing scale advantage.
How are PFAS regulations affecting producers?
U.S. CERCLA designations and the EU’s broad PFAS restriction proposal add compliance costs, extend product-approval timelines, and may prompt reformulation or relocation of capacity.
Page last updated on:



