
France Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 46.31 Million |
| Market Size (2026) | USD 53.73 Million |
| Market Size (2031) | USD 113.05 Million |
| Growth Rate (2026 - 2031) | 16.02 % |
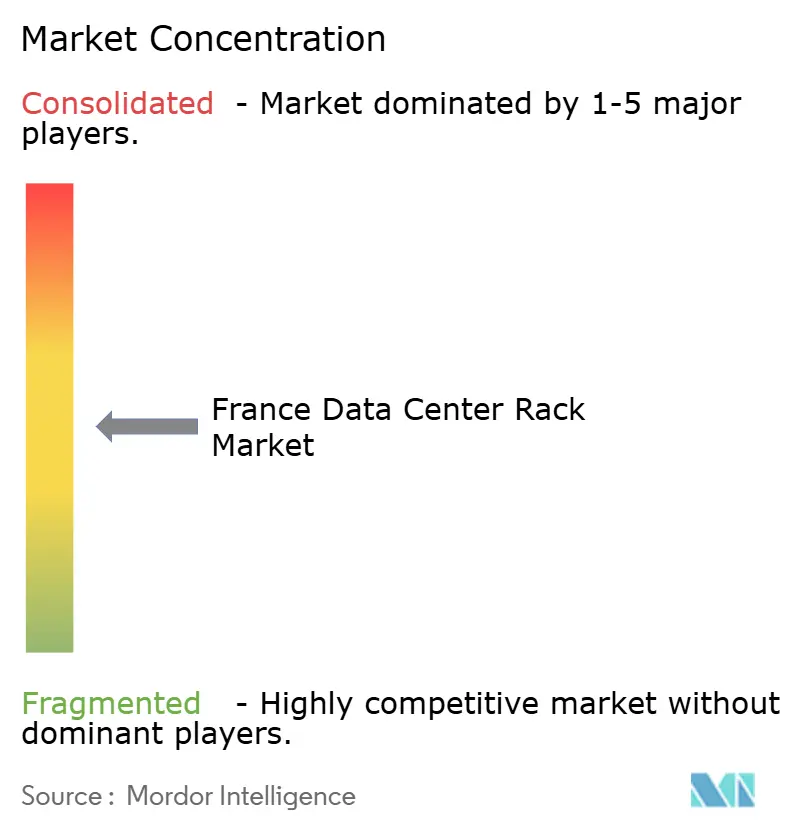
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
France Data Center Rack Market Analysis by 麻豆视频
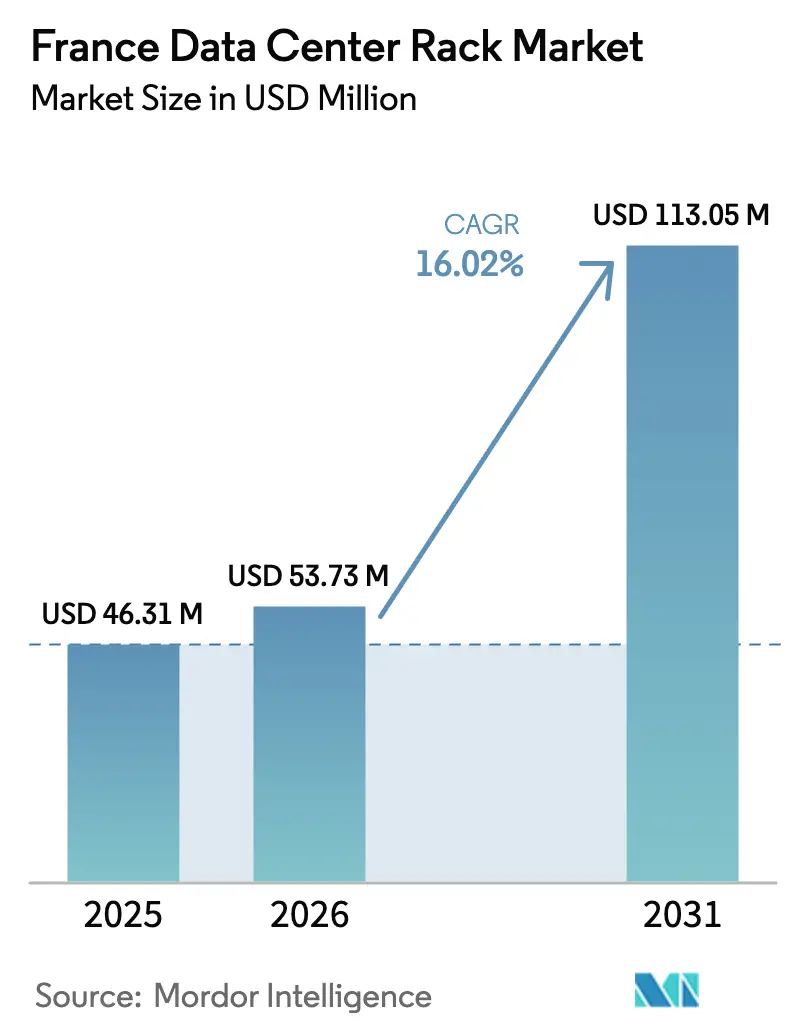
France data center rack market size in 2026 is estimated at USD 53.73 million, growing from 2025 value of USD 46.31 million with 2031 projections showing USD 113.05 million, growing at 16.02% CAGR over 2026-2031. Robust sovereign-cloud incentives, hyperscale build-outs linked to AI training clusters, and a nuclear-powered grid that regularly enables power-usage-effectiveness (PUE) targets below 1.3 collectively underpin this growth trajectory. Standardized full-rack designs, widespread cabinet adoption for GDPR compliance, and the rapid take-up of 48U heights—each tailored to high-density GPU workloads—further consolidate market acceleration. National policies assigning “project of national interest” status to strategic data center investments, combined with 35 government-prepared powered land parcels, mitigate grid-connection moratorium risks and sustain investor confidence. Meanwhile, Brookfield’s EUR 20 billion commitment through Data4, AMD’s rack-level acquisition of ZT Systems, and Schneider Electric’s new AI-ready lab portfolio collectively illustrate the competitive stakes and the premium placed on turnkey rack solutions ready for liquid cooling and advanced power distribution. [1]Datacenter Dynamics, “Brookfield Commits EUR 20 Billion to French Data Centers,” datacenterdynamics.com
Key Report Takeaways
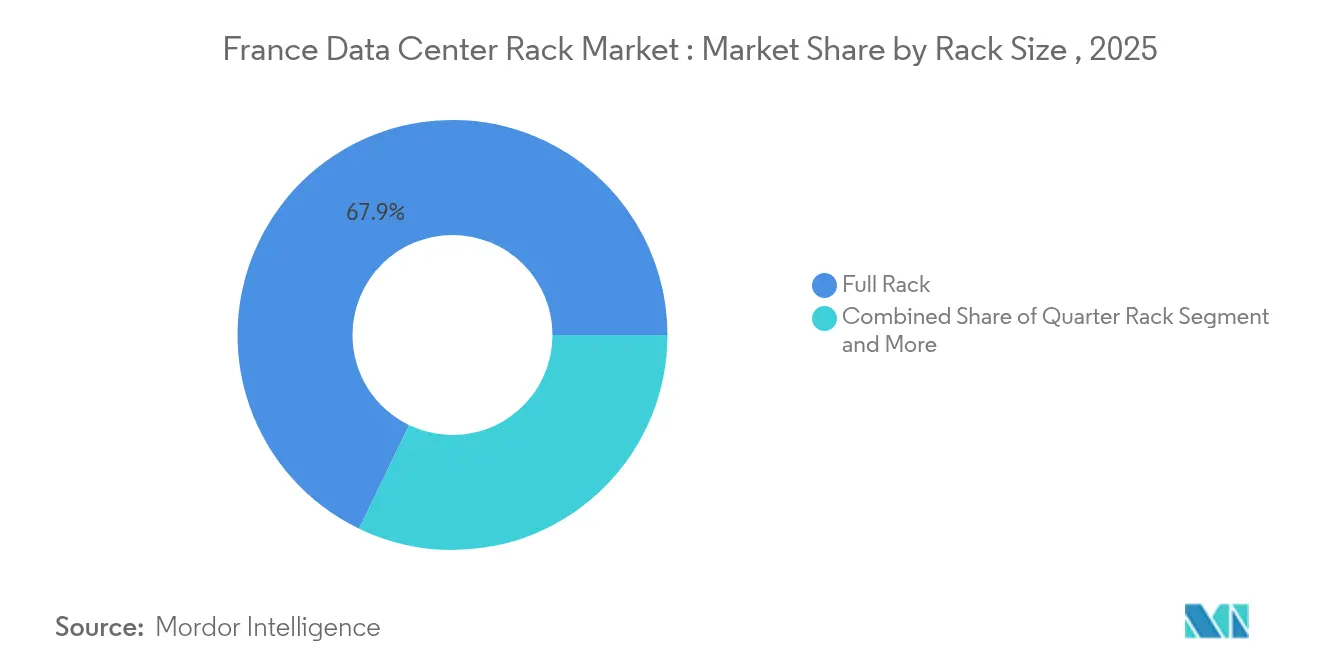
- By rack size, full-rack configurations held 67.85% of France data center rack market share in 2025 and are expanding at an 18.55% CAGR to 2031.
- By rack height, 42U accounted for 52.50% of the France data center rack market size in 2025, while 48U racks are advancing at a 19.02% CAGR.
- By rack type, cabinet solutions captured 74.74% revenue share in 2025; open-frame racks record the fastest projected CAGR at 17.03% through 2031.
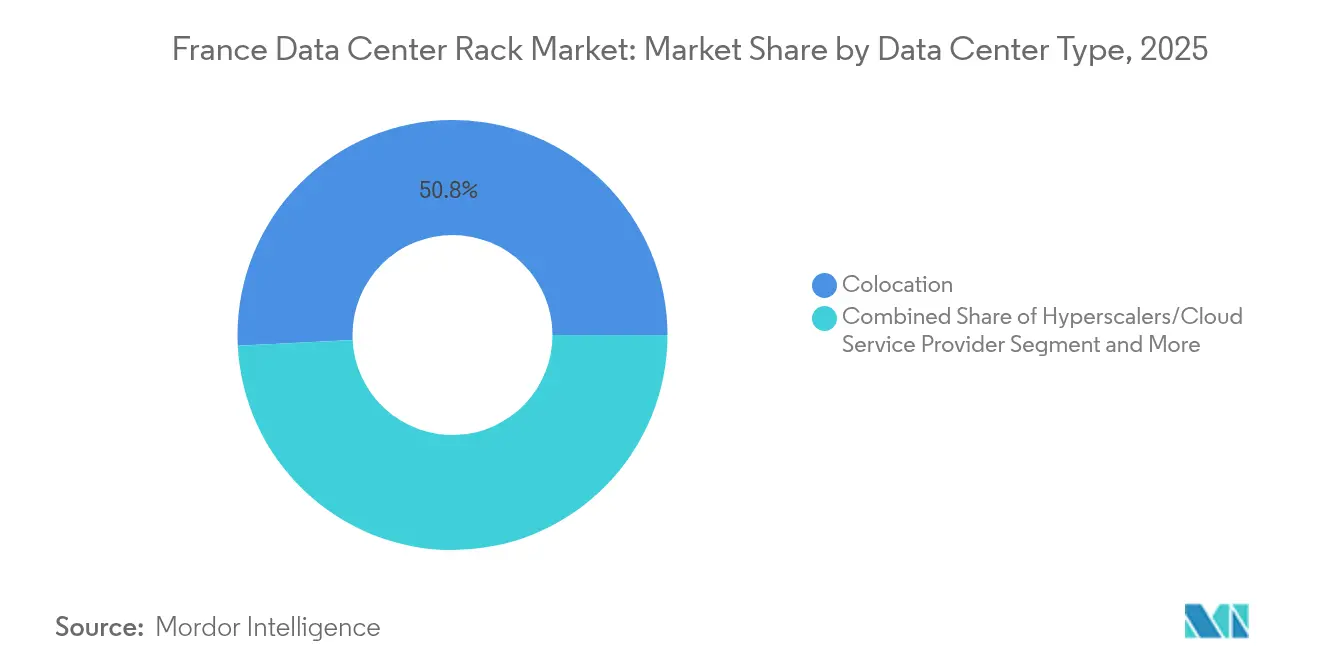
- By data center type, colocation facilities led with 50.80% share of the France data center rack market size in 2025, yet hyperscale investments deliver an 18.02% CAGR.
- By material, steel retained 73.60% share in 2025, while aluminum commands the highest growth at 16.98% CAGR.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
France Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in cloud-first enterprise strategies | +2.8% | National, focused on ?le-de-France & Marseille | Medium term (2-4 years) |
| Expansion of nationwide fiber backbone | +2.1% | National, corridor links among major cities | Long term (≥ 4 years) |
| “Cloud de Confiance” sovereign-cloud incentives | +3.2% | National, preference for French-controlled sites | Short term (≤ 2 years) |
| AI training clusters exceeding 30 kW per rack | +4.1% | Paris region & Sophia Antipolis | Medium term (2-4 years) |
| Paris-2024 digital-legacy hyperscale build-outs | +1.9% | ?le-de-France | Short term (≤ 2 years) |
| Low-carbon nuclear grid enabling <1.3 PUE | +2.4% | National | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Surge in Cloud-First Enterprise Strategies
French enterprises are modernizing IT estates, migrating from legacy on-premise stacks to hybrid architectures that call for resilient, high-density racks inside local data halls. The October 2024 server-procurement program confirmed the government’s pivot toward hybrid infrastructure, unlocking rack orders that support both private-cloud nodes and edge micro-data centers. Legrand now derives 20% of group revenue from data-center activity, confirming the strategic weight of the France data center rack market for diversified industrial suppliers . As edge topologies proliferate, rack designs must deliver uniform power distribution, fast serviceability, and integrated monitoring for AI inference engines as well as conventional enterprise workloads.
Expansion of Nationwide Fiber Backbone
RTE’s EUR 300 million allocation for mutualized reception zones tightly couples backbone fiber with high-capacity substations, encouraging hyperscale and colocation players to position compute sites far beyond Paris. The Hauts-de-France region exemplifies this decentralization, pairing favorable electricity pricing with sub-5 ms latency to London and Amsterdam routes. Vendors competing in the France data center rack market therefore emphasize rapid-assembly cabinet kits, remote locking, and predictive failure analytics—features demanded by remote sites where in-house engineering talent is thinner.
Cloud de Confiance” Sovereign-Cloud Incentives
The Orange-Capgemini venture Bleu and the Thales-Google partnership S3NS illustrate how data-localization rules drive a new procurement calculus that rewards racks with enhanced audit trails, tamper-evident doors, and SecNumCloud-ready documentation. Enclosed cabinet racks with biometric access modules dominate large tenders because French-controlled cloud operators must provide regulators with unequivocal evidence of physical security. Suppliers able to bundle compliance tooling directly into cabinet SKU codes capture premium margins within the France data center rack market.
AI Training Clusters Pushing > 30 kW/Rack Densities
NVIDIA reference designs with Schneider Electric highlight a leap to 132 kW per rack, validating the technical pivot toward rear-door heat exchangers and direct-to-chip liquid. Evroc’s 96-MW campus near Sophia Antipolis will host 50,000 GPUs, requiring rows of 48U and 52U cabinets pre-plumbed for warm-water cooling. This density arms race cements full-height cabinet supremacy in the France data center rack market while opening a parallel lane for aluminum frames that trim weight loads on raised floors without sacrificing torsional rigidity.
Restraints Impact Analysis*
| Escalating cyber-security & GDPR compliance costs | ?1.8% | National, higher impact in regulated verticals | Short term (≤ 2 years) |
|---|---|---|---|
| Scarcity of powered land parcels in ?le-de-France | ?2.4% | Paris metropolitan area | Medium term (2-4 years) |
| Grid-connection moratoriums delaying new builds | ?1.6% | Urban growth zones | Short term (≤ 2 years) |
| Embodied-carbon disclosure raising steel CAPEX | ?1.1% | National, tied to EU mandates | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Escalating Cyber-Security and GDPR Compliance Costs
Facial-recognition oversight clarified in the 2024 European Data Protection Board guidelines forces operators to retrofit cabinets with multi-factor access controls, RFID audit rails, and environmental sensor arrays. [3] European Data Protection Board, “Guidelines on Facial Recognition,” edpb.europa.eu France’s transposition of the NIS2 directive compels real-time security telemetry, lifting per-rack outlays and elongating certification cycles. For vendors in the France data center rack market, differentiated value now hinges on turnkey security modules pre-aligned with both GDPR and corporate-sustainability mandates.
Scarcity of Powered Land Parcels in ?le-de-France
Real-estate premiums and the Zéro Artificialisation Nette law limit greenfield construction, forcing data center investors either into costlier vertical builds or toward dispersed regional campuses. Government-vetted powered sites ease the shortage but often lack dense dark-fiber rings. The France data center rack market therefore leans on taller 48U designs that squeeze higher compute density into pricey footprints, as well as modular containerized racks deployable in secondary zones where utilities and skilled labor remain in flux.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full Rack Dominance Driven by Standardization
Full-rack cabinets captured 67.85% of 2025 revenue and continue to outpace other formats with an 18.55% CAGR through 2031. This commanding share of the France data center rack market stems from hyperscale mandates favoring uniform 48U and 52U templates, which simplify capacity planning and cut logistics costs. Operators pursuing 30 kW-plus densities further rely on full racks to spread coolant manifolds seamlessly across contiguous rows. Quarter- and half-rack footprints retain relevance for localized edge nodes, yet procurement managers increasingly redirect budget toward standardized full-rack bundles that ship with pre-integrated busbars, cable troughs, and liquid-cooling stubs.
Consistency dovetails with AI clusters demanding predictable airflow modeling. Schneider Electric’s NVIDIA partnership validates how fully enclosed columns enable repeatable thermal behavior across data halls, a design imperative when thousands of GPU servers run synchronous workloads. Therefore, the France data center rack market size attached to quarter-rack and half-rack variants remains capped by space-limited telecom huts and ancillary control rooms, whereas full-rack cabinets form the economic backbone of new hyperscale wings.


By Rack Height: 48U Emerges as AI-Optimized Standard
Although legacy 42U frames still account for 52.50% of the 2025 France data center rack market size, 48U units post a market-leading 19.02% CAGR to 2031. Height gains accommodate taller GPU sleds, redundant cable trays, and rear-door heat exchangers without breaching standard ceiling clearances. The France data center rack market share held by “other” ≥52U formats is small yet growing, especially inside greenfield AI labs eager to maximize compute per square foot.
AMD’s ZT Systems acquisition underscores the premium on carefully engineered vertical space that avoids recabling when nodes upgrade from air to liquid cooling. French facilities built before 2018 often lack the plenum depth for 52U cabinets, explaining the ongoing dominance of 42U in brownfield sites. New campuses, however, default to 48U in request-for-quotation documents, cementing this height as the median sweet spot between handling ergonomics and GPU density.
By Rack Type: Cabinet Security Drives Market Leadership
Cabinet racks claimed 74.74% revenue in 2025 and will log a 16.92% CAGR through 2031 as regulators scrutinize physical security across all critical-information infrastructure. The France data center rack market prizes locked, gasket-sealed doors that integrate biometric readers and audit logging, thereby easing SecNumCloud accreditation for sovereign-cloud operators. Open-frame alternatives still populate low-risk test labs due to superior airflow and lower cost but rarely pass final compliance checks for healthcare, fintech, or public-sector workloads.
Wall-mount units fill edge deployments such as traffic-camera aggregation points and smart-factory cells, yet their revenue contribution remains minor. Cabinet leadership is reinforced as operators chase electromagnetic-interference shielding to protect dense GPU boards running at boosted memory clocks. Vendors that pair sealed-door construction with hot-aisle containment kits observe rising attach rates, solidifying cabinet dominance within the France data center rack market.
By Data Center Type: Hyperscale Growth Reshapes Market Dynamics
Colocation incumbents maintained a 50.80% slice of revenue in 2025, but hyperscalers exhibit an 18.02% CAGR that is realigning capital allocation. Brookfield’s EUR 20 billion expansion via Data4 underscores hyperscaler influence over purchasing terms, dictating vendor qualifications and emphasizing rack pre-capitalization to accelerate white-space activation. Consequently, the France data center rack market size tied to hyperscalers could overtake colocation revenue before 2028.
Colocation operators are countering by bundling private-AI islands inside multi-tenant campuses, as evidenced by Equinix’s Dell-powered AI Factory rollout. Enterprise and edge categories together form a resilient niche, serving latency-sensitive industrial automation and regional content distribution. Yet hyperscale buyers dominate annual framework agreements, extracting volume discounts and pushing rack makers to shorten lead times to under eight weeks.
By Material: Aluminum Gains Ground in High-Density Applications
Steel retained 73.60% of 2025 revenue given its strength-to-price ratio, yet aluminum climbs at a 16.98% CAGR as floor-loading constraints interact with heavier GPU sleds. Operators targeting 3,000-lb rack loads view aluminum frames that trim mass by up to 40% as insurance against costly slab reinforcement. The France data center rack market now sees new RFPs pairing aluminum exoskeletons with steel mounting rails, offering hybrid mechanical performance.
Embodied-carbon disclosure under EU taxonomy rules also nudges buyers toward aluminum, which carries a lower CO? coefficient when sourced from French hydro-powered smelters. Supply-chain resilience remains a watch item because aerospace and automotive sectors compete for the same alloys. Nevertheless, aluminum’s thermal conductivity advantages help dissipate localized GPU heat, a trait that resonates with AI cluster designers forced to limit heat flux across densely packed PCBs.
Geography Analysis
The nuclear-heavy French grid provides average lifecycle carbon intensity below 55 gCO?/kWh, allowing operators to advertise near-zero-carbon compute, a differentiator against Germany or Poland. ?le-de-France still hosts roughly 60% of national IT power but faces EUR 40,000-per-MW grid-deposit requirements that tilt new-site economics toward provincial parcels. Land scarcity elevates ceiling heights and PUE optimization, reinforcing adoption of taller 48U cabinets in the heart of Paris.
Secondary territories such as Hauts-de-France and Normandy lure investors with sub-EUR 90 per m? annual land leases and direct fiber backhaulinto London and Amsterdam, creating fresh addressable demand pockets for the France data center rack market nordfranceinvest. Marseille’s critical role as a Mediterranean cable landing hub translates into rack orders purpose-built for high moisture and saline environments. Sophia Antipolis near Nice has become France’s “AI Riviera,” where facilities like Evroc’s 96-MW project plan to host 50,000 GPUs, cementing a regional preference for liquid-ready 48U and ≥52U cabinets.
Policy alignment further shapes geography. The forthcoming Business Simplification Bill proposes national-interest status for data centers, potentially overriding municipal opposition and accelerating permitting in underserved regions. Coupled with the government’s 35 shovel-ready, high-amp sites, this legislative shift spreads fresh rack deployments across nine regions, lessening Paris congestion while sustaining aggregate growth for the France data center rack market. Local authorities offering tax abatements for heat-reuse systems also tip procurement toward sealed cabinets able to integrate heat-exchanger coils directly at rack level.
Regulatory Landscape
France data center rack demand is shaped by a tightening mix of national energy-efficiency rules, environmental reporting, and site-permitting frameworks that influence enclosure selection, metering, and physical-security features. Under the French Energy Code (Articles L.236-1 to L.236-3), operators must align energy-efficiency practices with the transposition of EU Directive 2023/1791, which reinforces procurement of racks that support granular power monitoring and higher-density thermal architectures.
On reporting and environmental compliance, Arcep requires annual environmental data collection from data center operators that meet defined thresholds (including at least EUR 10 million revenue in France or at least 100 kW IT power). Depending on the setup, auxiliary systems can fall under the ICPE (Installations Classees pour la Protection de lEnvironnement) regime within the Environmental Code. In April 2026, Article 15 of the Economic Simplification Act introduced a route for certain data centers to obtain PMNI status (project of major national interest), shifting permitting authority toward prefectural levels and linking the acceleration objective to grid-connection processes involving RTE. This structure can shorten administrative timelines for new halls and supports cabinet and full-rack rollouts.
Value Chain Analysis
The France data center rack value chain begins with raw materials and subcomponents, including steel and aluminum structures, fasteners, doors and locking systems, cable management, PDUs and busbars, sensors, and thermal interfaces. These components are assembled into frames and enclosed cabinets, then configured to customer specifications such as 42U to 48U heights and liquid-cooling readiness. Manufacturing and system design are anchored by global and European suppliers with French commercial footprints, including Rittal (IT enclosures and climate control systems), Legrand (data center electrical and digital infrastructure via brands such as Minkels, Raritan, and Server Technology), and Schneider Electric (energy management, automation architectures, and data center power and cooling solutions).
Downstream, racks move through distributors and integrators before deployment by colocation providers, hyperscale and cloud service providers, and enterprise or edge operators. Installation, commissioning, and lifecycle services, such as retrofits for higher-density cooling, security upgrades, and ongoing monitoring, account for a growing share of delivered value. As operators align with energy-efficiency obligations and Arcep environmental reporting, demand shifts toward rack-level telemetry, secure cabinet configurations, and standardized designs that simplify maintenance across multi-site estates.
Competitive Landscape
The France data center rack market remains moderately consolidated, with Schneider Electric, Vertiv, and Legrand together holding about 38% of 2024 sales. Schneider’s EcoStruxure racks penetrate hyperscale contracts by bundling liquid-cooling manifolds and microgrid-ready power distribution. Vertiv counters through prefabricated modular rows that shrink installation cycles. Legrand leverages domestic production to shorten supply chains and align with souveraineté numérique initiatives [2]Legrand Group, “FY 2024 Results Presentation,” legrandgroup.com.
Technological differentiation now trumps pure cost. Schneider Electric’s December 2024 co-engineered NVIDIA blueprint supports 132 kW liquid-cooled racks, enabling immediate AI workload absorption. Vertiv joined the Net Zero Innovation Hub to pilot hydrogen backup modules, targeting zero-diesel footprints that attract sustainability-minded European cloud buyers. Metal-fabrication newcomers, meanwhile, market aluminum frames with integrated drip-less quick disconnects, invoking both weight and serviceability advantages to chip away at steel incumbents.
Partnership strategy intensifies. Equinix’s global alliance with Dell pushes private AI nodes into colocation halls, influencing rack demand for pre-wired GPU sleds and security-sealed doors. AMD’s purchase of ZT Systems grants silicon-to-rack vertical integration, signaling that processor vendors consider cabinet engineering pivotal for end-to-end AI performance. Collectively, these moves place innovation velocity and compliance alignment at the center of competition within the France data center rack market.
France Data Center Rack Industry Leaders
-
Schneider Electric SE
-
Legrand S.A.
-
Eaton Corporation
-
Vertiv Group Corp.
-
Rittal GmbH and Co. KG
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Accelerated permitting and grid-connection facilitation improves the timing visibility for new data halls and expansions. That creates whitespace for standardized, rapid-deploy rack programs and modular accessories that reduce time-to-live capacity. The April 2026 Economic Simplification Act introduced PMNI status for certain data centers, moving permitting toward prefectural handling and explicitly linking streamlining to RTE-related connection processes, which benefits suppliers that can deliver repeatable cabinet configurations, documentation packs, and installation kits aligned to fast-track project schedules.
AI-driven builds and national investment programs are also widening the addressable scope for high-density, liquid-ready rack ecosystems beyond traditional enterprise refresh cycles. Public commitments linked to the 2025 Paris AI Summit referenced EUR 109 billion of private investments aimed at establishing data centers, while supplier-side moves point to an equipment stack shifting toward integrated power, cooling, and rack solutions for AI halls. In this context, opportunities are concentrated in 48U and higher cabinets with pre-plumbed liquid interfaces, rack-level power distribution engineered for dense GPU loads, and compliance-oriented physical security features that help operators meet energy-efficiency and environmental reporting requirements without extensive custom engineering.
Recent Industry Developments
- June 2026: Vertiv Group Corp. completes thermal management modernization at France sovereign data center, delivering 20% cooling power reduction for high-density AI workloads. The upgrade improves efficiency and capacity for AI workloads in French sovereign data centers, supporting sovereign-cloud ambitions and high-density rack deployments.
- May 2026: Schneider Electric SE partners with SoftBank Group to lead a 5 GW AI data center capacity buildout in France, including a new power-module factory at the Port of Dunkirk. The collaboration accelerates France AI data center capacity expansion with localized power and rack module production, reinforcing turnkey AI-ready infrastructure capability.
- April 2026: Legrand S.A. acquires TES in the United Kingdom to strengthen its datacenter power distribution systems portfolio. The move broadens Legrand’s European data center footprint and product integration with UK-based PDU capabilities, aligning with sovereign and EU data-center initiatives.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the France data center rack market covers revenue from racks used to mount and organize IT and network equipment inside data centers located in France. The value is measured where racks are supplied to end users or through channel partners, in current USD.
Scope exclusions: This sizing excludes broader data center build costs such as power and cooling equipment, civil construction, and facility operations services.
Segmentation Overview
-
By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
-
By Rack Height
- 42U
- 45U
- 48U
- Other Heights (?52U and Custom)
-
By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
-
By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
-
By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market boundaries and connect rack demand to measurable data center activity in France. We referenced public sources such as Eurostat for macro and trade context, INSEE for national economic indicators, and French customs trade statistics where product-level flows can be used to sense hardware movements.
To keep assumptions grounded, supporting reads were taken from sources such as the International Energy Agency for electricity context, OECD digital indicators, and patent databases to sanity-check design shifts in racks and enclosures. Company filings, product catalogs, and investor presentations helped confirm typical configurations and pricing bands, and we also used paid subscriptions for company financials and shipment-level trade checks where public splits were not detailed enough. This list is illustrative only, and additional public and paid sources were reviewed for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on validating what is being bought in France, how orders are timed, and how pricing changes with configuration mix and lead times. We spoke with a mix of rack manufacturers, distributors, integrators, and data center operators, then used those inputs to confirm demand patterns across enterprise sites, colocation halls, and newer capacity additions around major metro clusters.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 31% | CXOs: 16% |
| Mid tier: 52% | Functional/Unit leaders: 40% |
| Smaller Players: 17% | Managers: 44% |
Market-Sizing & Forecasting
Sizing started from a top-down build that reconstructs France rack demand from the installed and planned rack base in data halls, and then applies refresh and expansion cycles to translate that footprint into annual spend. Once that demand pool is framed, results are checked with selective bottom-up approximations using sampled average selling prices multiplied by typical unit volumes observed through channel discussions and integrator order patterns.
Key inputs that shaped the model included the cadence of new data hall commissioning, the mix shift between standard racks and higher-density rack needs, typical rack utilization per white space area, lead time driven buying behavior, and price movement tied to steel and freight trends. Forecasts were extended using scenario analysis, where the base case is adjusted by expected capacity additions and procurement timing discussed in interviews, and then smoothed to avoid unrealistic step changes. Where a bottom-up view had gaps, especially for smaller deployments, we used conservative ranges and normalized them against the validated national demand pool before finalizing totals.
Data Validation & Update Cycle
Model outputs are cross-checked against independent indicators, including data center capacity announcements, import patterns for relevant hardware categories, and operator commentary on expansion timing. When outputs drift from these signals, assumptions are revisited, and follow-up calls are triggered to re-check pricing, mix, or cycle timing.
Before sign-off, the work goes through multi-step analyst review, including variance checks across years and a logic review of drivers that should move together, such as capacity additions and rack unit demand. Reports are refreshed annually, with interim updates when material events impact build activity or supply conditions, and a final pre-delivery pass is completed so clients receive the latest view.
麻豆视频's France Data Center Rack Market Sizing Compared With Other Published Estimates
Published market sizes for France data center racks can look far apart because the counting rules are not always the same, even when the topic name sounds similar. Differences usually come from what is counted as a rack, whether installation and integration services are bundled with hardware, and how base-year pricing and currency conversion are handled.
The table shows a clear spread, and in 麻豆视频's model the value is limited to rack hardware revenue supplied into France, with adjacent items like installation services and wider data hall fit-out kept outside the total unless they are sold as part of the rack unit itself.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 46.31 M (2025) | |
| Regional Consultancy A | USD 167.43 M (2025) | Uses a wider bundle that can fold in enclosure accessories, integration labor, and parts of data hall fit-out, which lifts the reported value beyond rack frames and cabinets. |
| Industry Publisher B | USD 5.17 B (2025) | Appears to apply a broader data center infrastructure definition and demand proxy, which can mix rack hardware with facility capex or IT equipment value, and that can inflate the market by an order of magnitude. |
Looking across the three figures, most of the gap can be explained by scope control and by keeping the model tied to observable unit demand and realistic pricing bands. By separating rack hardware from broader build and IT spending, the final estimate stays traceable to repeatable inputs that can be rechecked as France adds new capacity.


Key Questions Answered in the Report
What is the current value of the France data center rack market?
The market is valued at USD 53.73 million in 2026 and is forecast to reach USD 113.05 million by 2031.
Which rack size leads in France?
Full-rack cabinets account for 67.85% of 2025 revenue and expand at an 18.55% CAGR through 2031.
Why are 48U racks gaining traction?
They provide extra vertical space for liquid-cooling hardware and GPU servers, supporting AI clusters while fitting within existing ceiling clearances.
How fast is the hyperscale segment growing?
Hyperscale and cloud-service provider facilities are increasing rack purchases at an 18.02% CAGR, outpacing the broader market.
Page last updated on:
- Data Center Server Market Servers worldwide, split by tier, facility size and facility type.
- Data Center Security Market Security across the global market, covering security type, offering and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities worldwide, split by facility type, component and tier.
- Italy Data Center Power Market Italy's power systems, split by component, facility type and facility size.
- Italy Data Center Server Market Italy servers, split by facility size and tier.
- Canada Data Center Storage Market Storage demand across Canada, covering storage technology, storage type and facility type.
- Japan Data Center Power Market Japan's power systems, split by component, facility type and facility size.
- India Data Center Server Market Servers demand across India, covering form factor, processor architecture and deployment model.
- France Data Center Processor Market France's processors, split by facility size and tier.
- South America Data Center Construction Market South America's construction, split by tier.
- Europe Green Data Center Market Energy efficiency in Europe, split by component, facility type and tier.
- France Data Center GPU Market France GPUs, split by deployment type, gpu type and interconnect.



