
Germany Data Center Networking Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
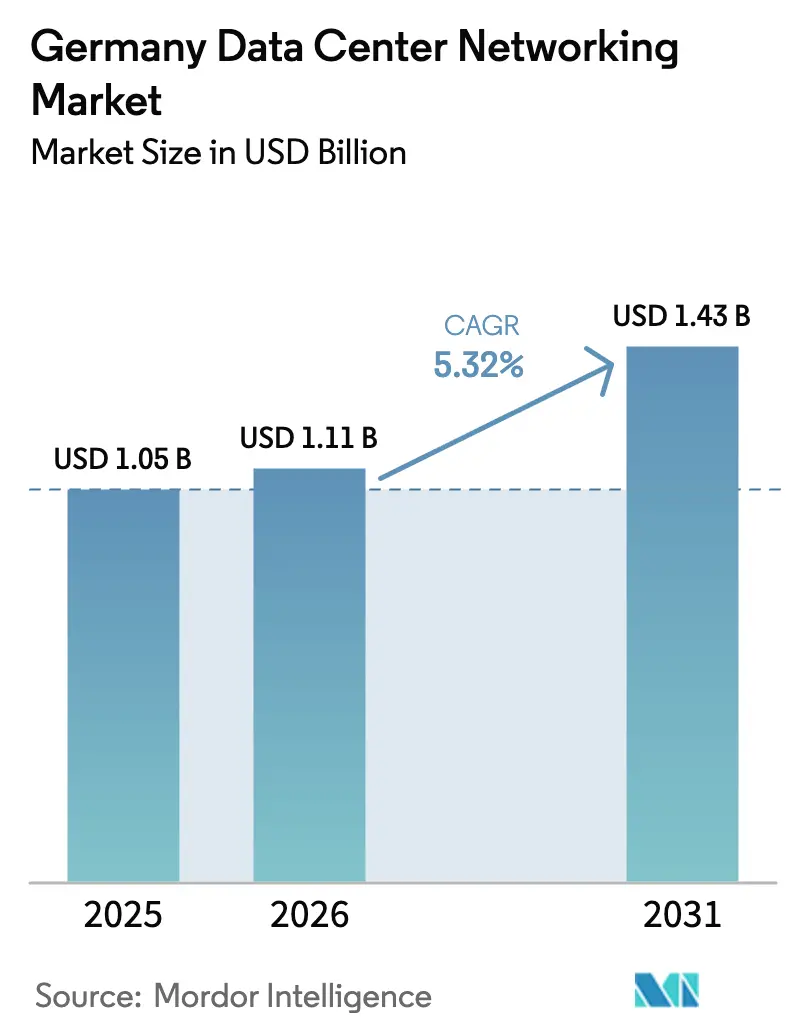
| Base Year Market Size (2025) | USD 1.05 Billion |
| Market Size (2026) | USD 1.11 Billion |
| Market Size (2031) | USD 1.43 Billion |
| Growth Rate (2026 - 2031) | 5.32 % |
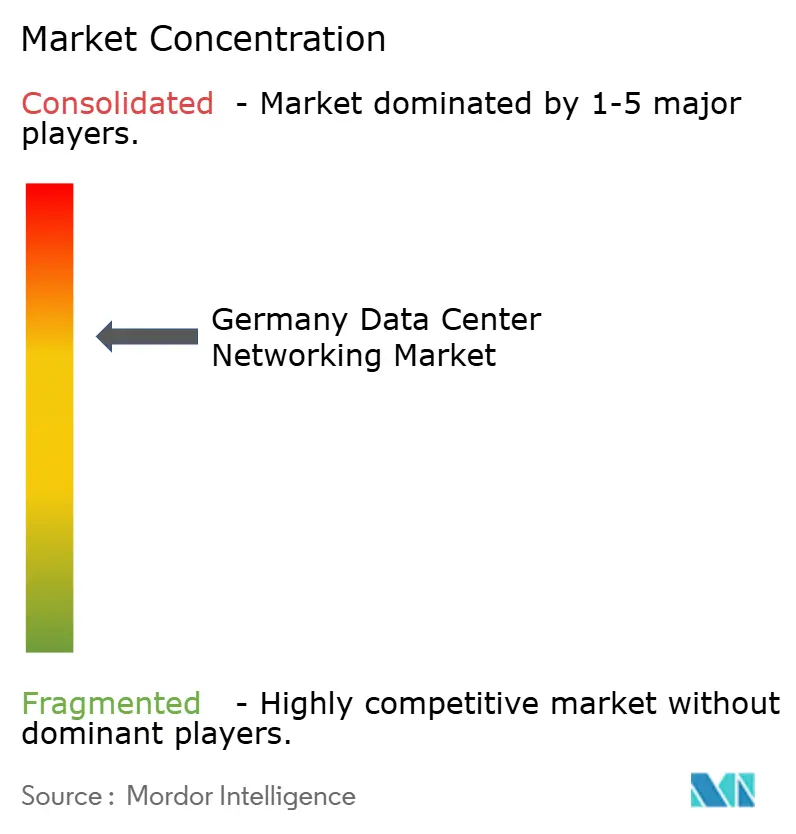
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Germany Data Center Networking Market Analysis by 麻豆视频
Germany data center networking market size in 2026 is estimated at USD 1.11 billion, growing from 2025 value of USD 1.05 billion with 2031 projections showing USD 1.43 billion, growing at 5.32% CAGR over 2026-2031. Hyperscale cloud providers are injecting multibillion-dollar capital into Frankfurt, Berlin, and Munich facilities, accelerating demand for next-generation 400G and 800G switching. Government mandates on fiber roll-out and renewable-energy sourcing tighten compliance deadlines, prompting early equipment refreshes. Rapid AI adoption across automotive, manufacturin,g and research drives a pivot from 25G or 100G architectures toward lossless fabrics that support large-scale GPU clusters. Liquid-cooling requirements, stricter PUE targets, and edge deployments in Industry 4.0 factories together shift spending toward high-efficiency, software-defined networks that can be managed by lean teams.
Key Report Takeaways
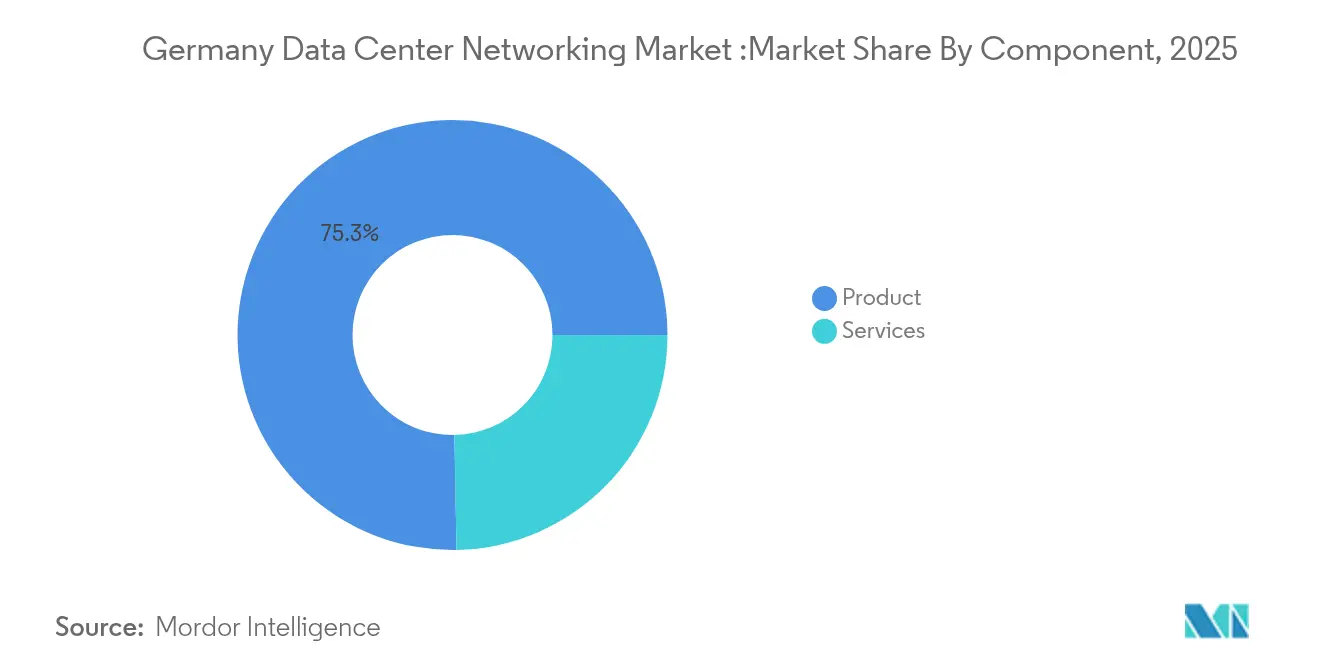
- By component, Products held 75.30% of Germany data center networking market share in 2025; Services post the highest 5.61% CAGR through 2031.
- By end-user, IT and Telecommunications commanded 35.20% share in 2025, while Manufacturing and Industrial is on track for a 6.05% CAGR to 2031.
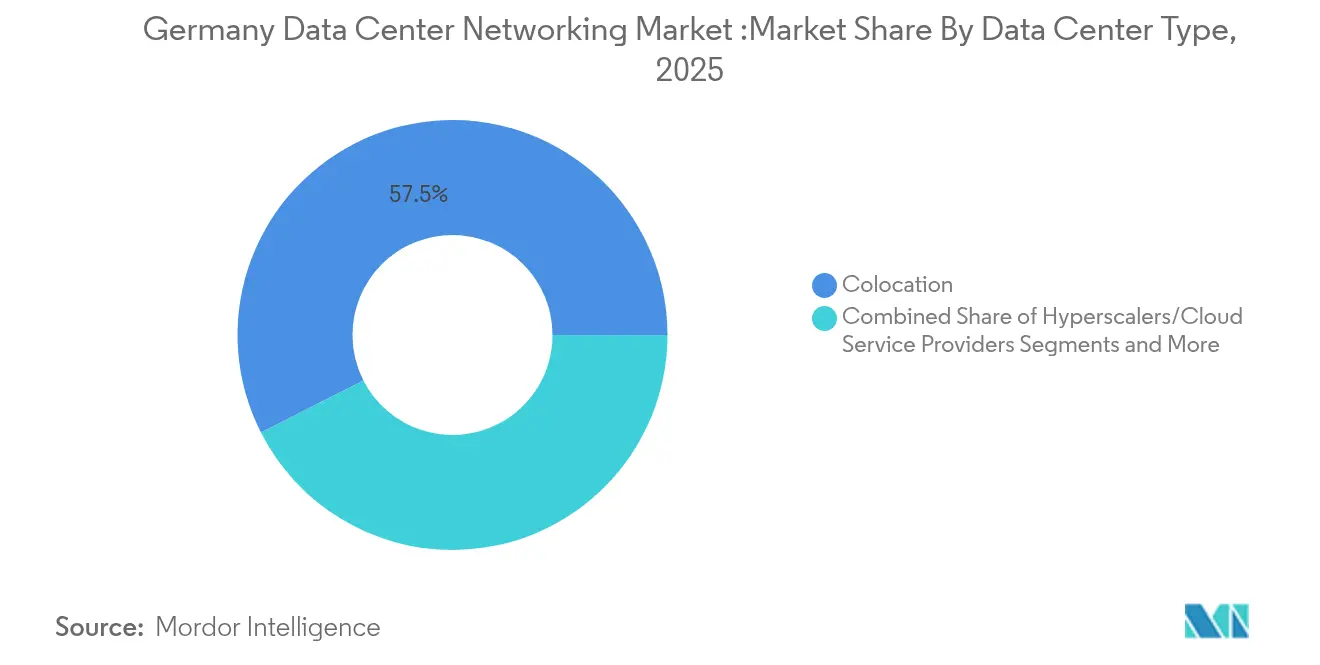
- By data-center type, Colocation led with 57.50% revenue share in 2025; Hyperscalers/Cloud Service Providers expand fastest at 7.68% through 2031.
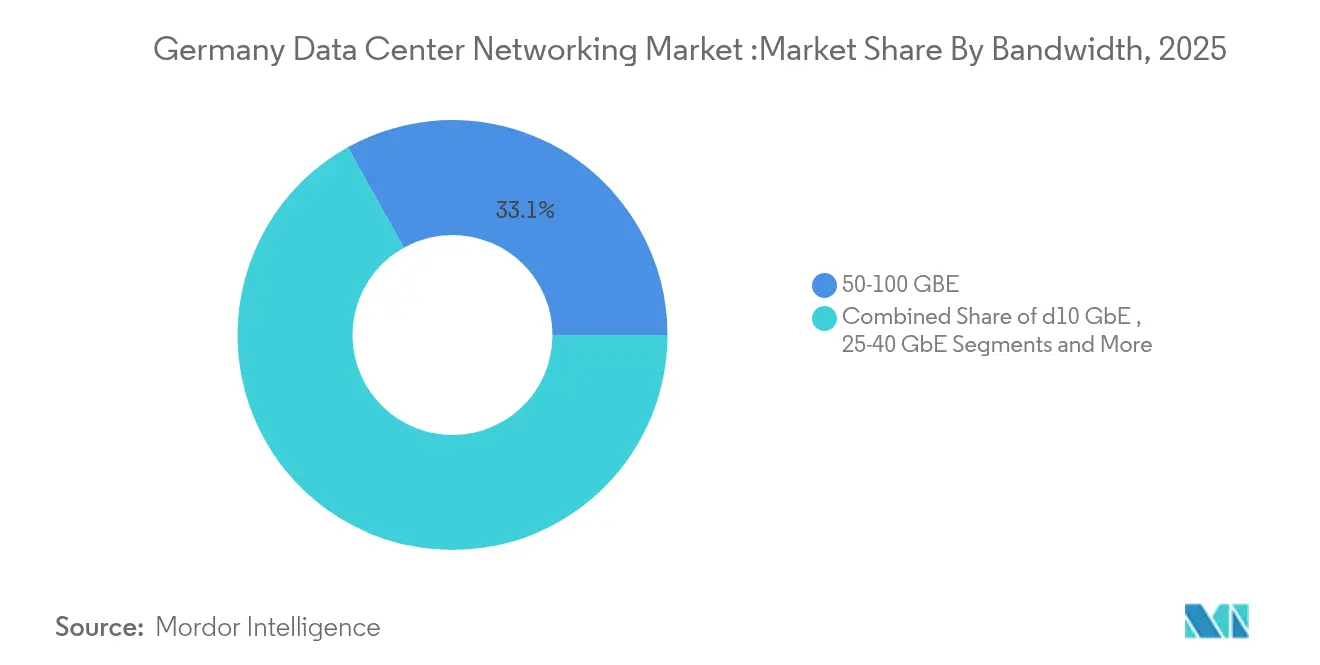
- By bandwidth, the 50–100 GbE segment accounted for 33.10% share of the Germany data center networking market size in 2025, whereas greater than 100 GbE registers a 7.05% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Germany Data Center Networking Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of hyperscale cloud and colocation footprints | +1.2% | Frankfurt, Berlin, Munich metro areas | Medium term (2-4 years) |
| Government Gigabit Strategy accelerating fiber amd 5G rollout | +0.8% | National, with priority in rural regions | Long term (≥ 4 years) |
| Surging AI/ML traffic driving 400G/800G switch refresh | +1.5% | Frankfurt data center corridor, major cities | Short term (≤ 2 years) |
| Rising edge-data-center deployments for IoT/low latency | +0.7% | Industrial regions, automotive clusters | Medium term (2-4 years) |
| Mandatory waste-heat-reuse rules boosting liquid-cooled gear | +0.4% | National, concentrated in urban areas | Long term (≥ 4 years) |
| EU sovereign-AI grants funding InfiniBand clusters | +0.6% | Research centers, major universities | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Expansion of hyperscale cloud and colocation footprints
Hyperscalers are reshaping procurement cycles by specifying 800G-ready fabrics and InfiniBand clusters for AI training. AWS alone committed USD 9.44 billion to its Frankfurt region, pushing switch vendors to deliver high-density, liquid-cooling-compatible platforms. Colocation operators such as Digital Realty respond with AI-focused halls, drawing enterprise tenants that then require premium interconnects capable of multi-tenant segmentation. [1]Digitalrealty ,"Digital Realty Expands Frankfurt Footprint with AI-Optimized, Sustainable Data Center,"digitalrealty.com These parallel investments compress equipment lifecycles to under four years and create multiplier effects in secondary metros.
Government Gigabit Strategy accelerating fiber and 5G rollout
Berlin’s Gigabit Strategy funds EUR 17 billion (USD 19.93 billion) for nationwide fiber and 5G, obliging data-center owners to adopt higher-capacity interconnects that sustain rural back-haul traffic.[2]Federal Ministry of Transport, "Gigabit funding 2.0, "bmv.deGrants stipulate adherence to BSI C5 security rules, steering demand toward vendors with European manufacturing lines. Fiber densification also enables distributed edge nodes that rely on software-defined overlays to link new regional facilities with Frankfurt’s internet exchanges.
Surging AI/ML traffic driving 400G/800G switch refresh
Deutsche Telekom’s planned industrial AI cloud with 10,000 GPUs exemplifies the throughput jump that legacy 100G leaf-spine designs cannot support. [3]Deutsche Telekom AG. " AI Turbo for Gigafactories: Telekom announces European Industrial AI Infrastructure with NVIDIA." telekom.com Automotive OEMs integrating real-time vision analytics insist on lossless fabrics with RDMA, driving adoption of InfiniBand and Spectrum-X Ethernet solutions. Research clusters such as the Blue Lion supercomputer propel early trials of 800G optics, anchoring Germany data center networking market demand at the high-bandwidth end.
Rising edge-data-center deployments for IoT/low latency
Industry 4.0 roll-outs in Baden-Württemberg and the Ruhr require ruggedized switches that tolerate factory temperatures yet provide enterprise-grade telemetry. Private 5G licences issued to automotive groups combine OT and IT traffic, increasing reliance on SDN controllers that map deterministic paths. Edge nodes also host CDN caches, steering traffic away from Frankfurt backbones and reshaping traffic engineering policies across national routes.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Energy-grid constraints and high electricity costs in FLAP-D | -0.9% | Frankfurt, major metropolitan areas | Short term (≤ 2 years) |
| Shortage of certified network-automation engineers | -0.6% | National, acute in tech hubs | Medium term (2-4 years) |
| Data-sovereignty (BSI C5) limits foreign white-box adoption | -0.3% | National, critical infrastructure sectors | Long term (≥ 4 years) |
| Optical-fiber raw-material shortages delaying builds | -0.4% | National, supply chain dependent | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Energy-grid constraints and high electricity costs in FLAP-D
Frankfurt’s power caps force operators to distribute AI loads across multiple smaller halls, inflating port counts and cabling runs. The Energy Efficiency Act sets a PUE ceiling of 1.3 by 2030, pushing buyers toward higher-price, low-watt ASICs and liquid-cooled optics that lengthen ROI horizons. Renewable-power sourcing adds spatial constraints because solar or wind adjuncts consume land that could host additional racks.
Shortage of certified network-automation engineers
SDN and AI fabrics demand skills in RoCE, Ansible and P4-programmable pipelines that remain scarce. Hyperscale salary premiums drain talent from regional colocation and enterprise facilities, prolonging deployment timelines. SMEs increasingly outsource to managed-service specialists, raising operating expenditure and tempering adoption speed for advanced telemetry features.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Component: Products anchor investment while Services accelerate
Products held 75.30% of Germany data center networking market share in 2025 of Germany data center networking market size. Switch refresh programs shift toward 400G and 800G platforms, and optical interconnect uptake scales with liquid-cooling aisle designs. SDN controller licenses rise as operators centralize management for metro-edge fabrics. Services are forecast to expand at a 5.61% CAGR, adding recurring revenue streams tied to AI-cluster optimisation and IPv6 migration. Managed Network Services absorb the skills gap, while integration specialists link private-5G cells to core data-center fabrics. Training programs see uptake as enterprises re-tool teams for GPU-centric traffic patterns. This mix elevates service spend from 2025 onward, yet hardware outlays remain dominant through 2030 in the Germany data center networking market.


By End-User: Manufacturing’s fast climb challenges IT incumbency
IT and Telecommunications continued to command 35.20% of Germany data center networking market share in 2025, anchored by carriers upgrading core routers for 5G and cloud providers scaling AI regions. DORA compliance bolsters switch-level segmentation and telemetry in financial data centers.Manufacturing and Industrial is projected to register 6.05% CAGR, outpacing all peers. Private 5G at facilities like Tesla’s Gigafactory creates micro-data-centers adjacent to production lines, each demanding low-latency fabrics. Factories integrate OT sensor grids with IT analytics, necessitating deterministic traffic engineering and redundant edge aggregation layers that lift spending per square meter.
By Data-Center Type: Hyperscalers narrow the gap with colocation
Colocation retained 57.50% share of Germany data center networking market size in 2025,. Tenants span fintech, government and media workloads that mandate sovereign hosting. Operators invest in spine-leaf topologies and SDN overlays to guarantee tenant isolation. Hyperscalers plot an 7.68% CAGR to 2031. Multi-billion-euro campuses specify custom ASICs, leafless fabrics and integrated liquid cooling. Their procurement volumes reshape supplier roadmaps and introduce open compute specifications, influencing wider market standards across the Germany data center networking market.
By Bandwidth: High-speed tiers gain momentum
The 50-100 GbE category accounted for 33.10% revenue in 2025 but faces gradual decline as AI workloads proliferate. Enterprises cling to 100 GbE for virtualisation clusters yet schedule upgrades before 2028 to meet hybrid-cloud latency objectives.Ports above 100 GbE post a 7.05% CAGR. Early 400G deployments in research supercomputers validate scalability, and 800G pilots begin within automotive AI labs. Optics vendors accelerate qualification cycles, pushing coherent-optical roadmaps that support inter-campus dark-fiber links across the Germany data center networking market.
Geography Analysis
Frankfurt anchors traffic flows, hosting DE-CIX peaks of 25 Tbps that necessitate continual spine uplifts and resilient routing. Hyperscalers’ region-build outs cluster at this nexus, driving multi-year purchase agreements for high-density switches and modular optics. Grid capacity limits and rising power tariffs encourage satellite deployments in Rhine-Main towns, yet connectivity gravity keeps Frankfurt dominant.Berlin forms the political and emerging tech twin-hub. Government cloud workloads and sovereign-AI projects foster demand for certified European equipment, steering procurement toward vendors with local assembly lines. Edge nodes sprout around Brandenburg’s automotive plants, each linking back to Berlin data-centers through dark-fiber rings that support real-time analytics.Munich benefits from aerospace and research institutions. The Blue Lion supercomputer anchors a regional 800G testbed, shaping early procurement of next-generation fabric ASICs. Bavaria’s renewable mix attracts sustainability-minded operators, though distance to Frankfurt’s exchange points raises dependence on coherent-optical gear.
Regulatory Landscape
Germanys data center networking demand is increasingly shaped by energy-efficiency and reporting requirements under the Energy Efficiency Act (EnEfG) and by federal policy direction. The Federal Ministry for Economic Affairs and Energy (BMWK) adopted a National Data Center Strategy on 18 March 2026, linking sector expansion to tighter sustainability and resilience requirements that affect network refresh cycles (for example, higher-efficiency switch silicon, telemetry for energy reporting, and more granular segmentation for compliance-driven operations).
EnEfG also sets facility-level obligations that cascade into networking architecture and operations. An energy efficiency register (DCReg) applies to data centers with a non-redundant rated electrical load of at least 300 kW, increasing the need for instrumented networks that can support auditable metering and workload placement. A draft EnEfG amendment proposed on 9 April 2026 addresses PUE limits and simplified waste-heat reporting, including proposed PUE thresholds of 1.3 for new data centers after 1 July 2026, and 1.6 from 1 July 2027 and 1.4 from 1 July 2030 for existing facilities. These thresholds raise the premium on power-optimized fabrics and operations tooling.
Competitive Landscape
Market structure is moderately concentrated. Cisco leverages a broad enterprise base yet faces rising share loss to Arista in AI-centric engagements. Arista’s Cluster Load Balancing and 800G roadmaps position it to capture hyperscale refreshes. NVIDIA extends vertical integration through Mellanox silicon and Spectrum-X, embedding itself in GPU cluster designs.
Vendor strategies hinge on alliances. Cisco’s silicon integration partnership with NVIDIA aligns Ethernet and InfiniBand under unified management stacks. HPE’s planned acquisition of Juniper seeks to combine compute and networking portfolios, targeting edge-to-cloud consistency demanded by German manufacturers. European regulations around supply-chain provenance give ADVA Optical and Nokia an edge in critical-infrastructure bids.
Germany Data Center Networking Industry Leaders
-
Cisco Systems Inc.
-
Juniper Networks Inc.
-
VMware Inc.
-
Huawei Technologies Co. Ltd.
-
Extreme Networks Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
The March 2026 National Data Center Strategy creates space for vendors and integrators that can package compliance-ready, high-efficiency networking stacks for new builds and retrofits. With the strategy targeting a doubling of national data center capacity by 2030 and a quadrupling of AI/HPC capacity by 2030, operators pursuing 400G/800G-ready switching, lossless fabrics, and optical interconnects are also buying software-defined networking controllers and observability tools to scale larger fabrics with lean teams. This aligns with the shift toward AI-centric networking in Germany, reflected in Deutsche Telekoms industrial AI cloud plan (10,000 GPUs, announced June 2025), which increases demand for deterministic, high-throughput east-west connectivity.
A second opportunity cluster is tied to energy and grid constraints that push operators toward distributed halls and more edge deployments, which then increases inter-campus connectivity needs and the demand for secure multi-tenant segmentation. EnEfGs DCReg reporting obligations for facilities above 300 kW also drive procurement of automation, telemetry, and managed network services that simplify evidence collection and day-to-day operational control. There is further room for joint go-to-market offerings between data center operators and energy suppliers, with system integrators delivering end-to-end designs that meet both AI training performance requirements and the documented energy-efficiency and reporting expectations under BMWK oversight.
Recent Industry Developments
- April 2026: MR Datentechnik expanded its IT portfolio to include Juniper Networks enterprise networking, data center architectures, and security solutions. The expansion strengthens Juniper presence in German enterprise and data center segments and broadens AI-ready networking capabilities.
- March 2026: Cisco expanded its Secure AI Factory collaboration with NVIDIA, integrating Nexus Hyperfabric and N9100 switches to accelerate AI infrastructure deployment. The collaboration reinforces Cisco and NVIDIA positions in the German AI-centric data center market.
- February 2026: Cisco announced the Silicon One G300 switching chip with 102.4 Tbps capacity for AI clusters and hyperscale network builders, with systems expected in the second half of 2026. This advances next generation data center switching and could drive demand in Germany data center networks.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market covers revenue earned in Germany from data center networking equipment and related software that enable connectivity inside and between data centers, including switching and routing used for data center traffic.
Scope exclusions: We exclude general enterprise LAN campus networking, end user devices, and carrier wide-area network buildouts that are not purchased for data center use cases.
Segmentation Overview
-
By Component
-
Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
-
Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
-
Products
-
By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
-
By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
-
By Bandwidth
- Less than 10 GbE
- 25-40 GbE
- 50-100 GbE
- Greater Than 100 GbE
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts by building a fact base on Germany data center build activity and traffic drivers, which then anchors the networking demand pool. We rely on public and official sources such as Destatis releases, Bundesnetzagentur publications, Eurostat digital and ICT series, and customs trade statistics. We also pull reference and technical context from standards and reference materials from bodies such as ETSI or IEEE.
To connect capacity growth to networking spend, we review annual reports and investor presentations of relevant ecosystem participants, along with reputable press coverage on new data center halls and major expansions. In parallel, we reference paid subscriptions for company financials and intelligence, news and financials, patent databases, and shipment-level import-export checks when clarification is required. This desk research list is illustrative only, and we reviewed many other sources for data capture, cross-checking, and interpretation.
Primary Interviews and Surveys
Primary interviews and surveys are used to test the sizing logic against what buyers and solution partners are seeing in live projects across Germany. We spoke with a mix of operators, system integrators, distributors, and technical specialists who could comment on refresh cycles, port-speed transitions, and typical bill-of-material patterns, which then helped tighten assumptions. Since this is a single-country market, coverage is balanced across major metro hubs and secondary locations where new capacity is being added.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 33% | CXOs: 14% |
| Mid tier: 53% | Functional/Unit leaders: 29% |
| Smaller Players: 14% | Managers: 57% |
Market-Sizing & Forecasting
Sizing starts from a top-down demand reconstruction, where Germany data center capacity additions and network architecture shifts are translated into equipment spending by applying penetration and refresh assumptions. Only after the demand pool is built do we test it with selective bottom-up checks, such as sampled configurations for spine-leaf builds, channel feedback on shipment mix, and average selling price (ASP) by port speed to correct obvious gaps.
Key inputs for this market include announced and under-construction data center capacity, typical leaf and spine switch counts per new hall, adoption of 100G, 200G, 400G, and early 800G ports, optical transceiver attach rates, and refresh timing tied to energy efficiency and density upgrades. Where data is incomplete, we use conservative proxy ratios that are validated through interviews, then stress-test them against import-export signals and supplier revenue splits.
For forecasting, we use scenario analysis supported by trend smoothing. The base case follows expected capacity commissioning, while alternative cases reflect slower permitting or faster density upgrades. The final forecast path is accepted after ensuring the key variables, especially ASP progression and port-speed mix, align with what industry respondents expect over the next few years.
Data Validation & Update Cycle
Outputs are validated through multiple checks so the results stay explainable and repeatable. We compare model totals against independent indicators such as capacity growth, trade flows for relevant equipment categories, and the implied spend per MW, then review and correct outliers before sign-off.
Each report goes through step-by-step analyst review, and we re-contact respondents when a major variance shows up or when a large project announcement shifts the local pipeline. Reports are refreshed annually, and interim updates are added if a material event changes pricing, procurement timing, or commissioning schedules. Before delivery, we run a final pass so clients receive the most current view available at that time.
麻豆视频's Germany Data Center Networking Market Size Compared Against Other Published Estimates
Published market values for Germany data center networking can look far apart because the underlying timelines and pricing mechanics are not always aligned. Differences often come from whether the estimate treats multi-year projects as booked at once, how it converts euro-denominated deals into USD, and how it accounts for price declines as port speeds move from 100G toward 400G and beyond.
In refresh-led tracking, the biggest spread usually shows up when older ASP points are carried forward without a clean reset to the latest quarters, or when a model includes adjacent IT items like servers, storage, or facility infrastructure. Currency timing also matters because using a single annual average rate versus a more recent rate can move a USD market value even if unit demand is unchanged, and these choices often do not get explained in short public summaries.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 1.05 B (2025) | |
| Industry Research Publisher A | USD 0.76 B (2025) | Often scoped tightly to data center switches, which leaves out routing, optics-related networking spend, and some software functions, and it can apply a faster ASP decline curve that pulls down the 2025 value. |
| Trade Portal B | USD 1.23 B (2026) | May use a forward-leaning year with optimistic commissioning assumptions, and it can convert EUR to USD using a different point-in-time rate, which lifts the reported USD value for the same demand signal. |
The table mainly shows how scope boundaries, price-refresh timing, and currency conversion choices change the headline number. By resetting ASPs to recent selling conditions and re-checking them during the annual refresh cycle, then applying the same currency timing rules across the series, 麻豆视频 reduces noise that can come from older price points and inconsistent conversions.


Key Questions Answered in the Report
What is the size of the Germany data center networking market in 2026?
The market stands at USD 1.11 billion in 2026.
What compound annual growth rate (CAGR) is forecast for the market through 2031?
A 5.32% CAGR is projected between 2026 and 2031.
Which bandwidth segment is expanding the fastest?
Ports above 100 GbE, driven by 400G and 800G adoption, are growing at a 7.05% CAGR.
Why are hyperscale providers channeling large investments into Frankfurt?
Frankfurt hosts DE-CIX’s 25 Tbps traffic peak and offers dense fiber interconnects, making it ideal for AI-ready, high-bandwidth cloud regions.
Page last updated on:
- France Data Center Networking Market
- South Korea Data Center Networking Market
- India Data Center Networking Market
- United Kingdom Data Center Networking Market
- Japan Data Center Networking Market
- Canada Data Center Networking Market
- Brazil Data Center Networking Market
- China Data Center Networking Market
- Spain Data Center Networking Market
- Mexico Data Center Networking Market
- Italy Data Center Networking Market
- Data Center Server Market Servers across the global market, covering tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities worldwide, split by facility type, component and tier.
- Data Center Construction Market Global construction demand, split by tier, facility size and facility type.



