
Hand Blender Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Market Size (2026) | USD 4.08 Billion |
| Market Size (2031) | USD 5.17 Billion |
| Growth Rate (2026 - 2031) | 4.84 % |
| Largest Market | Asia |
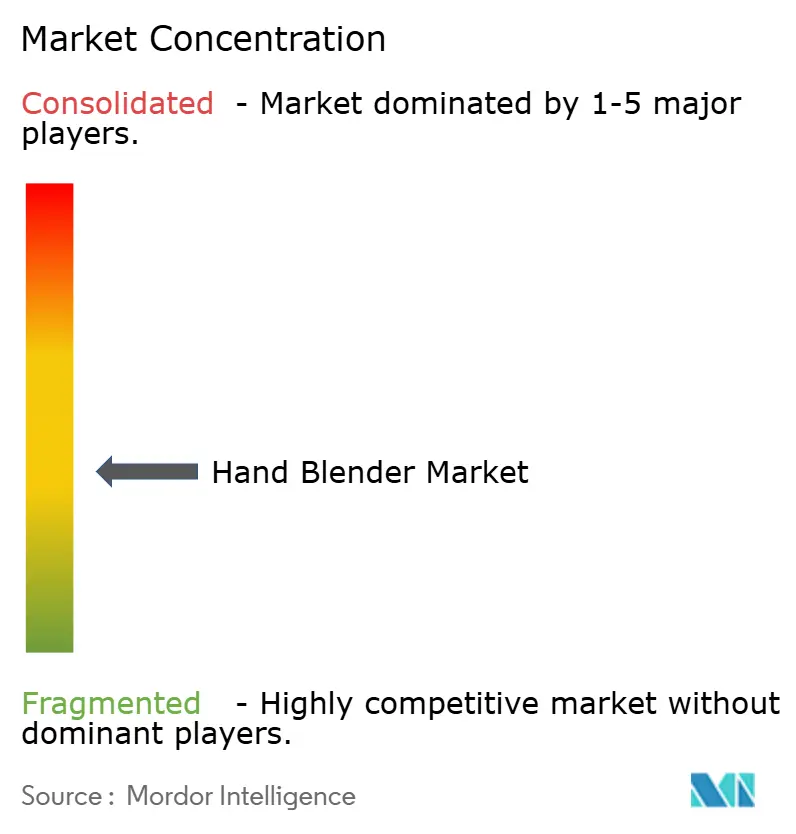
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Hand Blender Market Analysis by 麻豆视频
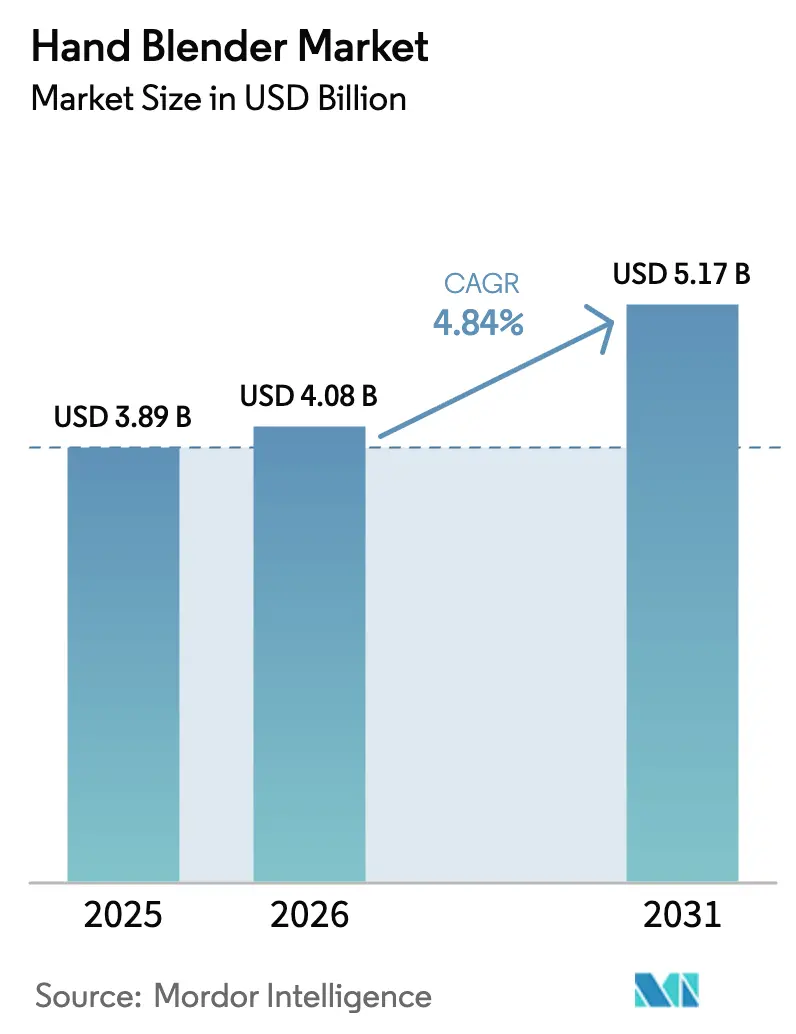
The global hand blender market size is expected to grow from USD 3.89 billion in 2025 to USD 4.08 billion in 2026 and is forecast to reach USD 5.17 billion by 2031 at 4.84% CAGR over 2026-2031. Steady gains come from urban living trends, lithium-ion cordless innovations, and greater preference for compact, multifunctional tools that suit smaller kitchens. The modest growth rate also signals resilience, given recent component shortages and tougher safety regulations that have affected many small appliance categories. Manufacturers continue to prioritize battery management systems, attachment versatility, and premium build quality to protect margins while broadening geographic reach. Strategic opportunities exist in Asia-Pacific’s fast-expanding urban centers, premium price tiers in mature markets, and commercial settings such as ghost kitchens that need portable blending equipment.
Key Report Takeaways
- By product type, corded models led with 61.54% of hand blender market share in 2025, whereas cordless units are projected to post the highest 7.55% CAGR to 2031.
- By end user, the residential segment accounted for 78.54% of the hand blender market size in 2025, while the commercial segment is set to expand at 7.31% CAGR through 2031.
- By distribution channel, offline retail held 55.98% of revenue in 2025; online retail shows the quickest 7.84% CAGR for 2026-2031.
- By price tier, mid-range products (USD 40-100) commanded 47.12% of the hand blender market size in 2025; premium units (>USD 100) lead growth with a 8.95% CAGR.
- By application, soups and sauces retained 33.98% share of the hand blender market size in 2025, while smoothies and beverages advance at a 7.18% CAGR.
- By geography, Europe led at 36.02% revenue share in 2025; Asia-Pacific is the fastest regional climber at 7.60% CAGR to 2031.
- The hand blender market exhibits moderate concentration with the top 5 players—KitchenAid (Whirlpool Corp.), Braun Household (De'Longhi Group), Philips Domestic Appliances (Versuni), Breville Group, and Cuisinart (Conair Corp.)—commanding significant market share in 2024.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Hand Blender Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing demand for compact appliances in urban kitchens | +1.2% | Global, concentrated in Asia-Pacific urban centers | Medium term (2-4 years) |
| Accelerating online retail penetration for small appliances | +1.0% | Global, led by North America and Europe | Short term (≤ 2 years) |
| Rapid innovation in cordless Li-ion hand blenders | +0.9% | Global, with early adoption in developed markets | Medium term (2-4 years) |
| Special-diet use cases (infant and elderly nutrition) | +0.7% | Developed markets, expanding to emerging economies | Long term (≥ 4 years) |
| Growth of ghost kitchens and small food-service formats | +0.6% | Urban centers globally, concentrated in Asia-Pacific | Short term (≤ 2 years) |
| Modular attachment ecosystems boosting upgrade sales | +0.5% | Premium segments in developed markets | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Growing Demand for Compact Appliances in Urban Kitchens
Dense housing and kitchen footprints of 50-70 sq ft in megacities are elevating the need for small, versatile tools, positioning hand blenders as space-efficient essentials. Developers of micro-kitchens in Tokyo, Mumbai, and London focus on modular layouts where every device must serve multiple uses. Consumers choose units with interchangeable accessories that swap whisking, chopping, and blending tasks while fitting into limited storage. The hand blender market therefore benefits from faster replacement cycles, as residents value devices that can adapt to restricted counter space. Retailers in Asia-Pacific urban clusters showcase compact appliance bundles, amplifying brand exposure and driving premium up-sell within the category. A mid-term sales tailwind emerges as urbanization spreads into Tier 2 cities that replicate the micro-home trend.
Accelerating Online Retail Penetration for Small Appliances
Digital storefronts enhance product storytelling through 360-degree views, live-stream demonstrations, and AI-driven comparison tools that clarify torque, noise, and runtime specifications. The online channel shortens decision cycles by aggregating verified user feedback and ease-of-return policies, nudging consumers toward affluent cordless SKUs. Subscription models for blades and seals add predictable income streams for brands while guaranteeing peak performance for users. North American and European buyers, already comfortable ordering high-ticket electronics online, are migrating small appliance purchases for the same convenience. The shift enables direct-to-consumer strategies that cut distribution layers and protect margins, a crucial gain amid rising production costs.
Rapid Innovation in Cordless Li-ion Hand Blenders
New cell chemistries now match corded peak wattage yet deliver 20-minute duty cycles, removing mobility constraints in kitchens without dedicated outlets. Brands are pairing optimized battery packs with high-efficiency brushless motors to sustain torque during viscous tasks such as nut butter or dough preparation. Supply chain volatility for lithium-ion cells, however, increases lead times and cost pressure, raising retail prices for premium cordless lines. Firms mitigate risk by dual-sourcing battery modules and developing proprietary management firmware that prevents over-discharge, extending product lifespan. The technology unlocks slimmer, more ergonomic handles that appeal to aging households seeking lightweight tools with reduced vibration.
Special-diet Use Cases (Infant and Elderly Nutrition)
Demographic shifts amplify demand for appliances able to produce fine, homogeneous textures suited to swallowing disorders and infant weaning. Hospitals and elder-care facilities integrate hand blenders into nutritional programs that require batch consistency and strict hygiene standards. Safety-certified plastics free of bisphenol A and intuitive one-hand controls cater to caregivers who need reliability under time constraints. Manufacturers are launching color-coded blades and jars to separate allergen-free and regular food preparation, reducing cross-contamination risk. Over the long term, the hand blender market sees new revenue from care-oriented SKUs with extended warranties and third-party validation from medical associations, lifting brand credibility.
Restraints Impact Analysis of Hand Blender Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Substitution threat from countertop blenders | -1.4% | Global, particularly in markets with larger kitchen spaces | Medium term (2-4 years) |
| Product-safety and durability recalls eroding trust | -1.1% | Global, with higher impact in regulated markets | Short term (≤ 2 years) |
| Li-ion battery supply constraints for cordless models | -0.8% | Global, affecting premium cordless segments | Short term (≤ 2 years) |
| Stricter energy-efficiency mandates raising costs | -0.6% | Europe and North America primarily | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Substitution Threat from Countertop Blenders
In regions where kitchens exceed 150 sq ft, owners gravitate toward high-horsepower countertop models that manage larger volumes and harder ingredients. Marketing for countertop blenders highlights full-jar stability and automated programs, diminishing the perceived value of handheld units. Retail promotions in North America often bundle countertop models with smoothie cups, reinforcing the one-appliance solution narrative. To counter the threat, hand-held brands spotlight precision control for small batches and direct-pot blending that avoids messy transfers. Designers also accentuate collapsible shafts that store in drawers, a feature that countertop machines cannot replicate.
Stricter Energy-Efficiency Mandates Raising Costs
Proposed Tier II eco-design rules in the European Union set maximum standby draw and minimum conversion efficiency benchmarks for all plug-in appliances [1]European Commission, “Ecodesign and Energy Labelling Working Plan 2022-2024,” ec.europa.eu. . Achieving compliance forces redesign around higher-grade magnetic materials, advanced power electronics, and low-resistance wiring. North American utilities encourage voluntary adoption of similar specifications through rebate schemes for energy-rated models. The hand blender market must manage a delicate price-feature balance, as cost increases may outweigh energy bill savings in buyers’ eyes. Manufacturers invest in lifecycle assessments to document emissions-reduction benefits, providing marketing support for higher prices.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Hand Blender Market Segment Analysis
By Product Type:
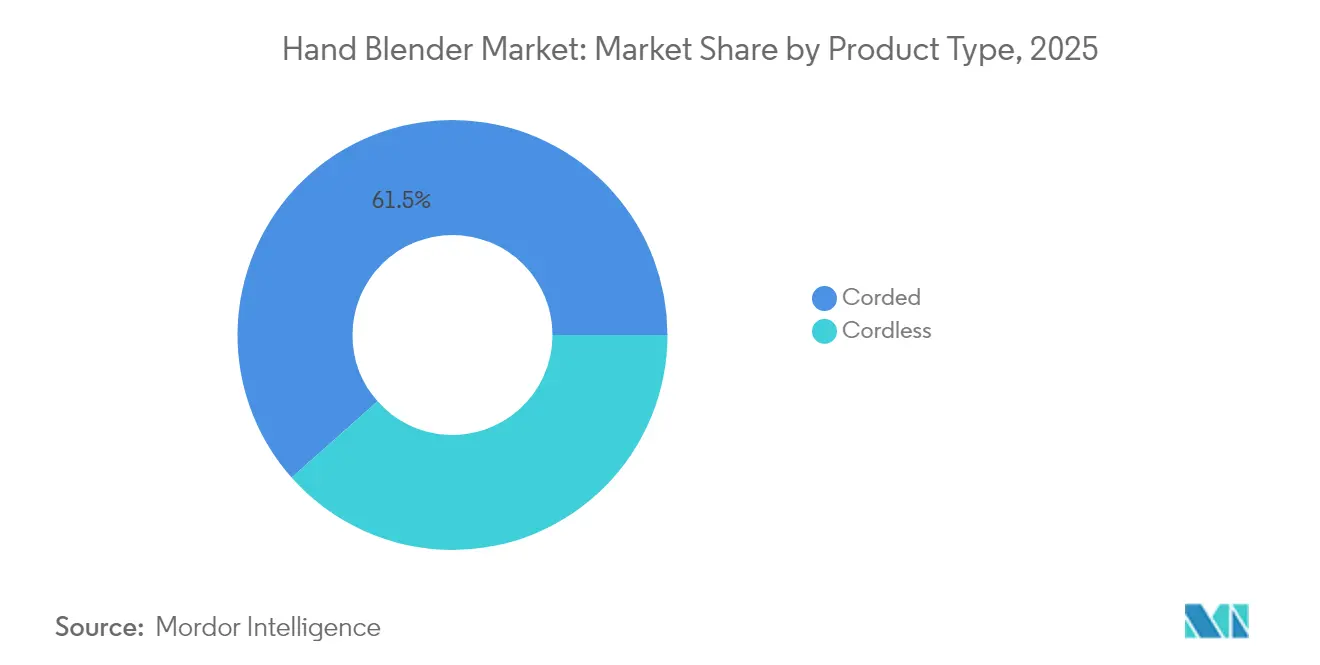
Cordless Innovation Drives Future GrowthCorded units held 61.54% of the hand blender market share in 2025 with uninterrupted runtime, rugged motors, and familiar price points. Their leadership anchors the overall hand blender market with dependable revenue streams, especially from commercial and heavy home users. Cordless lines, while smaller in absolute value, post a strong 7.55% CAGR, signaling that lithium-ion maturity and ergonomic gains are resonating with consumers seeking cable-free cooking. The segment’s expansion will elevate the hand blender market size for cordless variants over the next five years, provided battery supply stabilizes.
Rapid growth also reshapes brand portfolios. Vendors now launch cordless flagships first, then cascade technology to lower tiers, re-energizing mid-cycle refreshes. Corded models counterbalance by featuring high-torque settings ideal for dense dough and prolonged kitchen tasks. Manufacturers pair them with specialty beaters and extended shafts targeted at professional kitchens. The coexistence of both formats keeps overall replacement rates healthy, supporting a robust hand blender market through diversified positioning.


By End User:
Commercial Segment Accelerates Despite Residential DominanceResidential buyers accounted for 78.54% of the hand blender market size in 2025 as small-batch cooking and post-pandemic culinary habits spurred purchases. Home chefs favor lightweight designs, dishwasher-safe parts, and multi-speed triggers. Advertising often pairs the blender with smoothie bowls and infant purees, reinforcing household versatility. Commercial kitchens, though starting from a lower base, advance at a 7.31% CAGR owing to ghost kitchen adoption and specialist cafés requiring compact yet rugged gear. This upswing steadily lifts the hand blender industry’s professional revenue slice, prompting suppliers to certify products for continuous duty cycles and NSF-compliant hygiene.
Restaurant operators seek models capable of four-hour daily usage, detachable stainless steel shafts, and sealed buttons to resist cleaning fluids. Manufacturers price such units above residential SKUs, buffering margins against broader cost inflation. As delivery-only venues spread across dense urban corridors, commercial penetration adds stability to overall sales, diversifying demand beyond household replacement cycles and bolstering the hand blender market.
By Distribution Channel:
Online Retail Transforms Purchase PatternsOffline outlets still held 55.98% of revenue in 2025, reflecting shoppers’ desire to physically test weight and grip. Big-box retailers promote bundle discounts with pots or slicing sets, encouraging impulse purchases. Yet online retail’s 7.84% CAGR underlines shifting discovery habits; buyers increasingly research torque ratings and noise-level data via mobile apps before deciding. Optimization of last-mile logistics reduces breakage rates for fragile shafts, alleviating a historical barrier. The hand blender market size derived from pure-play e-commerce will therefore climb incrementally, especially in post-purchase ecosystems where automatic accessory replenishment boosts lifetime value.
Web-based platforms run algorithmic promotions synchronized with health-trend spikes, for example post-holiday detox periods, spurring seasonal peaks. Offline chains counter with experiential setups featuring chef-led demos that showcase texture control for popular dishes. A blended omnichannel strategy emerges: shoppers watch livestream tutorials, inspect units in store, then finalize transactions online for home delivery. The dynamic keeps both routes relevant and supports balanced growth across the hand blender market.
By Price Tier:
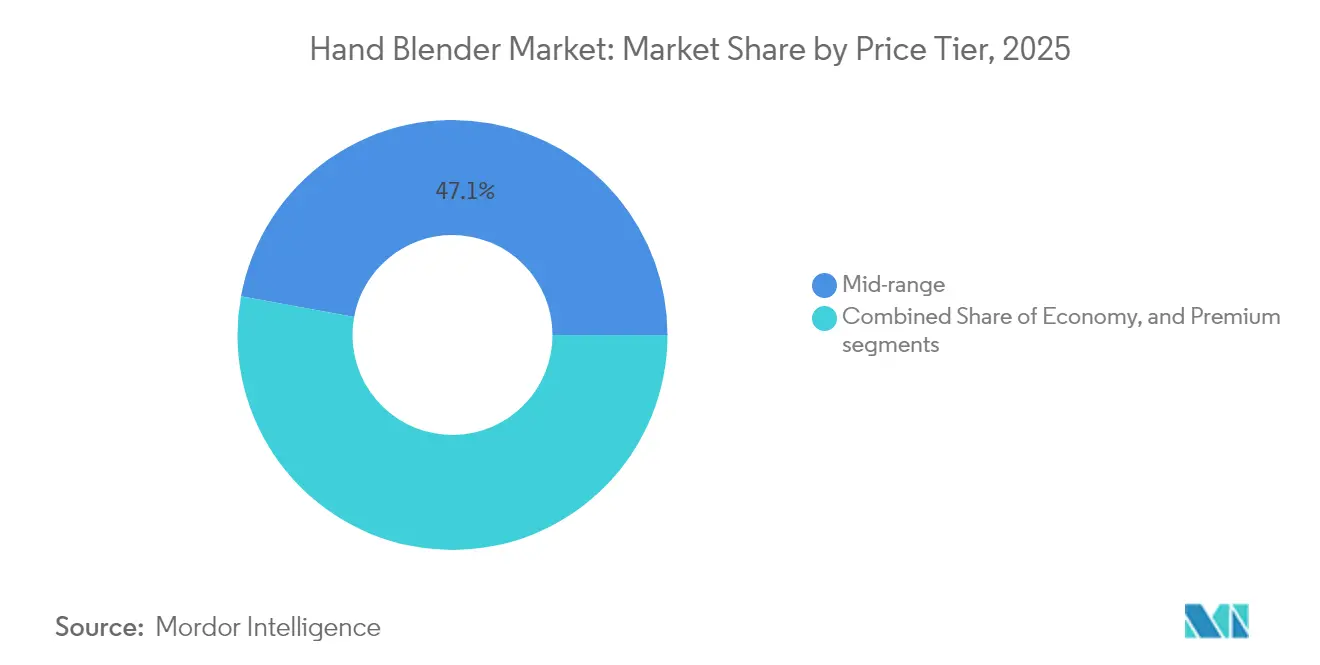
Premium Segment Leads Growth Despite Mid-range DominanceMid-range products captured 47.12% of the hand blender market size in 2025, serving pragmatic households that expect solid performance without luxury finishes. This tier benefits from scale manufacturing and feature trickle-down, extending sophisticated motors to accessible price points. Premium units priced above USD 100 grow at 8.95% CAGR, showing that affluent consumers value quieter operation, brushless motors, and full metal construction that remains cool during long blending sessions. Premium success pushes brands to invest in artisan-grade colorways and smart-connectivity chips, adding further differentiation.
Economy SKUs under USD 40 cater to first-time buyers and emerging markets but face tightening safety regulations and higher commodity costs, eroding already thin margins. Brands focusing on this tier pursue efficiency in assembly lines or partner with regional distributors to lower logistics expenditures. Over time, gradual consumer trading-up from economy to mid-range or premium benefits overall profitability in the hand blender market.
By Application:
Health-conscious Trends Drive Smoothie Segment GrowthSoups and sauces retained 33.98% of the hand blender market size in 2025, anchored by long-established cooking habits that value in-pot blending for hot preparations. The category relies on consistent temperature-resistant shafts and splash-reduction bell shapes. Smoothies and beverages post a 7.18% CAGR; this trend aligns with social media-led wellness challenges and the rise of plant-based diets. Influencers demonstrate fast breakfast smoothies assembled directly in portable beakers, reinforcing blender mobility.
Baby food and bakery applications see stable demand linked to population dynamics and at-home baking booms. Each additional attachment—whisks, frothers, and slicers—broadens utility and encourages accessory upgrades, reinforcing ecosystem stickiness in the hand blender market.
Geography Analysis
Europe Hand Blender Market
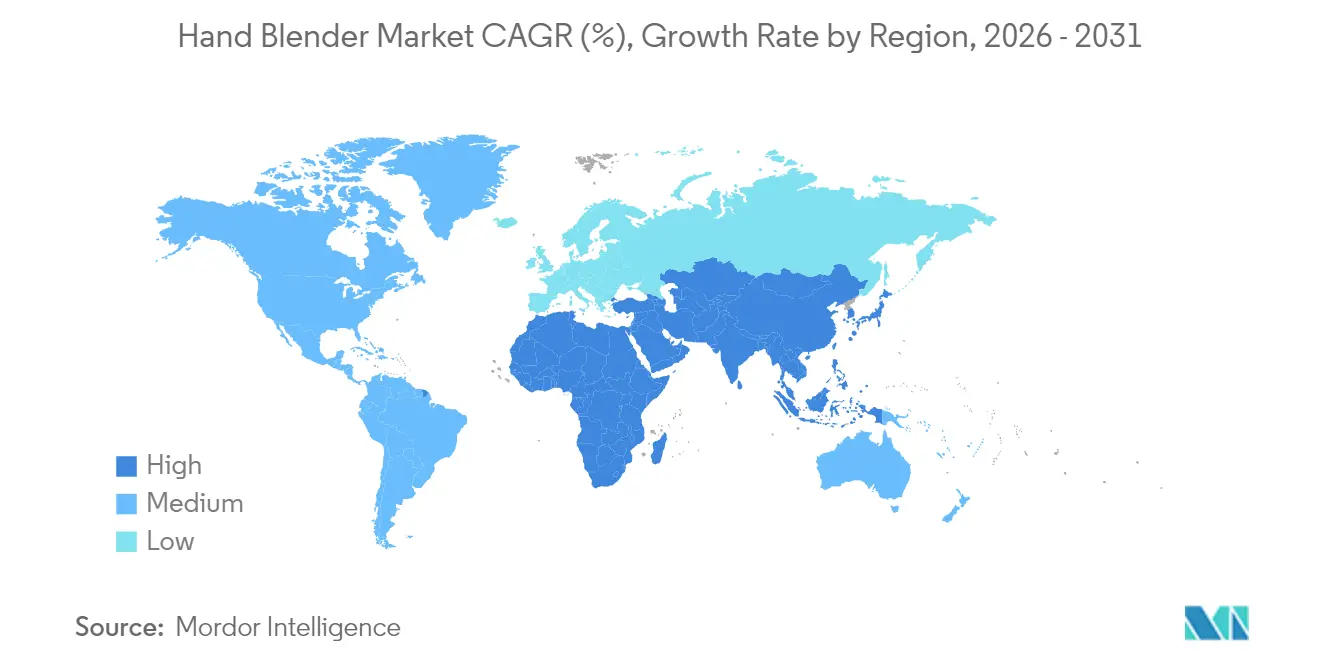
Europe remained the largest contributor with 36.02% revenue share in 2025. Mature households replace older units frequently and gravitate toward premium models featuring energy-efficient motors to meet EU eco-design norms. Brands leverage European engineering credentials to justify pricing, and rigorous certification frameworks push continuous safety enhancements. Distribution remains evenly split between specialist kitchen stores and online outlets, sustaining balanced growth within the regional hand blender market.
APAC Hand Blender Market
Asia-Pacific, on a 7.60% CAGR trajectory, benefits from rising disposable income and dense urban expansion in China and India. Smaller kitchen footprints favor handheld multifunction tools over countertop equipment. Local manufacturing clusters offer cost advantages, supporting competitive pricing that accelerates category penetration. Cross-border e-commerce further widens access to global brands, though trade policy fluctuations and component sourcing challenges represent ongoing hurdles for the hand blender market in the region.
The Americas and MEA Hand Blender Market
North America shows replacement-driven demand buoyed by premiumization and kitchen remodel trends that incorporate color-coordinated appliances. Competition from countertop models remains high, so manufacturers highlight precision control and easy storage to maintain relevance. South America and Middle East & Africa emerge more slowly due to macroeconomic volatility and limited retail infrastructure, yet urbanization unlocks pockets of future growth especially in middle-income segments. Suppliers adopting flexible voltage designs and region-specific plug types enhance accessibility, incrementally expanding the global hand blender market.

Regulatory Landscape
Hand blenders operate in a tightening small-appliance compliance environment covering electrical and mechanical safety, chemical disclosure, and energy-related design rules. In the IEC standards track, IEC 60335-2-14:2025 updates particular safety requirements for kitchen machines, including handheld blender variants, with specific attention to blade non-touchability. In Europe, the European Commission Implementing Decision (EU) 2025/1464 (July 17, 2025) determined not to publish the reference of harmonized standard EN 60335-2-14:2006 in the Official Journal due to safety concerns around blender blade access, which raises the compliance bar for manufacturers selling into the region.
In the United States, design, testing, and documentation requirements are also shaped by enforcement dynamics. Whirlpool Corporation operates under a US Consumer Product Safety Commission (CPSC) settlement-driven compliance framework (agreement finalized in 2023), reinforcing the importance of robust quality systems and traceability for consumer appliances under the CPSA. In California, Proposition 65 warnings and AB-1200 chemical disclosure requirements for food-contact surfaces add labeling and supply-chain documentation obligations, affecting material choices for shafts, coatings, and plastics used in accessories and containers.
Value Chain Analysis
The hand blender value chain begins with sourcing motors, electronics and control boards (including battery management systems for cordless models), stainless-steel shafts and blades, and food-contact plastics for beakers and attachments. This is followed by assembly, quality assurance, and third-party testing aligned to applicable safety standards. Compliance-driven inputs, such as verified base alloys and coatings, have become more central as brands strengthen supplier qualification and incoming inspection practices; for example, Whirlpool highlights third-party testing approaches tied to lead-content and migration requirements, increasing the importance of approved material suppliers and consistent lot-level traceability.
Midstream, product and packaging engineering increasingly connect to logistics efficiency and sustainability requirements. Versuni has described supply-chain moves that incorporate recycled and bio-based plastics, and it has implemented tools such as Circular Design Metrics (developed with DS Smith and the Ellen MacArthur Foundation) to evaluate environmental impact and guide redesign. Downstream, the chain spans offline retailers and fast-growing e-commerce routes, with packaging standardization and reduced-print documentation (for example, QR-enabled manuals) supporting lower packaging complexity, improved pallet utilization, and fewer region-specific packaging variants, which can reduce handling friction in cross-border distribution.
Competitive Landscape
Five leading companies—KitchenAid (Whirlpool Corp.), Braun Household (De'Longhi Group), Philips Domestic Appliances (Versuni), Breville Group, and Cuisinart (Conair Corp.)—hold a significant portion of 2024 sales, indicating moderate market concentration. Technology leadership is the principal battleground: brands race to optimize battery longevity, blade aerodynamics, and intuitive speed modulation. Intellectual-property acquisitions, such as De'Longhi’s cordless patents, safeguard differentiation and support premium pricing.
Sustainability ranks high on the innovation agenda. Electrolux partners with recycled-plastic suppliers to cut virgin-material content, aligning with EU circular-economy targets. Bosch’s 25% energy-use reduction underscores compliance readiness ahead of 2026 EcoDesign mandates [2]BSH Hausger?te, “New Energy-Efficient Motor Technology,” bosch-home.com. . Meanwhile, Whirlpool’s USD 50 million connectivity fund accelerates IoT features that link KitchenAid with voice assistants, nurturing a services ecosystem around firmware updates and recipe libraries [3]Whirlpool Corporation, “Smart-Connectivity Investment Announcement,” whirlpoolcorp.com. . Moderate consolidation leaves niches for region-specific challengers that adapt shaft length and input voltage to local culinary practices, though the scale of global leaders poses formidable entry barriers.
A moderate level of consolidation leaves room for regional challengers that tailor designs to local culinary practices, for instance longer shafts for traditional South American stews. Partnerships with local influencers further localize marketing messages. However, the scale advantages of global leaders in supply chain and R&D funding continue to shape the competitive baseline in the hand blender industry.
Hand Blender Industry Leaders
KitchenAid (Whirlpool Corp.)
Braun Household (De’Longhi Group)
Philips Domestic Appliances (Versuni
Breville Group
Cuisinart (Conair Corp.)
- *Disclaimer: Major Players sorted in no particular order
Hand Blender Market Companies Covered in this Report
- KitchenAid (Whirlpool Corp.)
- Braun Household (DeLonghi Group)
- Philips Domestic Appliances (Versuni)
- Breville Group
- Cuisinart (Conair Corp.)
- Hamilton Beach Brands
- Bosch Hausgerate (BSH)
- Kenwood Ltd (DeLonghi)
- Panasonic Corp.
- Smeg S.p.A.
- Electrolux AB
- Vitamix Corp.
- Robot Coupe
- Dynamic International
- Waring Commercial (Conair)
- SharkNinja (Ninja)
- Chefman
- Inalsa Appliances
- Morphy Richards
- TTK Prestige
- Bear Electric
- Braun GmbH
- Bamix*

Market Opportunities and Future Outlook
The most immediate opportunity lies at the intersection of premiumization and compliance, where brands can bundle higher perceived value with verifiable safety and material transparency. The shift to IEC 60335-2-14:2025 and Europe’s July 2025 action affecting EN 60335-2-14:2006 increases the payoff for designs that address blade-access risks. California Proposition 65 and AB-1200 also require more explicit chemical and food-contact disclosure, reinforcing demand for product platforms that use durable, testable materials, provide clearer labeling, and standardize documentation to reduce friction in regulated markets.
Sustainability-led packaging and circularity programs offer a second lever linked to cost-to-serve across omnichannel distribution. Versuni’s reported universal packaging platform rollout across its portfolio (including ink-use reduction and fewer packaging versions), Philips’ move to 100% recycled and recyclable paper packaging for home appliances, and the use of QR codes to replace printed multi-language manuals show how packaging redesign can support both logistics efficiency and retailer and consumer sustainability expectations. For hand blender vendors, these packaging and documentation systems can create room to simplify global SKUs, improve e-commerce ship-ability for attachments and accessories, and support direct-to-consumer replenishment models for consumables such as seals and replacement parts.
Recent Industry Developments in Hand Blender Market
- July 2026: KitchenAid (Whirlpool Corp.) launched the KitchenAid Go Cordless System in Malaysia confirming cordless hand blender availability. The initiative expands the cordless hand blender footprint in Southeast Asia and strengthens premium cordless positioning.
- April 2026: De'Longhi Japan released the Braun MultiQuick 3 Hand Blender in Japan on April 15, 2026. The product expansion in a key APAC market broadens Braun's regional presence and competes in the premium segment.
- April 2026: KitchenAid Go Cordless System additions press release highlighting ongoing cordless system evolution. Cordless system enhancements advance the platform and broaden cross device compatibility.


Hand Blender Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market covers revenues generated from hand blenders (also called immersion blenders), including corded and cordless models sold through offline and online channels for residential and commercial use.
Scope exclusions: Countertop blenders, food processors, mixer grinders, and other non-handheld mixing appliances are not counted in this market.
Segments Covered in This Report
- By Product Type
- Corded
- Cordless
- By End User
- Residential
- Commercial
- By Distribution Channel
- Offline Retail
- Online Retail
- By Price Tier
- Economy (Greater than USD 40)
- Mid-range (USD 40 - 100)
- Premium (Less than USD 100)
- By Application
- Soups and Sauces
- Smoothies and Beverages
- Baby Food and Purees
- Bakery and Dessert Prep
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab of Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the guardrails for the model and to avoid mixing hand blenders with adjacent small appliances. We reviewed public trade and macro indicators to understand how demand for small kitchen appliances typically moves, and we also used publicly available pricing cues to sense-check average selling price movement by region.
Key non-paywalled sources included materials such as UN Comtrade trade statistics for small appliance flows, World Bank and IMF macro series for household consumption signals, and government statistics offices for population, urbanization, and income proxies. We also referenced publications from standards and safety bodies (such as IEC and related national regulators) to understand how compliance can affect product refresh cycles. Company annual reports, investor presentations, and reputable press coverage were used to map channel mix and product launches, and a paid subscription for company financials and patent databases was used selectively to validate the direction of innovation. This desk source list is illustrative, and we reviewed many other public sources to collect, cross-check, and clarify data points.
Primary Interviews and Surveys
Primary work was used to convert the desk inputs into market-realistic assumptions, especially where public data is not reported at a hand-blender only level. We spoke with manufacturers, distributors, large retailers, and appliance-category specialists across key consumption regions, so the model could be corrected for channel shifts, price tier mix, and adoption of cordless formats.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 27% | CXOs: 13% | APAC: 44% |
| Mid tier: 58% | Functional/Unit leaders: 27% | EMEA: 37% |
| Smaller Players: 15% | Managers: 60% | Americas: 19% |
Market-Sizing & Forecasting
Sizing starts from a top-down demand pool build-up where household formation, urban living mix, and small-appliance spending patterns are translated into an addressable base, then refined using hand blender category penetration and replacement cycles. After those guardrails were set, selective bottom-up approximations were used to corroborate totals, including sampled channel checks for average selling prices and a roll-up of reported appliance revenues where product-level splits were available.
Inputs that mattered most included the share of cordless units in new sales, price tier mix (economy, mid-range, premium), distribution channel split between offline and online, and usage growth in quick-prep applications such as soups, sauces, and smoothies. When data gaps appeared, we used region-level proxying, followed by interview-led adjustments to keep the assumptions consistent with what is actually sold in each in-market channel.
For forecasting, we ran scenario analysis supported by short-run time series smoothing for key variables such as online share and cordless adoption. The scenarios were then aligned to the consensus range shared by industry participants. This approach keeps the forecast explainable and repeatable, while still reflecting observable category shifts.
Data Validation & Update Cycle
Model outputs were checked against independent signals before finalizing, including trade movement direction for small appliances, visible retail price bands, and the expected pace of cordless conversion in each region. Any major variance was traced back to one driver at a time, such as an unrealistic ASP step-up or a channel mix that did not match what respondents described.
A multi-step analyst review was applied so assumptions, calculations, and year-on-year growth stayed internally consistent across regions and end users. When responses indicated a material change, such as a promotion-led price drop or supply tightness in components, follow-up outreach was triggered to re-validate the input. Reports are refreshed annually, with interim updates when major events change demand or pricing, and a final pre-delivery review is completed so the latest information is reflected.
麻豆视频's Global Hand Blender Market Size Measured Against Other Published Estimates
Published market sizes for hand blenders can look far apart because the boundary is not always treated the same, and because pricing and channel assumptions can be updated at different speeds. Some estimates also mix handheld and countertop blending appliances, which inflates the addressable revenue pool even when the product purpose overlaps.
The benchmark table shows a tighter 2026 value, and in 麻豆视频's model the total is limited to hand blenders only (corded and cordless) across residential and commercial end users, rather than folding in nearby countertop blender revenue or broader small kitchen appliance bundles.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 4.08 B (2026) | |
| Global Consultancy A | USD 5.32 B (2024) | Uses an earlier base year and appears to include broader handheld blending tools with limited clarity on whether adjacent countertop blending revenue is excluded, which can lift totals when mapped to retail category labels. |
| Industry Insights Group B | USD 4.64 B (2025) | Applies a higher implied price uplift and faster online-led unit growth without showing cross-checks against replacement cycles, and currency timing assumptions are not transparent for multi-region rollups. |
The spread across sources mainly comes from what gets counted as a hand blender category, which year is used as the anchor, and how quickly ASP and channel mix are assumed to change. By tying the model to observable adoption markers like cordless share, channel split, and replacement behavior, the estimate stays traceable to clear inputs and can be re-run when new signals emerge.


Key Questions Answered in the Report
What is the expected value of the hand blender market by 2031?
The market is projected to reach USD 5.17 billion by 2031 at a 4.84% CAGR.
Which region is growing fastest for hand blenders?
Asia-Pacific leads with a forecast 7.60% CAGR thanks to urbanization and income growth.
Are cordless hand blenders gaining traction?
Yes, cordless models show the highest 7.55% CAGR due to lithium-ion improvements and greater kitchen mobility.
What price tier is expanding most quickly?
Premium units priced above USD 100 grow at a 8.95% CAGR as consumers invest in advanced features.
How concentrated is competition in the sector?
The top five brands command roughly three-quarters of global revenue, reflecting moderate concentration.
Which application category drives the greatest growth?
Smoothies and beverages segment expands at 7.18% CAGR, propelled by health-focused consumer habits.
Page last updated on:



