
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 1.10 Billion |
| Market Size (2026) | USD 1.17 Billion |
| Market Size (2031) | USD 1.57 Billion |
| Growth Rate (2026 - 2031) | 6.12 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
India Automotive OEM Coatings Market Analysis by 麻豆视频
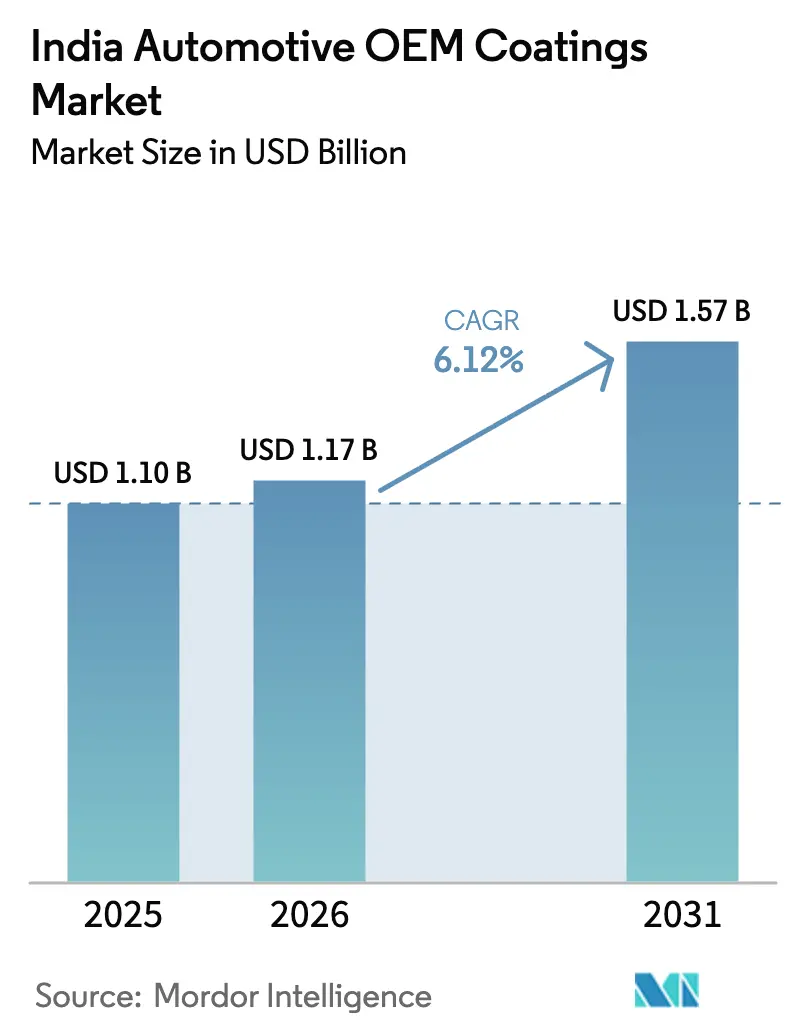
India Automotive OEM Coatings Market size in 2026 is estimated at USD 1.17 billion, growing from 2025 value of USD 1.10 billion with 2031 projections showing USD 1.57 billion, growing at 6.12% CAGR over 2026-2031. The growth arises from a steady preference for premium finishes, regulatory pushes toward low-VOC technologies, and localization incentives that reduce raw-material risk. Passenger cars remain the volume anchor, but multi-layer systems for SUVs and electric vehicles lift value per unit. Resin manufacturers benefit from a USD 3.5 billion Production-Linked Incentive fund that shrinks import dependence and stabilizes pricing. Rising electric-vehicle adoption creates niche demand for corrosion-resistant coatings on battery enclosures, while semiconductor cost inflation encourages automation in paint shops to offset operating expenses. Together, these trends allow the India automotive OEM coatings market to outpace the broader vehicle production cycle despite short-term supply shocks.
Key Report Takeaways
- By resin type, acrylics held 41.15% of the India automotive OEM coatings market share in 2025, whereas polyurethanes are poised for the fastest 6.41% CAGR through 2031.
- By technology, solvent-borne systems commanded 44.62% share of the India automotive OEM coatings market size in 2025, yet water-borne alternatives are expanding at 6.55% CAGR to 2031.
- By coat type, clearcoats contributed 33.55% revenue share in 2025, while e-coats advance at a 6.43% CAGR through 2031.
- By vehicle type, passenger cars accounted for 70.82% of the India automotive OEM coatings market size in 2025 and continue to grow at a 6.28% CAGR.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
India Automotive OEM Coatings Market Trends and Insights
Drivers Impact Analysis*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in SUV and premium-segment launches | +1.2% | National; early demand in Tamil Nadu, Karnataka, Maharashtra | Medium term (2-4 years) |
| OEM shift to water-borne lines | +0.8% | National; automotive manufacturing hubs | Short term (≤ 2 years) |
| PLI-linked localization of raw materials | +1.5% | Gujarat, Tamil Nadu, Maharashtra | Long term (≥ 4 years) |
| Lightweighting push for high-solid PU systems | +0.9% | Premium vehicle programs by global OEMs | Medium term (2-4 years) |
| EV battery-pack corrosion needs | +0.6% | Emerging EV hubs in Tamil Nadu, Karnataka, Maharashtra | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Surge in SUV and Premium-Segment Launches Post-2024
Premium SUVs require multi-layer, high-gloss coatings with scratch resistance, driving higher value per vehicle. Luxury registrations in South India climbed 19.3% in 2024, prompting OEM investments in advanced spray robots that support two-tone roof designs. Domestic brands now deploy digital paint cells that enable fine color accents once limited to luxury imports. Larger body panels on SUVs expand the coated surface area and raise the consumption of clearcoat and basecoat layers. Certification under the Automotive Research Association of India standards anchors product specifications and keeps the barrier-to-entry high for new suppliers.
PLI-Linked Localization of Resin and Pigment Supply Chains
The Production-Linked Incentive program unlocks domestic investment in acrylic, polyurethane, and pigment plants, trimming currency exposure and shipping delays. Government data show USD 3.5 billion allocated to auto incentives, sparking multi-state resin projects[1]Press Information Bureau, “Revolutionizing Mobility – The Make in India Auto Story,” pib.gov.in. Early localization narrows the historic titanium-dioxide supply gap, giving large integrated suppliers a margin buffer. Smaller import-dependent applicants, however, face working-capital strain during the transition.
Automotive Lightweighting Drives High-Solid PU Demand
Polyurethane systems deliver chip resistance and elasticity ideal for aluminum and composite panels used in lighter vehicles. Their 6.72% CAGR reflects OEM targets to offset semiconductor and battery costs with weight savings. High-solid chemistry lowers VOC output while maintaining film build, aligning with environmental mandates. Material innovators advance PU resin chain-extensions to bond securely to new substrates, widening application beyond body panels to structural battery casings.
EV Battery-Pack Corrosion Requirements Create Niche Epoxy Demand
Uniform e-coat layers shield battery housings from electrolyte leaks and thermal cycling. Epoxy formulations with dielectric properties prevent short circuits and enhance fire safety. A dedicated application center opened by a global coatings major accelerates local prototype work, mirroring earlier facilities abroad. Powder e-coats gain favor for low-temperature cure profiles that protect sensitive battery components, reinforcing a specialized growth pocket inside the India automotive OEM coatings market.
Restraints Impact Analysis*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Semiconductor shortages delaying upgrades | -0.7% | Global; acute for Indian expansion plans | Short term (≤ 2 years) |
| Volatile titanium-dioxide prices | -0.9% | National; heavier on smaller applicators | Medium term (2-4 years) |
| Slow approval of powder clearcoats | -0.4% | National; affects exterior applications | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Semiconductor Shortages Delay New Paint-Shop Investments
Vehicle makers channel scarce chips to production, postponing capital for automation in coating lines. Advanced robots and inline quality sensors require the same microcontrollers that power infotainment systems. Project deferrals compress short-term demand for new spray booths, giving incumbent applicators extra volume but limiting overall capacity growth. OEMs favor equipment that operates on existing control platforms, restraining rollout of digital overspray-free technologies.
Volatile Titanium-Dioxide Prices Squeeze Tier-2 Applicators
Rutile feedstock tightness swings pigment costs, eroding margins for small‐scale coaters who lack hedging ability. Domestic output meets only one-fifth of demand, forcing reliance on imports denominated in strong currencies. Integrated players with captive mining or long contracts pass cost swings more easily to OEMs, accelerating consolidation. Industry hopes stem from PLI-backed mineral projects that could lift local production but will not materially ease pressure before 2027.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Resin Type: Acrylics Anchor Volume, Polyurethanes Propel Value
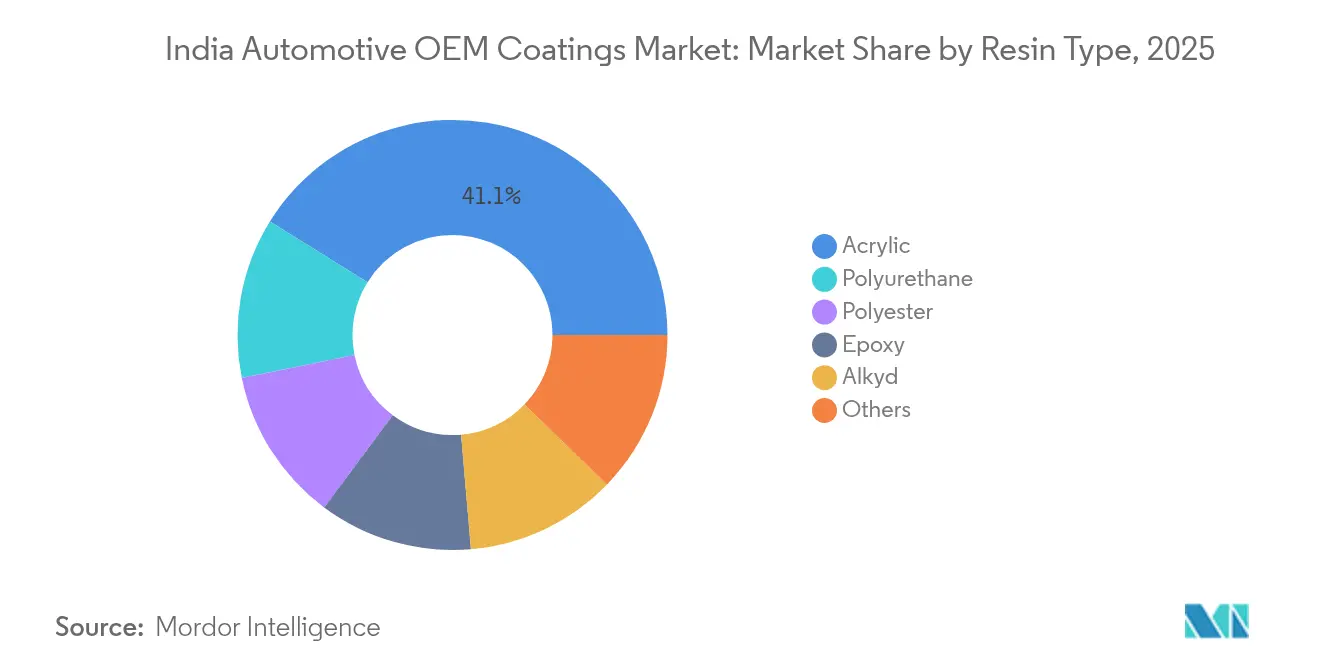
Acrylic resins commanded 41.15% of 2025 revenue in the India automotive OEM coatings market. Their versatility across basecoat and clearcoat roles and cost advantage keep them the default choice for passenger cars. Polyurethanes, however, post the highest 6.41% CAGR, reflecting lightweighting and flexibility imperatives. Epoxy grades re-emerge for electric-vehicle enclosures that face chemical and thermal stress. Halloysite nanotube-reinforced epoxy-acrylate emulsions doubled salt-spray endurance in lab work, hinting at next-generation corrosion solutions. Niche bio-based chemistries occupy the “Others” bucket, gaining OEM attention for future zero-isocyanate programs.
Competitive positioning shifts as integrated resin makers leverage in-house pigment synthesis secured under PLI benefits. The India automotive OEM coatings market size tied to acrylics should still rise in absolute terms, though the share migrates incrementally to high-solid PU. Suppliers with balanced resin portfolios cushion against cyclical swings in any single chemistry. Certification processes under ISO 12944 balance experimentation with reliability, keeping barriers to rapid resin substitution high and ensuring gradual, not abrupt, share shifts.


By Technology: Water-Borne Momentum Builds on Regulatory Tailwinds
Solvent-borne systems retained a 44.62% share in 2025, thanks to performance familiarity, especially for clearcoats. Yet water-borne volumes climb steadily with a CAGR of 6.55%, propelled by India-VI rules and carbon-reduction targets. Sustainability-led products already account for nearly half of a leading global supplier’s sales. Development focus centers on resins that trap hydrophobic segments within polymer shells, delivering high gloss at lower bake temperatures.
Investment announcements for dedicated water-based paint lines in central India shorten delivery cycles for OEMs shifting platforms. The India automotive OEM coatings market size allocated to water-borne solutions is projected to surpass solvent-borne by 2029 if current trajectories hold. Powder and UV-cure technologies reside in the “Others” category. Although powder clearcoats await final exterior certification, their zero-VOC profile ensures long-term relevance. UV systems find niche use on plastic exterior parts where fast tack-free cure enhances throughput.
By Coat Type: Clearcoats Capture the Largest Wallet Share
Clearcoats represented 33.55% value in 2025, validating their role as the final aesthetic and protective layer. Innovations such as pixelated robotic applications allow contrasting roofs and stripes with no masking film, cutting material waste up to 40%. E-coats register 6.43% CAGR as body-in-white surfaces and battery boxes seek uniform corrosion shields. Basecoats gain from metallic and pearl grades popular in SUVs, while primers increasingly adopt water-borne formats under VOC caps.
Adoption patterns tell a value-hierarchy story: OEMs cannot compromise on clearcoat quality, so premium formulations deliver pricing power. Conversely, volumes rest with primers and e-coats that cover the full body. The India automotive OEM coatings market share captured by high-function layers, therefore, skews value distribution. Powder clearcoats, once approved, could upset this balance by mixing top-tier durability with environmental compliance, but timelines remain uncertain.
By Vehicle Type: Passenger Cars Drive Scale, EVs Seed New Niches
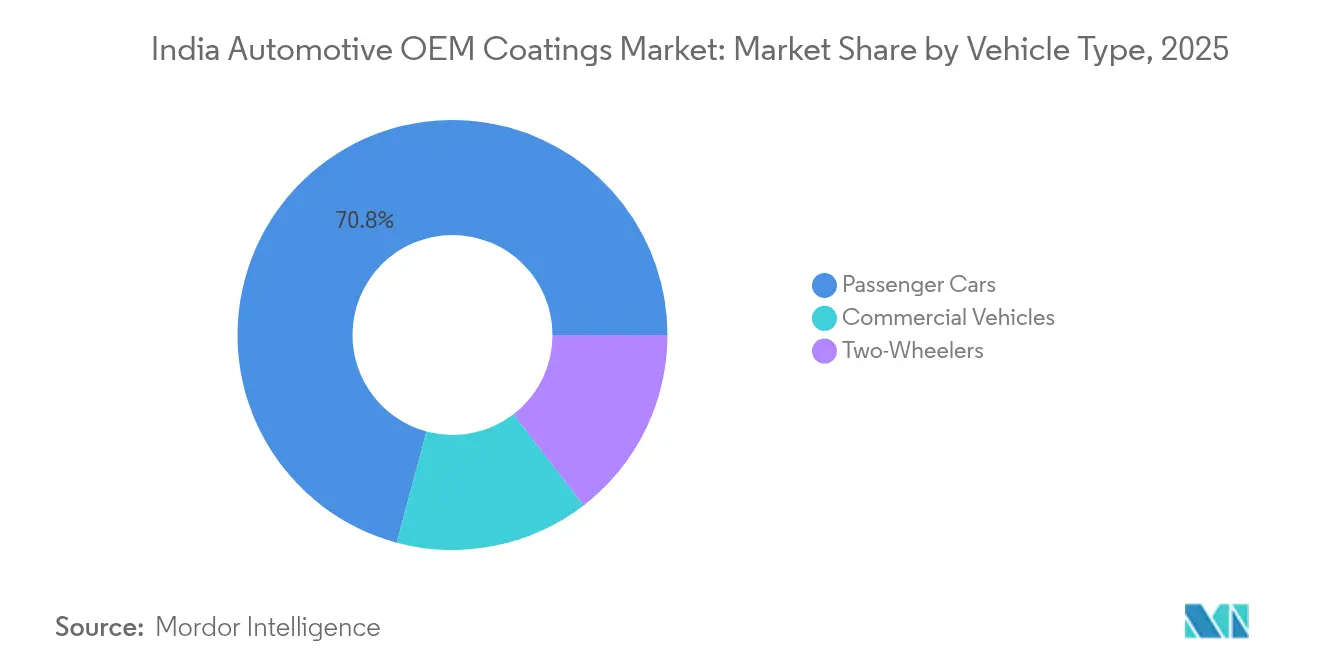
Passenger cars held 70.82% of the 2025 volume and are growing at a CAGR of 6.28% owing to stringent cosmetic expectations. Compact SUVs lead color-variant rollout cycles, raising basecoat complexity. Commercial vehicles demand thick, chip-resistant coatings, often high-solid polyurethane blends, to survive rough logistics routes. Two-wheeler makers stress cost-per-part yet increasingly add metallic flake and matte finishes to differentiate models.
Electric three-wheelers reached 50% penetration and two-wheelers 5% in 2024, creating an immediate need for dielectric and thermal-management coatings on battery casings. Though unit economics differ, their fast growth pulls epoxy and powder specialists into new supply opportunities. The India automotive OEM coatings market size attached to passenger cars still dwarfs others, yet incremental growth from EV variants alters the chemistry mix, ensuring robust demand for innovation in corrosion and heat-dissipation layers.
Geography Analysis
Manufacturing hubs in Tamil Nadu, Gujarat, and Maharashtra anchor more than two-thirds of India’s automotive output, shaping regional coating consumption. Tamil Nadu leads luxury-vehicle demand, prompting suppliers to expand water-borne and clearcoat capacity near Chennai for logistical efficiency.
Gujarat benefits from proximity to petrochemical complexes that feed resin and solvent value chains. A leading domestic paint maker broke ground on a USD 350 million facility near Bharuch, underlining the pull of integrated feedstocks. The India automotive OEM coatings market grows in the West as global OEMs deploy export-oriented platforms from Sanand.
Maharashtra’s Chakan corridor showcases advanced paint automation, including AI-guided robots that adjust atomization parameters in real time. The corridor’s EV programs draw niche suppliers for battery-pack coatings. While the south and west dominate volumes, northern states add incremental capacity tied to commercial-vehicle assemblers who prefer epoxy-rich, high-build systems to suit long-haul duty cycles. Nationally, water-borne lines proliferate fastest where state industrial policies rebate capital on pollution control infrastructure, reinforcing the regional mosaic of technology uptake.
Regulatory Landscape
Automotive coatings standards in India are defined through the CMVR Technical Standing Committee (CMVR-TSC), the Automotive Industry Standards Committee (AISC), and the Bureau of Indian Standards (BIS). For type approval, OEMs submit technical specifications under AIS-007, with conformity assessments anchored to ARAI-linked procedures.
India is a signatory to the 1998 UN WP.29 agreement but is not a party to the 1958 agreement. This distinction affects mutual recognition of type approvals and can influence import dynamics.
Value Chain Analysis
The India automotive OEM coatings value chain begins with upstream feedstocks and intermediates, including resins, pigments such as titanium dioxide, solvents, and additives. It then moves into formulation and manufacturing of e-coats, primers, basecoats, and clearcoats, followed by OEM paint-shop application covering pretreatment, electro-deposition, bake cycles, and quality checks.
Localization efforts under Make in India and the Production-Linked Incentive (PLI) scheme are drawing more resin and pigment capacity into domestic supply networks. At the same time, import dependence for some inputs continues to shape price volatility and working-capital needs for smaller applicators.
Competitive Landscape
The India automotive OEM coatings market is moderately fragmented and tilting further toward scale players. Asian Paints, Kansai Nerolac, Berger Paints, and the newly formed JSW-Akzo entity run multi-site networks with aligned resin, pigment, and application technology. Potential disruptors surface in powder clearcoats and UV-cure solutions. Early-stage providers partner with equipment OEMs to co-validate processes for regulatory approval. Meanwhile, volatile titanium-dioxide pricing widens the gap between integrated and standalone players, creating acquisition prospects as smaller applicators seek balance-sheet relief. Overall, supplier alliances with equipment makers and raw-material localization continue to shape bargaining power in contract renewals with automotive OEMs.
India Automotive OEM Coatings Industry Leaders
Axalta Coating Systems LLC
BASF
JSW Paints
Kansai Nerolac Paints Limited
PPG Industries, Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Technology conversion inside OEM paint shops remains a key white-space area, especially the shift from solvent-borne to water-borne systems. Process updates that reduce energy use, including wet-on-wet approaches and low-bake color systems, also present implementation opportunities tied to shop upgrades.
Supplier and OEM actions are already reinforcing this direction. Established players are emphasizing sustainability-led portfolios, while OEMs are upgrading lines to meet VOC and operational-efficiency constraints linked to India-VI era compliance expectations.
Recent Industry Developments
- July 2026: Axalta Coating Systems participated in Prawaas 5.0 in Gandhinagar, showcasing low-cure, waterborne, and heat-reflective coatings for commercial vehicle OEMs. The demonstration expanded exposure to India’s commercial vehicle segment and reflected continued focus on advanced coating solutions.
- December 2025: JSW Paints completed the acquisition of Akzo Nobel India, integrating industrial coatings assets including automotive refinish capabilities. The consolidation strengthened JSW Paints' footprint in Indian automotive coatings and broadened its asset base.
- April 2024: BASF expanded its e-coat manufacturing facility at the Mangalore site, focusing on CathoGuard 800 RE products for Indian automotive OEMs. The expansion increased e-coat capacity to meet OEM demand and supported premium finishes in India's market.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers coatings supplied for factory application on new vehicles made in India, where the coating is applied on the production line to protect and finish the vehicle body and parts.
Scope exclusions: It excludes aftermarket refinish paints, detailing products, and coatings used mainly for industrial equipment that is not part of an automotive OEM line.
Segmentation Overview
- By Resin Type
- Epoxy
- Acrylic
- Alkyd
- Polyurethane
- Polyester
- Others
- By Technology
- Water-borne
- Solvent-borne
- Others
- By Coat Type
- E-coat
- Primer
- Basecoat
- Clearcoat
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- Two-Wheelers
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the starting structure of demand and pricing for OEM coatings in India, before we stress-tested assumptions with field inputs. Public sources helped us anchor vehicle production by type and track the direction of regulatory and technology shifts, which then guided realistic split assumptions for coating layers and technologies.
Illustrative sources include SIAM production and sales releases, Ministry of Road Transport and Highways vehicle registration statistics, India customs trade data for key coating raw materials and intermediates, CPCB notifications relevant to VOC control, and peer-reviewed journals covering corrosion protection and coating performance. We also reviewed company annual reports, investor presentations, and plant expansion announcements, and then supplemented coverage with paid subscriptions for company financials and intelligence, news and financials, patent databases, and shipment-level import and export data where it helped validate supply signals. These sources are not exhaustive, and we used additional references for data collection, validation, and clarification during the work.
Primary Interviews and Surveys
Primary work focused on paint shop and procurement viewpoints along the OEM value chain, including coating formulators, channel partners serving OEM plants, and vehicle makers who influence technology choices. Because the analysis is India-specific, discussions were centered on major manufacturing clusters, while cross-checking how passenger vehicles, two-wheelers, and commercial vehicles differ in layer counts, transfer efficiency, and accepted price ranges.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 39% | CXOs: 12% |
| Mid tier: 42% | Functional/Unit leaders: 31% |
| Smaller Players: 19% | Managers: 57% |
Market-Sizing & Forecasting
The sizing starts from a top-down reconstruction where vehicle production by category in India is translated into coated surface demand, and then converted into value using layer-wise coating usage and price assumptions. To keep the model grounded, results are corroborated using selective bottom-up checks, such as sampling supplier revenue exposure to OEM coatings, channel checks on typical plant-level consumption, and a simple volume times average selling price sanity check by coat type.
Key inputs that shape the totals include passenger car, two-wheeler, and commercial vehicle output trends, the mix shift toward premium finishes that lifts clearcoat and basecoat value, the water-borne versus solvent-borne adoption pattern in OEM plants, and resin and solvent price movements that influence OEM contract pricing. We also track paint shop utilization and repaint or reject rates as directional checks, since these can affect consumption even when production is stable. For forecasting, scenario analysis is applied around vehicle production growth, technology migration (especially water-borne), and expected pricing pass-through, with the final trajectory aligned to what industry experts consider achievable over the cycle. When company or plant information is incomplete, gaps are handled by using peer averages and then rebalancing to match the production-led demand pool.
Data Validation & Update Cycle
Validation is done through multiple checks that look for mismatches between the model and independent signals, such as reported vehicle output, trade flows for key inputs, and shifts in OEM technology choices. Outliers are reviewed and adjusted only after the underlying driver is understood, and then a second analyst review is completed before sign-off.
The report is refreshed annually, and interim updates are triggered when there are material events, such as sharp raw material price swings, regulatory moves affecting VOC limits, or major capacity additions and shutdowns. Before delivery, we complete a final pass to confirm that the latest public releases and recent interview feedback have been reflected consistently across the market totals and the assumptions behind them.
麻豆视频's India Automotive Oem Coatings Market Size Measured Against Other Published Estimates
Published market values for India automotive OEM coatings can vary more than buyers expect, even when the topic sounds narrowly defined. The main reasons usually come from differences in what is counted as OEM, how coat layers are valued, and whether numbers are aligned to the same base year and currency timing.
The table shows a visible spread across estimates because some publishers roll OEM and refinish together or include coatings used on adjacent non-vehicle industrial parts, and then apply broad price escalation across the full basket. In 麻豆视频's model, the number is built from OEM line-applied coatings only, with coat-type splits tied back to vehicle production mix and with pricing updated using near-term contract and input cost checks rather than a single flat inflation factor.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 1.10 B (2025) | |
| Industry Association A | USD 1.34 B (2025) | Often aggregates automotive OEM coatings with refinish demand and some non-OEM industrial coating uses, which inflates the addressable value when applied to total paints and coatings consumption. |
| Trade Journal B | USD 0.92 B (2026) | Typically uses a narrower vehicle coverage and conservative plant utilization assumptions, and then applies a simplified price-per-vehicle factor without separating e-coat, primer, basecoat, and clearcoat value build-up. |
Looking across the figures, the key takeaway is that scope and conversion logic matter as much as the headline year. By keeping the build-up traceable to vehicle output, layer demand, and realistic pricing inputs, the resulting market size stays easier to reproduce and to pressure-test when assumptions change.


Key Questions Answered in the Report
What is the current value of the India automotive OEM coatings market?
The market is worth USD 1.17 billion in 2026 and is forecast to reach USD 1.57 billion by 2031.
Which resin type leads demand in India for OEM coatings?
Acrylic resins lead with 41.15% share thanks to versatility and cost efficiency.
How fast are water-borne automotive coatings growing in India?
Water-borne systems are expanding at a 6.55% CAGR through 2031 under VOC regulations.
What vehicle segment drives the highest coating consumption?
Passenger cars account for 70.82% of coating demand and remain the innovation anchor.
Which Indian states host the largest automotive paint facilities?
Tamil Nadu, Gujarat, and Maharashtra house the most significant coating manufacturing clusters.
Page last updated on:



