
India Dried Distillers Grain With Solubles Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
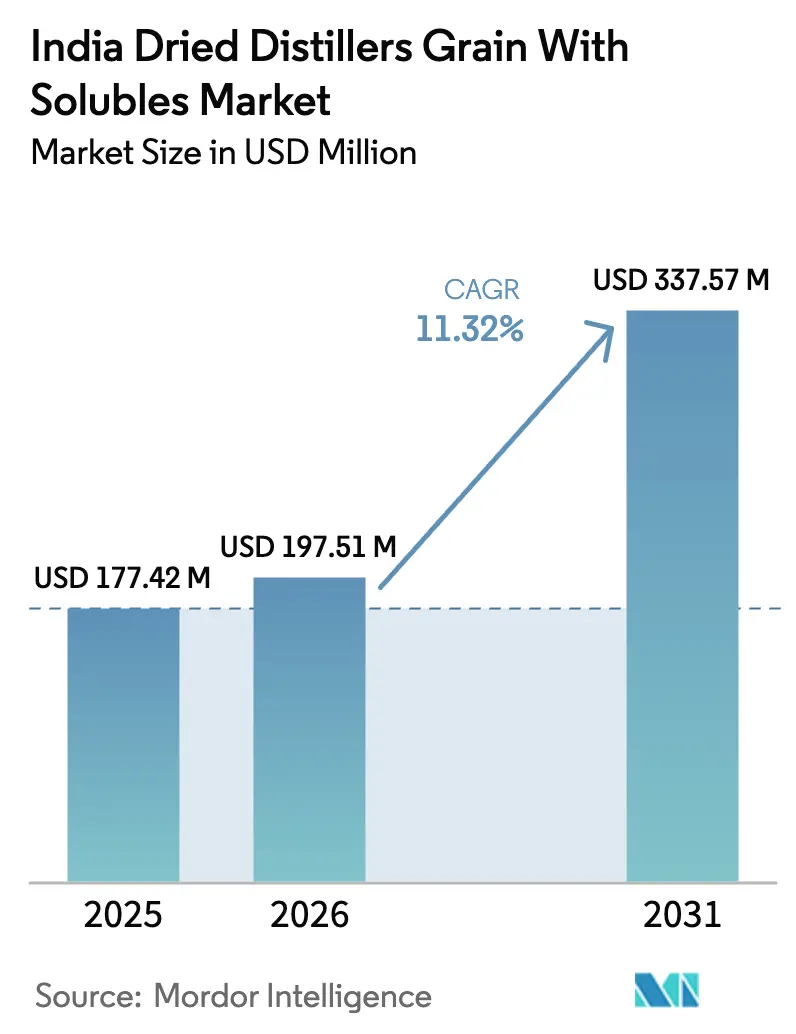
| Base Year Market Size (2025) | USD 177.42 Million |
| Market Size (2026) | USD 197.51 Million |
| Market Size (2031) | USD 337.57 Million |
| Growth Rate (2026 - 2031) | 11.32 % |
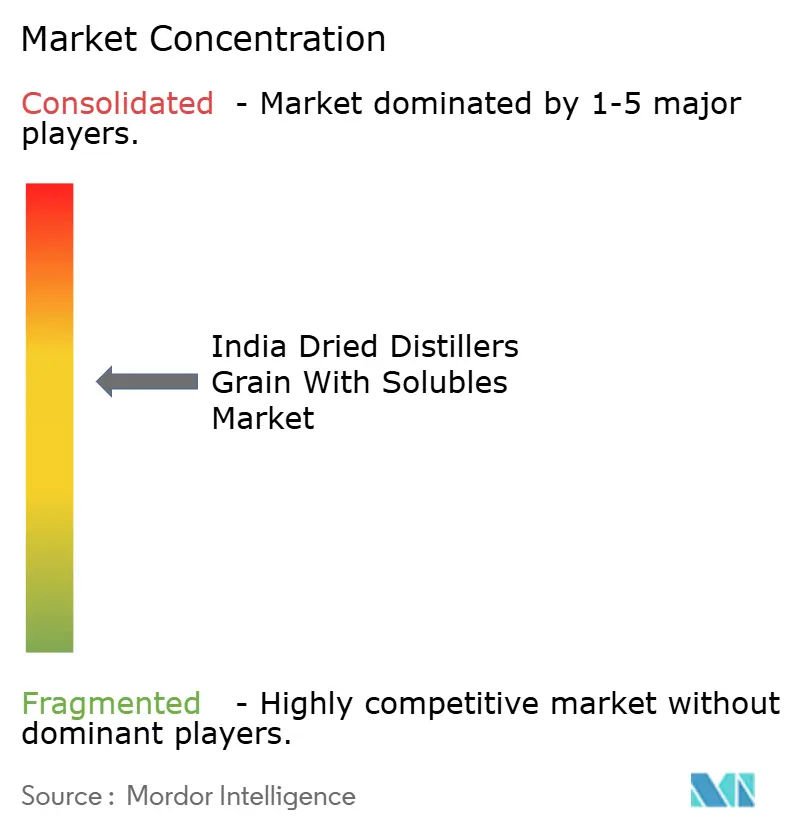
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
India Dried Distillers Grain With Solubles Market Analysis by 麻豆视频
The India dried distillers grain with solubles market size was valued at USD 177.42 million in 2025 and estimated to grow from USD 197.51 million in 2026 to reach USD 337.57 million by 2031, at a CAGR of 11.32% during the forecast period (2026-2031). India's ethanol blending mandate aligns with livestock nutrition needs, establishing DDGS (Distillers Dried Grains with Solubles) as a significant feed ingredient to address the country's protein deficit. Feed mills, dairy farms, and poultry integrators are increasing DDGS inclusion in their formulations due to its 26-30% crude protein content and metabolizable energy comparable to corn. The E20 policy implementation and industry investments, including Modi Naturals' Raipur facility expansion in 2025, ensure a consistent grain-based DDGS supply while reducing imported soybean meal dependency. Despite challenges in logistics, anti-nutritional factors, and tax regulations, DDGS maintains a 15-20% cost advantage compared to traditional protein meals, enabling feed manufacturers to maintain margins during feedgrain price fluctuations.
Key Report Takeaways
- By product type, corn led with 64.90% of the India dried distillers grain with solubles market share in 2025, while rice is forecast to expand at a 11.96% CAGR through 2031.
- By animal type, poultry commanded 42.10% of the India dried distillers grain with solubles market size in 2025, whereas aquaculture is advancing at a 13.55% CAGR to 2031.
- Market concentration is moderate, with the top five companies - ADM (Archer Daniels Midland Company), Louis Dreyfus Company B.V., IFB Agro Industries Limited, Gulshan Polyols Limited (Gulshan Holdings Private Limited), and Nutrigo Feeds Pvt Ltd (SSL Group) collectively holding the majority of the India dried distillers grain with solubles market share in 2025.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
India Dried Distillers Grain With Solubles Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising demand for sustainable livestock feed ingredients | +1.8% | Maharashtra, Karnataka, and Uttar Pradesh | Medium term (2-4 years) |
| Expansion of domestic ethanol production drives DDGS supply | +2.3% | Ethanol clusters nationwide | Short term (≤ 2 years) |
| Cost-effective protein and fiber source versus conventional meals | +1.5% | Feed-deficit regions | Long term (≥ 4 years) |
| Government biofuel mandate catalyzes new distilleries | +2.1% | Grain-surplus states | Medium term (2-4 years) |
| Adoption of DDGS in commercial aquaculture feed blends | +1.2% | Coastal aquaculture hubs | Long term (≥ 4 years) |
| Introduction of high-protein fractionated DDGS improves feed conversion | +0.9% | Organized feed sector nationwide | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||


Rising Demand for Sustainable Livestock Feed Ingredients
India's livestock sector faces a cattle concentrate deficit of 78 million metric tons in 2024, compelling feed manufacturers to seek alternative protein sources that are locally available and support circular economy principles. DDGS meets these requirements by converting ethanol byproducts into feed, reducing dependence on soybean meal imports, and conserving foreign exchange. Organized feed mills, which produce 17 million metric tons of compound feed annually, utilize DDGS for its consistent 26-30% protein content and digestibility when managed with appropriate quality control measures[1]Source: Agricultural and Processed Food Products Export Development Authority, “Prepared Animal Feeder,” apeda.gov.in. The increasing adoption of sustainability certifications by meat processors encourages the use of ingredients with reduced carbon footprints and localized supply chains. These factors establish DDGS as an essential component in feed formulations for dairy operations, poultry integrators, and commercial aquaculture facilities.
Expansion of Domestic Ethanol Production Drives DDGS Supply
India requires approximately 10.16 billion liters of ethanol annually to achieve E20 blending targets. By mid-2024, grain-based distilleries supplied 1.81 billion liters of ethanol, with maize contributing 1.10 billion liters and generating significant DDGS production. The March 2025 policy allows cooperative sugar mills to process maize and damaged food grains beyond the cane-crushing season, enabling year-round DDGS production. The government provides interest subvention up to 6% for five years to reduce capital costs, while the National Agricultural Cooperative Marketing Federation of India Ltd. ensures stable grain procurement. These measures support consistent DDGS production volumes in the India dried distillers grain with solubles market.
Cost-Effective Protein and Fiber Source Versus Conventional Meals
DDGS is priced 15-20% lower than soybean meal while providing similar protein content and additional fiber that improves rumen health. Its cost advantage increased in early 2024 when maize prices rose by 20%, expanding the price difference between grain inputs and coproduct outputs. Poultry producers incorporate DDGS at 10-15% levels in feed without affecting conversion ratios, reducing costs during periods of margin pressure. The 8-12% fiber content allows dairy farmers to substitute roughage components, lowering total feed costs and streamlining diet formulation.
Adoption of DDGS in Commercial Aquaculture Feed Blends
India's aquaculture production exceeds 17 million metric tons annually, with intensive pond systems requiring balanced feed formulations. Research trials at aquatic institutes demonstrate that carp and catfish perform well on diets containing 15-25% DDGS, reducing feed costs per kilogram of gain by 8-12%. Fish farmers serving domestic markets readily incorporate these formulations, while shrimp exporters use lower inclusion rates but acknowledge DDGS's cost advantages for domestic sales. This expanding adoption across aquaculture segments broadens the India dried distillers grain with solubles market customer base and reduces end-use concentration risk.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Uncertain GST classification and tax burden | -1.4% | Nationwide | Short term (≤ 2 years) |
| Anti-nutritional risks from excess inclusion in animal rations | -1.1% | Nationwide | Medium term (2-4 years) |
| Volatile domestic raw material prices disrupt supply | -1.6% | Grain belts | Short term (≤ 2 years) |
| Limited bulk logistics from distilleries to demand centers | -0.8% | Transport corridors | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Uncertain GST Classification and Tax Burden
The India dried distillers grain with solubles market faces GST classification challenges, as it can be categorized either as animal feed at 5% GST or as industrial by-products at 18% GST. This classification uncertainty affects pricing strategies for producers and procurement decisions for feed manufacturers. The tax classification varies for different DDGS types, including corn-based, rice-based, and blended products, which creates market fragmentation and administrative challenges. The Food Safety and Standards Authority of India requires Bureau of Indian Standards Certification for animal feeds used in food-producing animals, resulting in regulatory costs and delays that particularly impact small-scale producers[2]Source: Food Safety & Standards Authority of India (FSSAI), "FSSAI to bring animal feed under FSSA; insists on BIS compliance for now," fssai.gov.in .
Volatile Domestic Raw Material Prices Disrupt Supply
Maize prices fluctuate up to 25% between harvest and lean seasons due to concurrent demand from food, feed, and fuel sectors. This volatility affects distillery profit margins and disrupts production schedules, resulting in DDGS price variations that impact feed mills' procurement plans[3]Source: Office of Agricultural Affairs, “India: Grain and Feed Update,” United States Department of Agriculture, fas.usda.gov. Government policies on grain markets, including rice supply restrictions to distilleries and inconsistent allocation of damaged food grains, create supply uncertainties that affect DDGS production and inventory management. The competition among food, feed, and fuel sectors for grain resources increases price pressures, especially during monsoon failures or when export restrictions reduce domestic grain availability.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product Type: Corn Dominance Drives Market Foundation
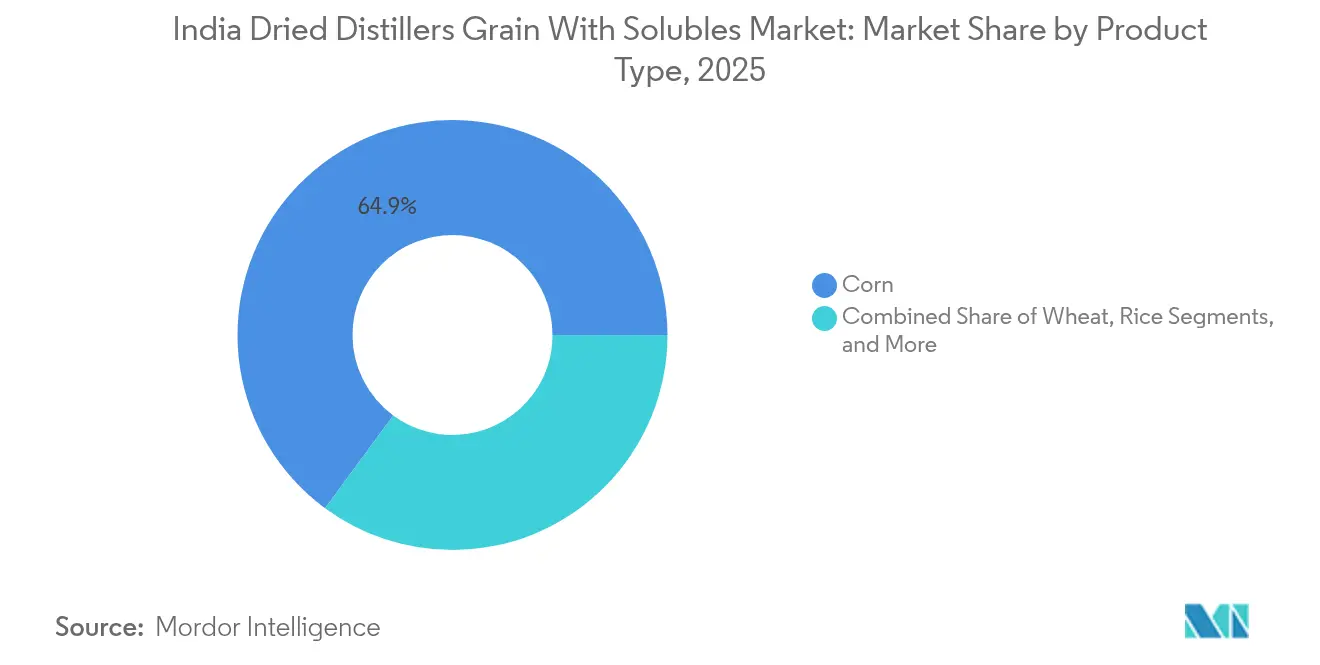
Corn accounted for 64.90% of the India dried distillers grain with solubles market share in 2025, reflecting the extensive use of maize within grain-based distilleries and its established acceptance among feed formulators. The India dried distillers grain with solubles market for corn variants benefits from consistent quality, predictable supply, and ongoing capacity additions in ethanol clusters across Maharashtra, Uttar Pradesh, and Karnataka. Industry stakeholders prefer corn DDGS due to its reliable amino acid profiles and lower variability, maintaining high inclusion rates in poultry and dairy diets. Established domestic trading networks strengthen corn DDGS distribution, enabling mills to contract forward volumes with consistent quality.
Rice is experiencing rapid growth with a 11.96% CAGR through 2031. This growth stems from government allocations of damaged and broken rice that distilleries purchase at subsidized rates of Rs 2,250 per quintal (USD 270 per metric ton) in 2025. This raw material supply ensures year-round plant utilization and provides a distinct nutrient profile valuable in fish and shrimp feeds that accommodate higher fiber content. Wheat, barley, and sorghum remain niche products but provide formulation flexibility in regions where these grains dominate crop rotations. The diverse feedstock mix enables feed mills to test blended DDGS products to optimize protein, fiber, and energy balance for species-specific diets.


By Animal Type: Poultry Leadership Faces Aquaculture Challenge
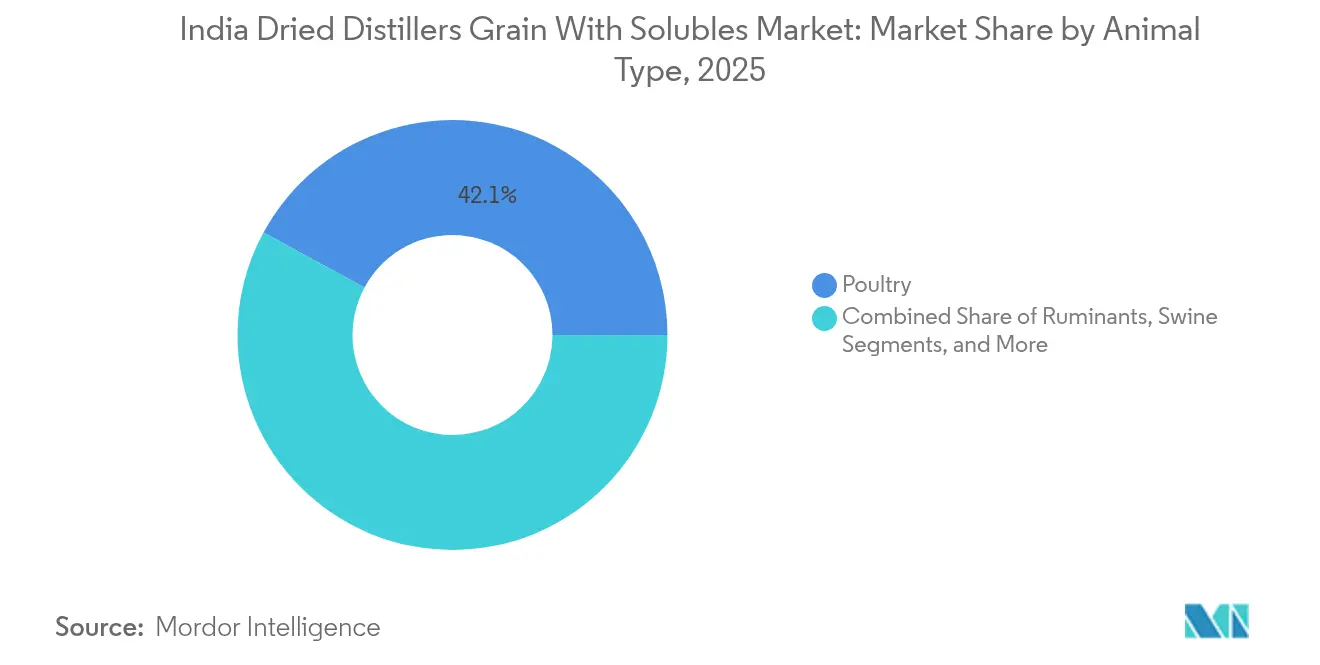
Poultry accounts for 42.10% of the India dried distillers grain with solubles market size in 2025. Large integrators utilize DDGS due to its balanced amino acid profile and metabolizable energy content comparable to corn, while offering cost advantages over soybean meal. The inclusion rates of 10-15% in broiler starter and grower diets help stabilize feed costs during ingredient price fluctuations. The consistent supply of quality-assured DDGS from organized distilleries ensures minimal impact on performance, maintaining poultry's dominant position in the market.
The aquaculture segment is projected to grow at a 13.55% CAGR through 2031. Freshwater fish farmers in Andhra Pradesh, West Bengal, and Odisha are incorporating DDGS at 15-25% in feed formulations, driven by improved feed conversion ratios and reduced ex-mill feed costs. Shrimp hatcheries are gradually adopting DDGS at 5-8% inclusion levels to reduce fishmeal dependency. The dairy and beef sectors maintain steady consumption, using DDGS fiber to enhance rumen function while managing feed costs. Despite limited adoption in the swine sector, primarily concentrated in Eastern and Northeastern India, initial trials indicate positive growth performance when DDGS substitutes traditional corn-soy combinations.
Geography Analysis
Maharashtra, Karnataka, and Uttar Pradesh form the production-consumption triangle in the India dried distillers grain with solubles market. These states control a significant portion of national ethanol capacity and house several large feed mills that integrate DDGS into poultry and dairy rations. The extensive road and rail network around Mumbai and Pune facilitates consistent dispatches to western and southern markets, while sugar and grain cooperatives ensure raw material supply for distilleries. The proximity between mills and livestock clusters reduces delivery cycles and quality losses, maintaining competitive pricing structures.
Punjab, Haryana, and Rajasthan utilize their dairy infrastructure to incorporate DDGS as a protein and energy supplement. State livestock departments promote adoption through feed quality workshops and include DDGS parameters in ration balancing programs under the National Livestock Mission. Logistics challenges exist as DDGS transportation often exceeds 1,200 kilometers from distillery hubs, increasing freight and handling costs. Feed millers address this by purchasing during post-harvest periods when freight rates decrease and maize availability increases.
Tamil Nadu, Andhra Pradesh, and West Bengal represent the fastest-growing regions for DDGS usage. Commercial aquaculture feed plants near Kakinada and Chennai incorporate rice-based DDGS in freshwater carp and catfish feeds. While export demand for shrimp sometimes limits DDGS inclusion due to international buyers' input requirements, domestic fish demand allows higher usage levels. Infrastructure improvements under the Sagarmala and Gati Shakti programs aim to enhance hinterland connectivity, reducing transit times and improving DDGS quality preservation during monsoon seasons. Eastern and Northeastern states show significant growth potential once logistics and market awareness improve.
Regulatory Landscape
DDGS marketed as an animal feed ingredient in India sits under the compliance perimeter led by the Food Safety and Standards Authority of India (FSSAI), with commercial feed materials and compound feeds requiring adherence to applicable Bureau of Indian Standards (BIS) specifications. In practice, feed buyers and manufacturers anchor quality and safety on BIS IS:2052:2009 parameters for compounded cattle feed, including an aflatoxin B1 limit of 20 ppb, and on FSSAI limits tied to food-chain outcomes such as aflatoxin M1 in milk at 0.5 micrograms per kilogram. This alignment pushes DDGS suppliers to strengthen mycotoxin control and traceability in procurement and drying.
Industry guidance is also tightening around production-side quality management. The National Dairy Development Board (NDDB) has issued guidelines for production of quality DDGS by grain-based distilleries, reinforcing expectations for consistent nutrient profiles, moisture management, and contamination controls to support use in dairy and other food-producing animals. Alongside ongoing uncertainty in GST classification, commonly debated between 5% and 18% depending on categorization, these standards and guidelines shape labeling, testing frequency, and documentation norms for DDGS movement from distilleries to organized feed mills and integrators.
Competitive Landscape
The India dried distillers grain with solubles market demonstrates moderate fragmentation, with five major suppliers controlling a significant market share in 2024: ADM (Archer Daniels Midland Company), Louis Dreyfus Company B.V., IFB Agro Industries Limited, Gulshan Polyols Limited (Gulshan Holdings Private Limited), and Nutrigo Feeds Pvt Ltd (SSL Group). Their market position stems from integrated global sourcing capabilities, strategic storage facilities near major ports, and technical service teams ensuring consistent nutrient quality. Louis Dreyfus leverages its commodity trading expertise to provide flexible pricing and blended DDGS products, while IFB Agro maintains a strong market presence in Eastern India through its distillery network's proximity to aquafeed mills.
Second-tier companies, including Gulshan Polyols Limited, Nutrigo Feeds Pvt Ltd, and Prorich Agro Foods Pvt. Ltd, compete through specialized offerings such as fractionated DDGS, mycotoxin-screened products, and custom packaging options. These companies invest in integrated logistics systems, incorporating rail sidings at production facilities and specialized truck fleets with moisture-resistant covers. They implement advanced technologies like infrared nutrient scanners to improve grading processes and reduce batch variations, enhancing their reliability ratings with major integrators.
The market sees increasing strategic collaborations between distillers and feed companies, establishing offtake agreements and sharing supply chain efficiencies. Companies are expanding into export markets, including Bangladesh, Nepal, and Vietnam, working with the Agricultural and Processed Food Products Export Development Authority (APEDA) to meet international regulatory requirements. Regional suppliers maintain their market presence by serving specific geographical areas where transportation costs affect larger competitors, contributing to the market's diverse supplier base.
India Dried Distillers Grain With Solubles Industry Leaders
-
ADM (Archer Daniels Midland Company)
-
Louis Dreyfus Company B.V.
-
IFB Agro Industries Limited
-
Gulshan Polyols Limited (Gulshan Holdings Private Limited)
-
Nutrigo Feeds Pvt Ltd (SSL Group)
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
In India, DDGS opportunities center on improving consistency and safety assurance for higher-inclusion use across organized poultry, dairy, and aquafeed channels. Buyers increasingly ask for documented quality controls aligned to FSSAI licensing expectations, BIS-linked feed parameters, and NDDB DDGS production guidance. A clear focus area is premium, quality-assured DDGS built around mycotoxin risk management, given the feed-chain sensitivity to aflatoxins, including BIS IS:2052:2009 aflatoxin B1 limits and FSSAI limits on aflatoxin M1 in milk. Suppliers that standardize testing, moisture control, and traceability can broaden acceptance with large feed mills that manage performance and residue risk across food-producing animals.
Technology-led differentiation is also becoming a nearer-term value-capture lever, especially in rice-based DDGS and aquaculture-facing formulations. IFB Agro Industries has disclosed use of low-temperature fluidized bed drying (below 70 C) for rice-based DDGS, which supports digestibility preservation for performance-sensitive feed formulators. On the supply side, investment programs linked to grain processing and bio-ethanol capacity expansion keep enlarging the domestic DDGS pool, while policy actions that opened quota-based duty concessions for DDGS imports from the United States create an additional lever for traders and large integrators to balance price and supply when domestic availability tightens or when specific nutrient specifications are needed.
Recent Industry Developments
- July 2026: IFB Agro Industries Limited - The annual report notes headwinds for its alcohol and by-product business including DDGS due to excess capacity in West Bengal and depressed price realizations. The company successfully concluded a project on DDGS digestibility in poultry feed in collaboration with a university. This underscores ongoing research activity and margin pressure in ethanol and by-product streams, while signaling continued engagement with feed innovation centers.
- June 2026: Mukka Proteins Limited - The board approved a 150 million rupee strategic investment to acquire an equity stake in Aqua Marine. The move broadens Mukka Proteins access to aquaculture inputs and supports diversification of its marine protein portfolio. The investment strengthens vertical integration and expands the company footprint in marine protein supply chains.
- June 2026: Mukka Proteins Limited - The company completed the acquisition of a 51% stake in Delta Marine Products for 11.10 crore rupees, enhancing its position in the marine protein business. The acquisition broadens Mukka Proteins downstream distribution and product mix in aquatic proteins. The deal supports scale up of its marine protein capabilities and market reach.


Research Methodology Framework and Report Scope
Market Definition and Coverage
In this methodology, the market covers the value of dried distillers grain with solubles (DDGS) sold in India for use in animal feed. It includes locally produced and imported DDGS that is commercially traded and priced in USD terms.
Scope exclusions: We exclude wet distillers grains, on-farm byproduct use that is not sold, and broader feed ingredients that are not DDGS.
Segmentation Overview
-
By Product Type
- Corn
- Wheat
- Rice
- Blended Grains
- Other Product Types (Barley, Sorghum, and Bajra)
-
By Animal Type
- Ruminants
- Poultry
- Swine
- Aquaculture
- Other Animal Types (Equine, Camel, etc.)
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the boundaries of DDGS supply and demand in India, and to build the base layers for the market model. We relied on public sources such as the Ministry of Consumer Affairs (price and commodity signals), the Department of Animal Husbandry and Dairying (livestock and dairy indicators), and the Livestock Census series to understand the feed demand pool.
We also reviewed documents from agencies such as the Food Safety and Standards Authority of India, trade and customs statistics (to reflect import flows where relevant), and technical publications that explain DDGS nutrition and inclusion rates by species. These were complemented with company filings and investor presentations, reputed press coverage of ethanol capacity additions, and selective paid subscriptions for company financials, patent databases, and shipment level import or export checks where it helped validate totals. The examples of sources mentioned here are not exhaustive, and many other references were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on validating how DDGS is actually traded and used in India, since contracts, quality specs, and adoption rates can vary by animal type and region. We spoke with participants across ethanol production, DDGS traders and distributors, feed mills, integrators, and large farms, then rechecked assumptions with nutritionists and procurement teams to close gaps left by public data.
For India-specific coverage, discussions were balanced across major consuming belts and key supply states so the model reflects practical logistics and price realization, not only theoretical capacity.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 35% | CXOs: 15% |
| Mid tier: 50% | Functional/Unit leaders: 28% |
| Smaller Players: 15% | Managers: 57% |
Market-Sizing & Forecasting
Sizing started with a top-down build that reconstructs India DDGS availability from ethanol output indicators and typical DDGS yield factors, then adjusts for drying rates and commercial saleability. After that, we corroborated results with selective bottom-up approximations such as sampled price points by region, distributor throughput checks, and a reasonableness roll up of demand from large feed consumers.
Key inputs that shaped the model included grain-based ethanol capacity additions, operating utilization trends, observed DDGS price spreads versus soybean meal and maize, typical inclusion rates by species (especially dairy and poultry), and shifts in compound feed production that influence ingredient pull-through. When bottom-up information was missing for smaller states or fragmented channels, we used proxy assumptions from adjacent markets and then corrected them using expert feedback so the final totals stayed realistic.
Forecasts were built using scenario analysis, because policy-led ethanol expansion and feed affordability can swing demand faster than a single straight-line trend. Variables such as ethanol commissioning timelines, livestock production momentum, and expected DDGS pricing were stress-tested, and the final forward curve was aligned to consensus ranges shared by industry respondents.
Data Validation & Update Cycle
Validation was done through multiple checks so one weak data series did not drive the final number. Our team compared outputs against independent signals like ethanol plant start-ups, feed industry demand direction, and import activity, and then investigated any large variances before locking assumptions.
Draft results went through stepwise analyst review, followed by targeted re-contact when an indicator moved outside the expected band (for example, a sharp change in DDGS pricing or utilization). Reports are refreshed annually, with interim updates when material events occur, and a final pre-delivery review is completed so clients receive the most current view available at the time of publication.
麻豆视频's India Dried Distillers Grain With Solubles Market Market Estimate Compared With Other Published Estimates
Published estimates for India DDGS are not always aligned, mainly because the market can be counted from different angles, such as ethanol supply potential versus realized feed consumption. Differences also come from how each publisher treats informal trade, the choice of pricing point (ex-factory versus delivered), and whether the numbers reflect a steady-state year or a transition year with new capacity ramp-ups.
In our work, the biggest gap drivers typically sit in three places, which are the assumed DDGS yield per unit of ethanol output, the share that is dried and sold versus diverted locally, and the adoption curve in poultry and ruminant diets when prices move. Currency conversion timing and refresh cadence also matter, since DDGS pricing can react quickly to grain costs and government blending momentum.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 177.42 M (2025) | |
| Industry Association A | USD 210.00 M (2025) | This estimate appears to lean on rated ethanol capacity and headline DDGS yield assumptions, without fully adjusting for drying constraints, plant ramp-up, or state-level logistics that reduce realized marketed volumes. |
| Trade Journal B | USD 150.00 M (2025) | This figure seems closer to organized channel sales only and may exclude smaller distributor flows or on-contract volumes, which can understate total commercial DDGS traded when adoption widens in dairy and poultry. |
The table shows a visible spread around the 2025 market value, and in 麻豆视频's model the number is anchored to DDGS that is actually dried and commercially sold for feed, with pricing normalized to a consistent USD basis for the year. Once capacity, utilization, and traded volume are reconciled with on-ground buying patterns, the resulting total becomes easier to trace back to clear inputs and to refresh as new ethanol plants and feed demand signals emerge.


Key Questions Answered in the Report
What is the 2026 value of the India dried distillers grain with solubles market?
The market is valued at USD 197.51 million in 2026.
How fast is the India dried distillers grain with solubles market projected to grow?
It is forecast to post an 11.32% CAGR between 2026 and 2031, reaching USD 337.57 million.
Which DDGS type leads sales in India?
Corn-based DDGS leads with 64.90% share in 2025.
Why is DDGS popular among poultry integrators?
DDGS supplies 26-30% protein at prices 15-20% below soybean meal and supports 10-15% inclusion without hurting feed conversion.
What policy supports DDGS supply growth?
India's E20 ethanol mandate spurs distillery expansion, directly generating larger DDGS volumes.
Who are the key players in India dried distillers grain with solubles space?
ADM (Archer Daniels Midland Company), Louis Dreyfus Company B.V., IFB Agro Industries Limited, Gulshan Polyols Limited (Gulshan Holdings Private Limited), and Nutrigo Feeds Pvt Ltd (SSL Group ) are the top five suppliers.
Page last updated on:



