
India Fungicide Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 227.26 Million |
| Market Size (2026) | USD 236.28 Million |
| Market Size (2031) | USD 287.05 Million |
| Growth Rate (2026 - 2031) | 3.97 % |
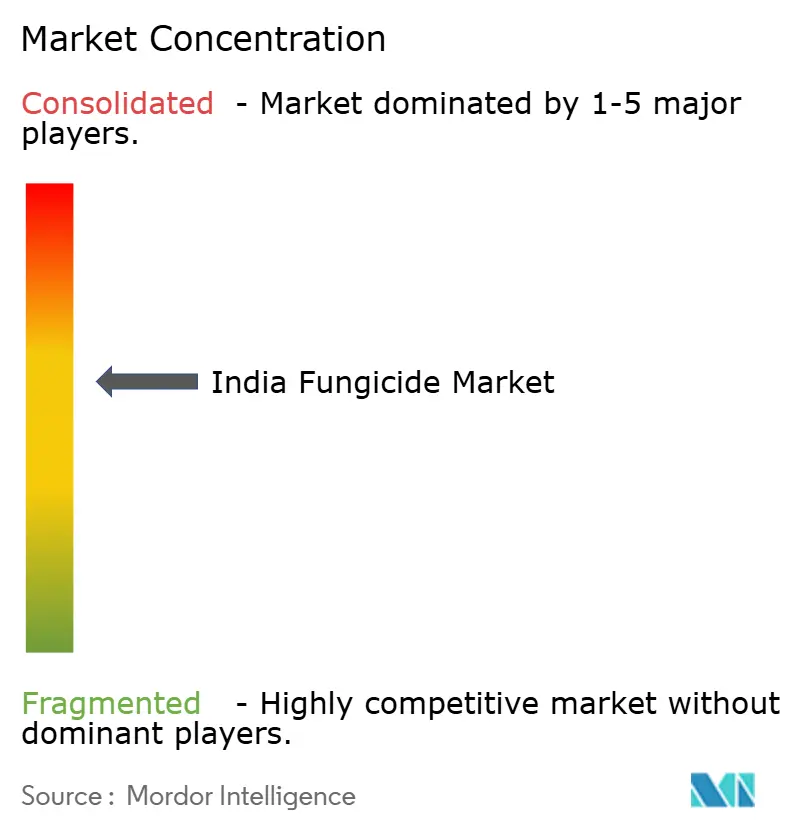
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
India Fungicide Market Analysis by 麻豆视频
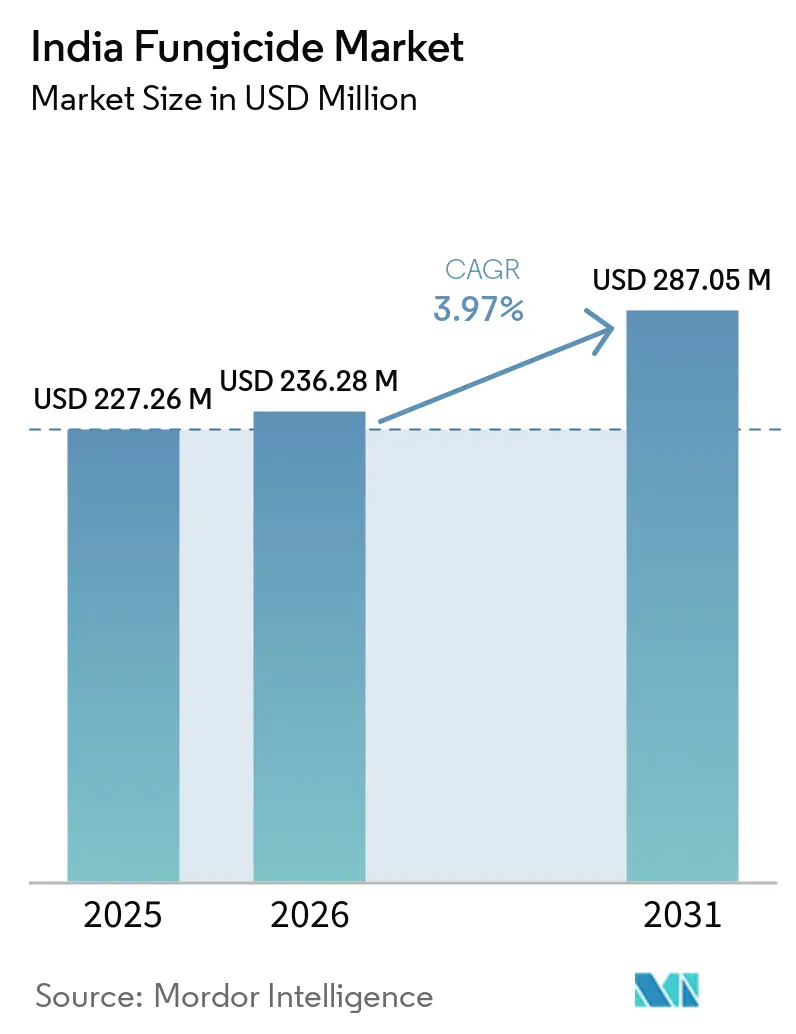
The India fungicide market size was valued at USD 227.26 million in 2025 and is forecast to grow from USD 236.28 million in 2026 to USD 287.05 million by 2031, at a CAGR of 3.97% from 2026 to 2031. Disease pressure in rice, wheat, and export-focused horticulture supports demand for fungicide products, while expanding distribution networks are improving product availability across key agricultural regions. Increasing awareness of crop-specific disease management and the need to maintain crop quality are further supporting fungicide adoption. Export-oriented crop production increases the importance of residue compliance and fungicide performance. Weather variability can increase disease risk and influence fungicide application patterns, while fluctuations in farm income can affect purchasing capacity among smallholder farmers.
Key Report Takeaways
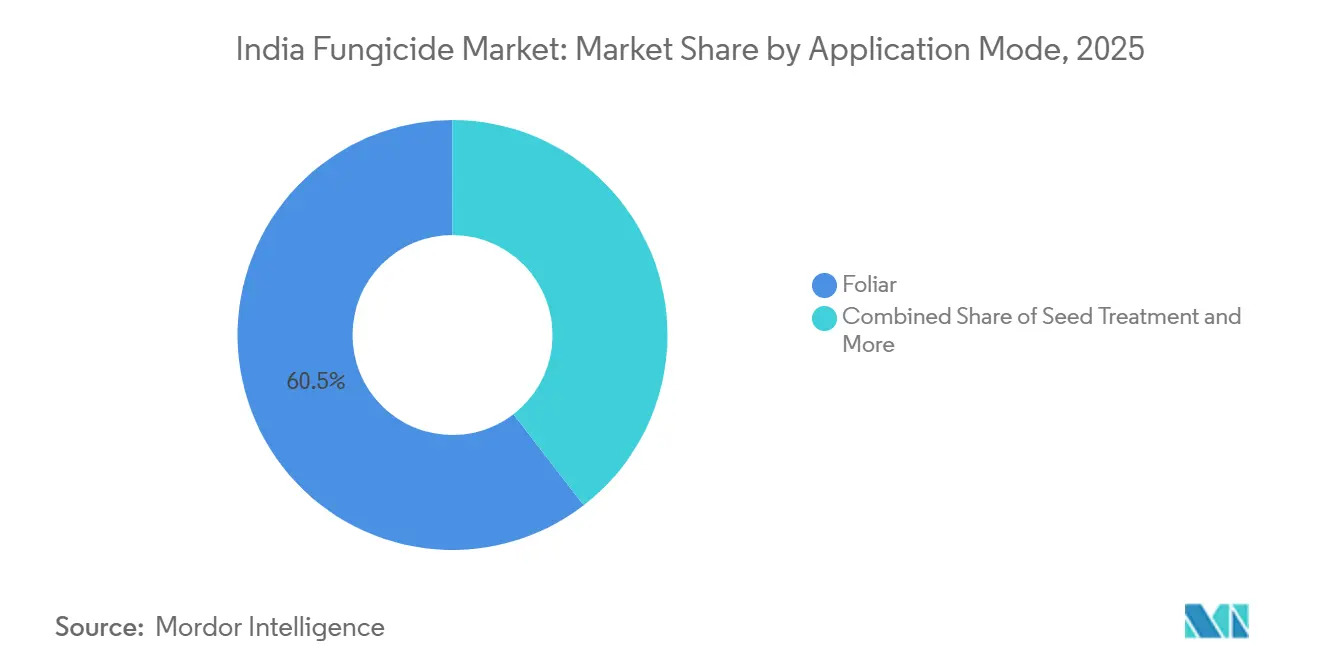
- By application mode, Foliar was the largest segment, accounting for 60.4% of the India fungicide market share in 2025, and is forecast to grow at the fastest CAGR of 4.1% from 2026 to 2031.
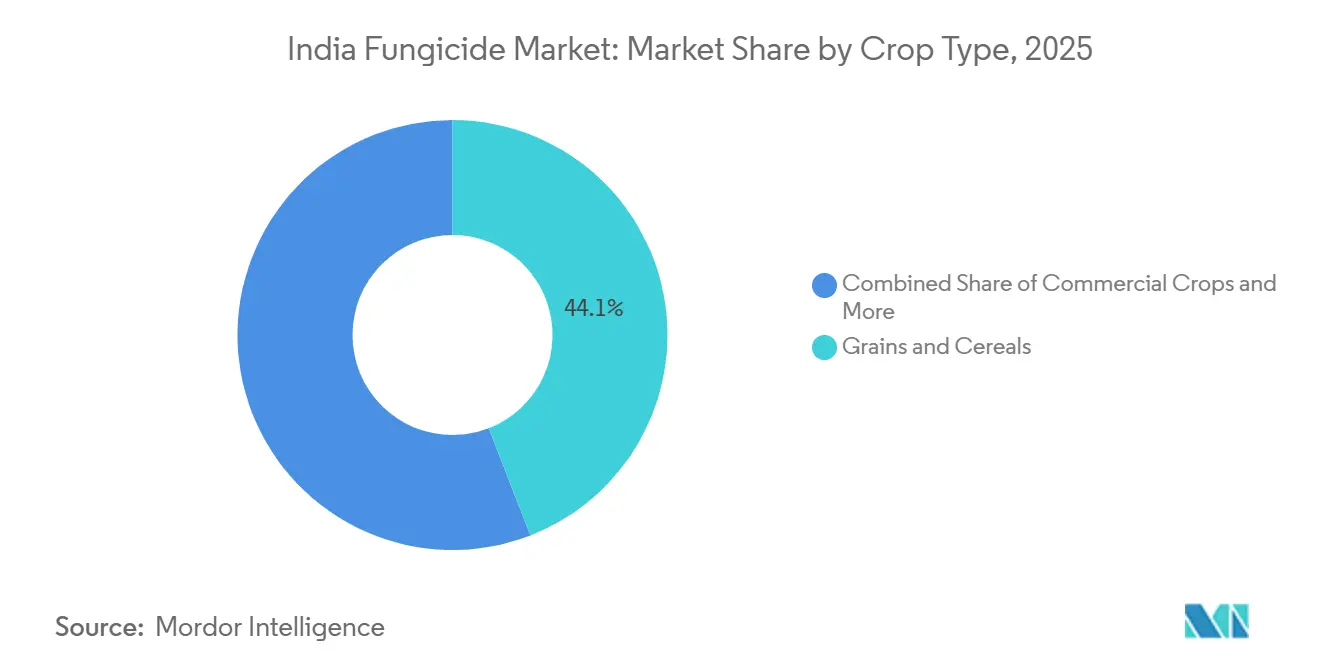
- By crop type, grains and cereals were the largest segment, accounting for 44.1% of the India fungicide market size in 2025, while commercial crops are forecast to grow at the fastest CAGR of 4.2% from 2026 to 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
India Fungicide Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Climate-driven fungal disease pressure | +1.2% | India, with the strongest relevance in rice, wheat, grape, and vegetable belts | Short term (≤ 2 years) |
| Growing adoption of registered and branded fungicide formulations | +0.8% | India, with early gains in Uttar Pradesh, Maharashtra, Karnataka, and Punjab | Medium term (2-4 years) |
| Growth of high-value horticulture and export crops | +0.7% | Maharashtra, Karnataka, Andhra Pradesh, West Bengal, and Kerala | Medium term (2-4 years) |
| Increasing adoption of preventive fungicide programs | +0.5% | Pan-India, with intensity in rice, wheat, grape, vegetable, and commercial crop belts | Medium term (2-4 years) |
| Drone spraying and application-window compression | +0.4% | Maharashtra, Telangana, Karnataka, and Punjab | Short term (≤ 2 years) |
| Local formulation and export manufacturing economies | +0.3% | Gujarat, Maharashtra, Andhra Pradesh, and Telangana | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Climate-Driven Fungal Disease Pressure
India’s diverse growing conditions expose crops to several fungal diseases across regions. Rice blast affects eastern and southern production areas, while wheat rust remains a concern in northern farming belts. Downy mildew creates recurring disease-management needs in Maharashtra’s grape-growing areas. Horticulture output reached 370.9 million metric tons in 2025-26, compared with 370.7 million metric tons in 2024-25, highlighting the scale of crop production exposed to variable growing conditions. Increasing variability in temperature, humidity, and rainfall can alter disease development and expand disease pressure into crops or regions that previously faced lower risk. As a result, the India fungicide market sees demand for combination products that address more than one pathogen risk within a crop cycle.
Growing Adoption of Registered and Branded Fungicide Formulations
Registered and labeled fungicide formulations are gaining relevance as dealer networks deepen across key agricultural states. Increasing farmer awareness of product quality, dosage consistency, and crop-specific recommendations is reducing reliance on unbranded or locally blended products. A 2025 study published in Archives of Current Research International, covering 180 cumin farmers in Gujarat, identified brand image, agro-service-center recommendations, and product performance as key factors influencing fungicide purchase decisions[1]Archives of Current Research International, "180 cumin farmers in Surendranagar district, Gujarat, found that brand image, agro-service center recommendations, and product performance", www.journalacri.com. Field demonstrations and farmer engagement further support adoption by improving awareness of disease identification and appropriate fungicide use. This shift favors established manufacturers that can provide consistent product quality alongside agronomic guidance and reliable distribution. As a result, the India fungicide market is increasingly supported by the transition toward registered, branded formulations, particularly in commercially intensive crop-growing regions.
Growth of High-Value Horticulture and Export Crops
India’s agricultural exports reached USD 52.6 billion in FY2025-26, rising 2.8% from USD 51.1 billion in FY2024-25. Export-oriented growers select crop protection products based on certification and residue requirements as well as price. Grapes, mangoes, pomegranates, and spices are key examples of this purchasing behavior. Compliance with Codex Alimentarius and destination-country residue requirements increases the relevance of newer fungicide programs. Rejected export shipments can result in costs far exceeding those of a compliant disease-management program. The India fungicide market has an opportunity to serve these growers with products that support both residue management and disease control.
Increasing Adoption of Preventive Fungicide Programs
Preventive fungicide programs are gaining importance in crops exposed to recurring disease pressure, particularly where temperature and humidity conditions favor fungal development. These programs combine crop-specific spray schedules, disease monitoring, and timely fungicide applications to manage disease pressure during susceptible crop stages. Fungal diseases such as rice blast, wheat rust, grape downy mildew, and those affecting fruits and vegetables create recurring requirements for preventive disease management. Growing emphasis on integrated disease management is encouraging growers to incorporate preventive fungicide applications into broader crop protection programs. The increased adoption of preventive fungicide programs supports timely and repeated fungicide applications across disease-prone crops, benefiting the India fungicide market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Resistance to azoles and site-specific fungicides | -0.8% | India, with strongest relevance in rice, grape, and wheat belts | Short term (≤ 2 years) |
| Residue compliance and product registration burden | -0.6% | Export horticulture and food-processing supply chains, mainly Maharashtra, Gujarat, and Punjab | Medium term (2-4 years) |
| Smallholder cash flow and weather-linked purchase volatility | -0.5% | Rainfed cereals, pulses, oilseeds, and smallholder horticulture across major crop regions | Short term (≤ 2 years) |
| Counterfeit and unregistered product leakage | -0.4% | Rural retail markets across major crop regions, especially Rajasthan, Gujarat, and Madhya Pradesh | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Resistance to Azoles and Site-Specific Fungicides
Fungicide resistance creates agronomic and commercial pressure for growers and manufacturers. A 2025 review published in Frontiers in Microbiology examined the potential link between the use of agricultural demethylation inhibitor (DMI) fungicides and azole resistance in pathogenic yeasts, highlighting concerns about cross-resistance between agricultural and clinical azoles. The Fungicide Resistance Action Committee (FRAC) lists demethylation inhibitors in Group 3 and quinone-outside inhibitors in Group 11 as high-risk groups for resistance [2]Fungicide Resistance Action Committee, “FRAC Recommendations for Fungicide Resistance Management,” Fungicide Resistance Action Committee, frac.info. Reduced sensitivity to tricyclazole in rice disease programs can require scheduled product rotations with different chemistries. These rotations add complexity and can raise procurement costs for growers with limited budgets. The India fungicide market faces shorter commercial lifetimes for individual molecules when resistance management becomes more demanding.
Residue Compliance and Product Registration Burden
New registrations require field-trial data, residue studies, and toxicological documentation. Registration costs per active ingredient were reported at USD 60,000-96,000 (INR 50-90 lakh). The 475th Registration Committee meeting in August 2026 required new formulations to meet 30-month real-time storage-stability requirements. Products also require water-contamination and bee-toxicity warnings under the stated approvals. Export-focused companies must also meet the destination country's maximum residue limit requirements. The India fungicide market, therefore, presents greater entry barriers for smaller companies that lack data-generation resources.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Application Mode: Foliar Application Leads the Market
Foliar application accounted for 60.4% of the India fungicide market share in 2025 and is forecast to grow at a CAGR of 4.1% from 2026 to 2031. This application mode remains the primary disease-management method across major crops, including rice, wheat, grapes, and vegetables, due to its ability to provide direct canopy coverage. The adoption of precision spraying technologies, including agricultural drones, is also improving application efficiency in regions facing labor shortages and field-access constraints[3]Press Information Bureau, “Namo Drone Didi Scheme Key Achievements of Digital Sky Platform,” Press Information Bureau, pib.gov.in.
Seed treatment is gaining importance in pulses and oilseeds, where fungicidal treatment can protect seeds and emerging plants from soil- and seed-borne diseases. In August 2026, the Registration Committee approved Fluxapyroxad 333 g/L FS from Seedlings India Private Limited for use across sorghum, soybean, cotton, groundnut, and potato, supporting the expansion of registered seed-treatment solutions in India. Chemigation remains concentrated in drip-irrigated pomegranate orchards in Maharashtra and vegetable farms in Himachal Pradesh, where precision delivery can limit active-ingredient waste in these higher-spending crop systems. Fumigation remains concentrated in mushroom houses and nursery operations. Soil treatment has a smaller but growing role in intensive vegetable areas of the Deccan plateau.


By Crop Type: Grains and Cereals Lead While Commercial Crops Drive Growth
Grains and cereals accounted for 44.1% of the India fungicide market size in 2025. Wheat–rice rotations across Punjab, Haryana, and western Uttar Pradesh support recurring seasonal fungicide demand, as farmers manage diseases such as rice blast and sheath blight in rice and yellow rust in wheat when weather conditions favor disease development. Commercial crops are the fastest-growing crop type and are forecast to grow at a CAGR of 4.2% from 2026 to 2031. Cotton, sugarcane, and plantation crops contribute significantly to fungicide demand. Grapes and pomegranates can have substantially higher fungicide expenditure per hectare than cereals because of intensive disease management and stringent export-quality requirements. As a result, commercial and export-oriented crops can have a greater impact on the India fungicide market than higher-volume crops where fungicide spending per hectare is lower.
Fruits and vegetables represent an important application area for fungicides, particularly across Maharashtra, Karnataka, Andhra Pradesh, and West Bengal, where diverse horticultural production supports demand for broad-spectrum and systemic products. Pulses and oilseeds primarily use targeted late-season applications across large acreage areas. Madhya Pradesh, Rajasthan, and Maharashtra’s Vidarbha region remain important locations for this demand. Turf and ornamentals account for a smaller, specialized application area, supported by demand from golf courses, institutional landscaping, and other managed green spaces.
Geography Analysis
Punjab, Haryana, and western Uttar Pradesh remain important fungicide-consuming regions, supported by intensive rice-wheat cultivation and high-input farming practices. Intensive wheat-rice rotations and established dealer credit channels support this position. Wheat rust treatment in Rabi and rice sheath blight control in Kharif create recurring seasonal demand. Himachal Pradesh forms a separate premium cluster through apple orchards. Apple growers use disease-management calendars for scab, powdery mildew, and rust across multiple spray intervals each season. Fungicide demand in this northern corridor reflects mature input distribution and regular disease-management practices.
Western and southern India represent important markets, supported by commercial agriculture and high-value horticultural production. Maharashtra and Gujarat have strong horticulture demand for grapes, pomegranates, onions, and mangoes, which often require repeated applications within each growing cycle. Export-oriented crop production also places greater emphasis on residue compliance and disease-management programs. Karnataka has demand across maize, coffee, turmeric, and vegetables. Tamil Nadu, Andhra Pradesh, and Telangana contribute demand from rice, vegetables, chili, turmeric, and cotton, while organized farmer groups support the deployment of drone-based spraying services in Telangana.
Eastern India offers a long-term growth opportunity for the Indian fungicide market, supported by disease pressure and scope for greater fungicide adoption. West Bengal's rice-growing areas face diseases such as blast and brown spot, while smaller farm holdings, limited access to formal credit, and gaps in extension coverage can constrain per-hectare spending. Central India's soybean and cotton belt represents an important fungicide-consuming region, supported by extensive cultivation of these crops and expanding distribution networks. Assam's tea plantations and horticultural areas in Sikkim and Meghalaya provide smaller but distinct demand centers. Farmer-producer organizations can further support organized input procurement across eastern and central states.
Competitive Landscape
The India fungicide market is moderately consolidated, with UPL Limited, Bayer AG, Syngenta Group, PI Industries Limited, and Rallis India Limited among the leading companies. BASF SE, Corteva Agriscience, Dhanuka Agritech Limited, Indofil Industries Limited, and Gharda Chemicals Limited are among the other notable participants. Multinational companies compete through new active ingredients, product innovation, and technical support, while domestic companies leverage distribution reach, formulation capabilities, and regional relationships.
Syngenta Group's Miravis Duo fungicide is powered by ADEPIDYN technology, while Reflect Top features Double Binding Technology. BASF SE received registration in August 2026 for a Pyraclostrobin 75 g/L plus Tricyclazole 150 g/L ZC formulation for rice blast. Dhanuka Agritech Limited completed a USD 19.2 million (INR 165 Crore) acquisition of international marketing and distribution rights for Bayer AG’s Iprovalicarb and Triadimenol fungicides in January 2025, gaining access to markets in more than 20 countries across South America, Europe, the Middle East, Africa, and Asia.
Lower-cost resistance-management programs are relevant for smallholders who cannot afford premium rotation chemistry. Drone-compatible formulations can also create opportunities for companies that connect products with certified operator networks. Digital agronomy and disease forecasting can support inventory planning and farmer engagement. Registration requirements and patent-protected molecules create entry barriers at the active-ingredient level. Companies with synthetic combinations and drone-compatible formats can address a wider range of crop and farmer needs.
India Fungicide Industry Leaders
-
UPL Limited
-
Bayer AG
-
Syngenta Group
-
PI Industries Limited
-
Rallis India Limited
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- June 2026: BASF SE Agricultural Solutions launched Melyra Fungicide in India, containing mefentrifluconazole and pyraclostrobin, expanding its fungicide portfolio for disease management across key crops, including cotton, groundnut, soybean, chili, and tomato.
- January 2025: Dhanuka Agritech Limited completed the acquisition of global marketing and distribution rights for Bayer AG's Iprovalicarb and Triadimenol fungicides for USD 19.2 million (INR 165 Crore ), covering South America, Europe, Middle East, Africa, and Asia across 20 countries.
- August 2024: Syngenta India launched Miravis Duo (pydiflumetofen plus difenoconazole) for tomato, chili, groundnut, and grape, and Reflect Top (isopyrazam plus difenoconazole) for rice, expanding its fungicide portfolio in India with new solutions for high-disease-pressure crops.


India Fungicide Market Report Scope
Fungicides are crop protection products used to control and prevent fungal diseases in crops. The market scope includes synthetic fungicides and excludes biological/biocontrol fungicides, biostimulants, and other non-synthetic disease-management products.
The India Fungicide Market Report is Segmented by Application Mode (Chemigation, Foliar, Fumigation, Seed Treatment, and Soil Treatment) and by Crop Type (Commercial Crops, Fruits and Vegetables, Grains and Cereals, Pulses and Oilseeds, and Turf and Ornamental). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Metric Tons).
| Chemigation |
| Foliar |
| Fumigation |
| Seed Treatment |
| Soil Treatment |
| Commercial Crops |
| Fruits and Vegetables |
| Grains and Cereals |
| Pulses and Oilseeds |
| Turf and Ornamental |
| By Application Mode | Chemigation |
| Foliar | |
| Fumigation | |
| Seed Treatment | |
| Soil Treatment | |
| By Crop Type | Commercial Crops |
| Fruits and Vegetables | |
| Grains and Cereals | |
| Pulses and Oilseeds | |
| Turf and Ornamental |


Market Definition
- Function - Fungicides are chemicals used to control or prevent fungi from damaging the crop and prevent yield loss.
- Application Mode - Foliar, Seed Treatment, Soil Treatment, Chemigation, and Fumigation are the different type of application modes through which crop protection chemicals are applied to the crops.
- Crop Type - This represents the consumption of crop protection chemicals by Cereals, Pulses, Oilseeds, Fruits, Vegetables, Turf, and Ornamental crops.
| Keyword | Definition |
|---|---|
| IWM? | Integrated weed management (IWM) is an approach?to incorporate multiple weed control techniques throughout the?growing season to give producers the best opportunity to control problematic weeds.? |
| Host? | Hosts are the plants that form relationships with beneficial microorganisms and help them colonize.? |
| Pathogen? | A disease-causing organism.? |
| Herbigation? | Herbigation?is?an effective method of applying herbicides through irrigation systems.? |
| Maximum residue levels (MRL)? | Maximum Residue Limit (MRL) is the maximum allowed limit of pesticide residue in food or feed obtained from plants and animals. |
| IoT? | The Internet of Things (IoT) is a network of interconnected devices that connect and exchange data with other IoT devices and the cloud.? |
| Herbicide-tolerant?varieties (HTVs)? | Herbicide-tolerant?varieties?are plant species that have been genetically engineered to be resistant to herbicides used on?crops.? |
| Chemigation? | Chemigation is a method of applying pesticides to crops through an irrigation system.? |
| Crop Protection? | Crop protection is a method of protecting crop yields from different pests, including insects, weeds, plant diseases, and others that cause damage to agricultural crops.? |
| Seed Treatment? | Seed treatment helps to disinfect seeds or seedlings from seed-borne or soil-borne pests. Crop protection chemicals, such as fungicides, insecticides, or nematicides, are commonly used for seed treatment. |
| Fumigation? | Fumigation is the application of crop protection chemicals in gaseous form to control pests. |
| Bait | ?A bait is a food or other material used to lure a pest and kill it through various methods, including poisoning. |
| Contact Fungicide? | Contact pesticides prevent crop contamination and combat fungal pathogens.? They act on pests (fungi) only when they come in contact with the pests. |
| Systemic Fungicide? | A systemic fungicide is a compound taken up by a plant and then translocated within the plant, thus protecting the plant from attack by pathogens.? |
| Mass Drug Administration (MDA)? | Mass drug administration is the strategy to control or eliminate many neglected tropical diseases?. |
| Mollusks? | Mollusks are pests that feed on crops, causing crop damage and yield loss. Mollusks include octopi, squid, snails, and slugs. |
| Pre-emergence Herbicide? | Preemergence herbicides are a form of chemical weed control that prevents germinated weed seedlings from becoming established.? |
| Post-emergence Herbicide? | Postemergence herbicides are applied to the agricultural field to control weeds after emergence (germination) of seeds or seedlings.? |
| Active Ingredients? | Active ingredients?are the?chemicals in pesticide?products that kill, control, or repel pests.? |
| United States Department of Agriculture?(USDA)? | The Department of Agriculture provides leadership on food, agriculture, natural resources, and related issues?. |
| Weed Science Society of America (WSSA)?? | The?WSSA, a non-profit professional society, promotes research, education, and extension outreach activities related to?weeds?. |
| Suspension concentrate? | Suspension concentrate (SC) is one of the formulations of crop protection chemicals with solid active ingredients dispersed in water.? |
| Wettable powder? | A wettable powder (WP) is a powder formulation that forms a suspension when mixed with water prior to spraying.?? |
| Emulsifiable?concentrate?? | Emulsifiable concentrate (EC) is?a concentrated liquid formulation of pesticide that needs to be diluted with water to?create a spray solution.? |
| Plant-parasitic nematodes?? | Parasitic Nematodes feed on the roots of crops, causing damage to the roots. These damages allow for easy plant infestation by soil-borne pathogens, which results in crop or yield loss. |
| Australian Weeds Strategy (AWS)? | The Australian Weeds Strategy, owned by the?Environment and Invasives Committee, provides national guidance on?weed management.? |
| Weed Science Society of Japan (WSSJ)?? | WSSJ aims to contribute to the prevention of weed damage and the utilization of weed value by providing the chance for research presentation and information exchange.? |


Research Methodology
麻豆视频 follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms





