
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
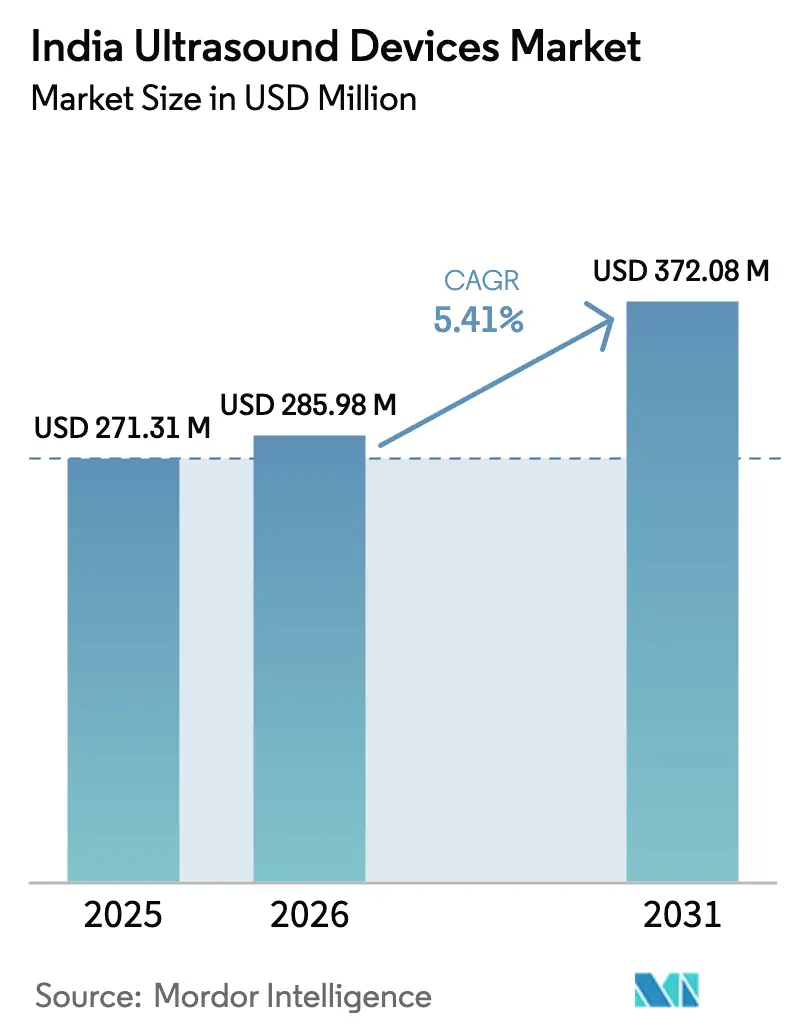
| Base Year Market Size (2025) | USD 271.31 Million |
| Market Size (2026) | USD 285.98 Million |
| Market Size (2031) | USD 372.08 Million |
| Growth Rate (2026 - 2031) | 5.41 % |
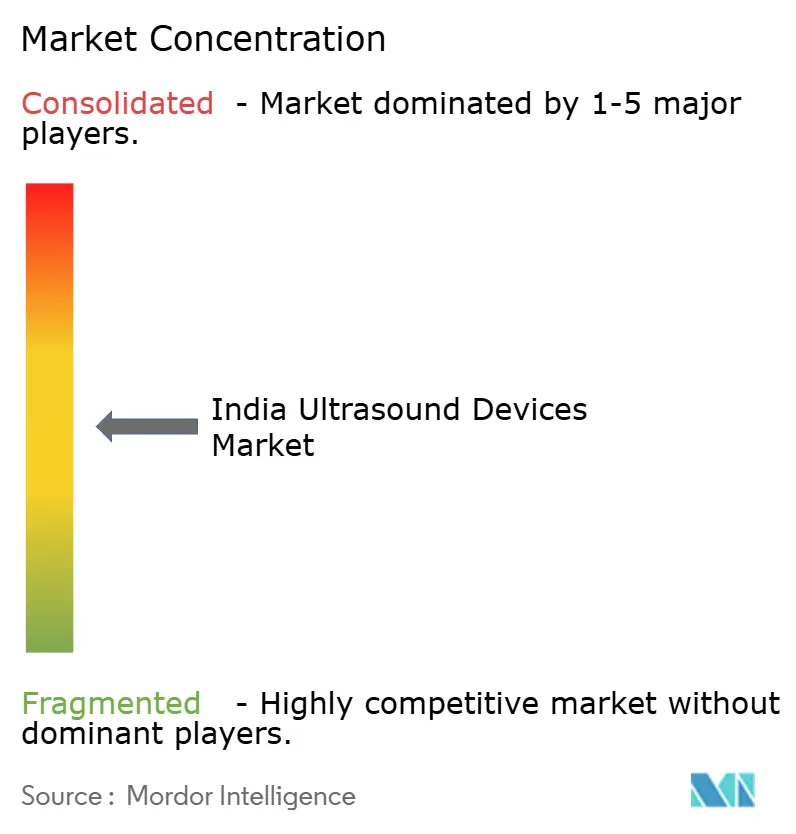
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
India Ultrasound Devices Market Analysis by 麻豆视频
The India Ultrasound Devices Market size was valued at USD 271.31 million in 2025 and estimated to grow from USD 285.98 million in 2026 to reach USD 372.08 million by 2031, at a CAGR of 5.41% during the forecast period (2026-2031).
Rising chronic-disease screening mandates, government incentives for local production, and rapid adoption of point-of-care imaging jointly sustain the expansion of the India ultrasound devices market. Multinational vendors accelerate localization through sizeable capital commitments, while indigenous manufacturers leverage the Production-Linked Incentive program to close capability gaps. Portable systems gain traction as 5G connectivity and tele-health platforms extend diagnostics into underserved districts, yet stringent CDSCO licensing and workforce shortages restrain near-term momentum. Overall, the India ultrasound devices market continues to benefit from policy-backed infrastructure spending that lifts public and private procurement across tier-1 and tier-2 cities.
Key Report Takeaways
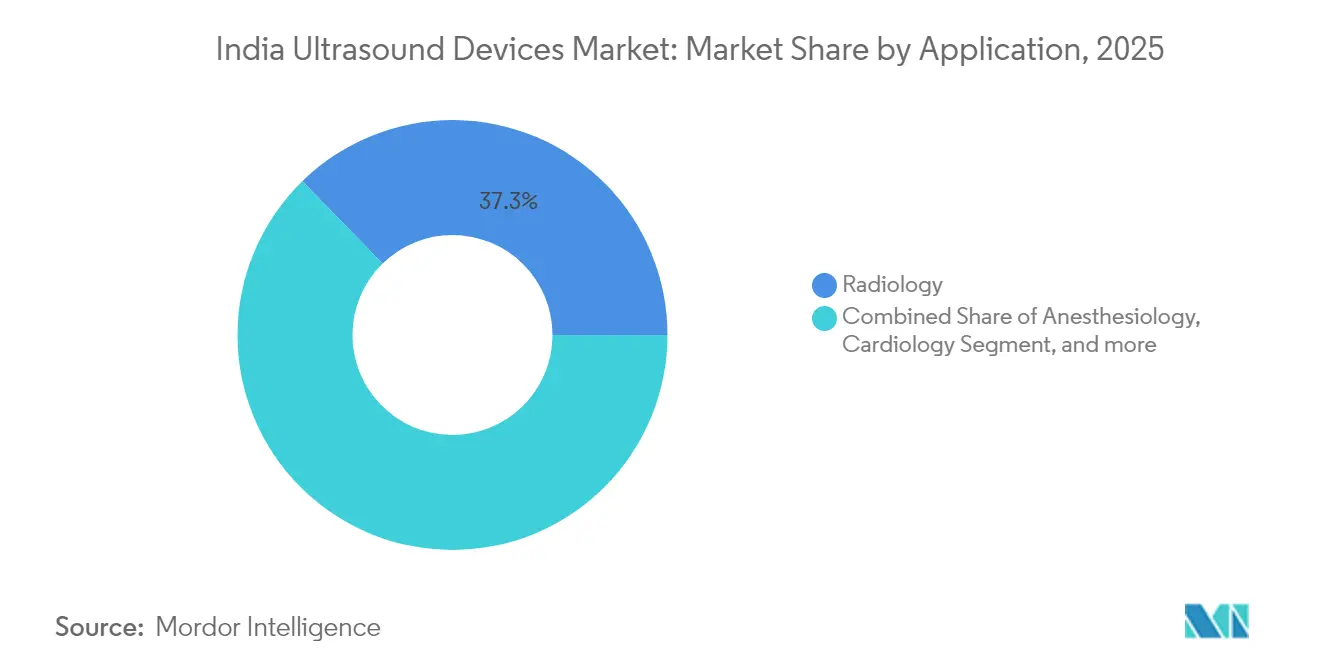
- By application, radiology led with 37.31% share of the India ultrasound devices market in 2025, while critical care posted the fastest 3.75% CAGR through 2031.
- By technology, 3D & 4D systems commanded 43.95% of the India ultrasound devices market size in 2025; high-intensity focused ultrasound is projected to grow at a 3.42% CAGR over 2026-2031.
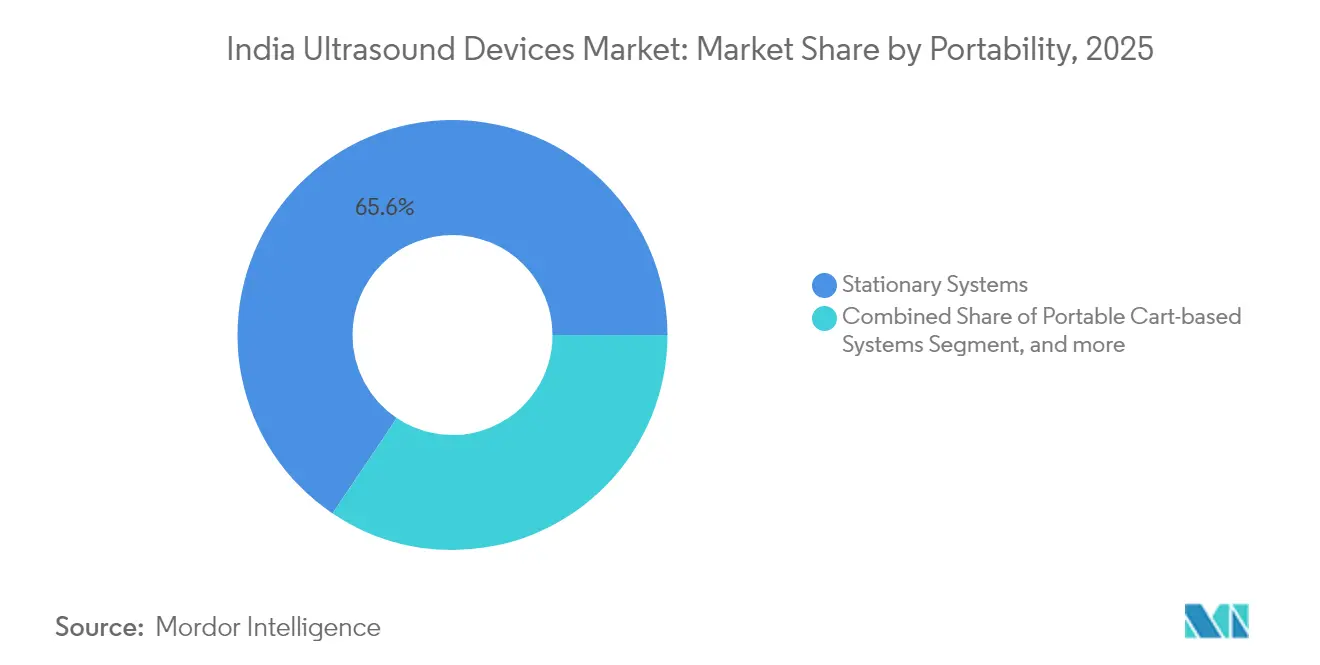
- By portability, stationary systems had a 65.58% share of the India ultrasound devices market in 2025, whereas handheld/pocket devices are advancing at a 4.63% CAGR to 2031.
- By end user, Hospitals held 52.34% share of the India ultrasound devices market in 2025, but Ambulatory Surgical Centres are forecast to expand at a 4.31% CAGR during the outlook period (2026-2031).
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
India Ultrasound Devices Market Trends and Insights
Drivers Impact Analysis Table*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Burden of Chronic Diseases | +1.2% | National, higher in urban centers | Medium term (2-4 years) |
| Growing Awareness of Early Disease Detection | +0.9% | South & West India | Short term (≤ 2 years) |
| Expansion of Portable & Point-of-Care Ultrasound | +1.1% | Rural & semi-urban, North-East focus | Medium term (2-4 years) |
| Government Healthcare Initiatives | +0.8% | National, underserved regions | Long term (≥ 4 years) |
| Local Manufacturing & Product Innovation | +0.7% | Karnataka, Tamil Nadu, Gujarat | Long term (≥ 4 years) |
| Telemedicine & Remote Ultrasound Access | +0.6% | Rural North-East & Central India | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Rising Burden of Chronic Diseases
One in four Indian adults screened at Apollo Hospitals in 2025 was hypertensive, and nearly the same proportion was diabetic, underscoring a silent epidemic that propels ultrasound from episodic diagnostic use to routine community screening.[1]Ministry of Health and Family Welfare, “NPCDCS Clinic Network Update 2025,” mohfw.gov.in NPCDCS clinics now operate across every state, embedding ultrasound into standardized protocols at primary centers.[2]Healthcare IT News, “AIIMS Delhi Oncology AI Project,” healthcareitnews.com Preventive-care financing under Ayushman Bharat further embeds structured reimbursement, while AIIMS Delhi’s oncology AI, trained on 500,000 images, exemplifies how artificial intelligence augments image interpretation and mitigates workforce gaps. The combined effect is sustained volume growth for portable units that reach urban outreach camps and rural wellness centers.
Growing Awareness of Early Disease Detection
The eSanjeevani tele-consult platform has served 340 million patients since 2021, integrating imaging referrals into virtual primary care and stimulating demand for systems that upload scans directly to cloud archives.[3]Invest India, “eSanjeevani Tele-consult Milestone,” investindia.gov.in Aster CMI Hospital’s 95%-accurate carpal-tunnel AI illustrates specialized ultrasound expansion beyond obstetrics. Hyderabad’s SMART DROP diabetic-retinopathy protocol proves how structured screening cascades into higher equipment utilization inside diabetes clinics. Ayushman Bharat reimbursement removes price friction, letting facilities deploy midrange scanners without delaying ROI, thereby accelerating the India ultrasound devices market.
Expansion of Portable & Point-of-Care Ultrasound
University of Cambridge research identified cultural and training barriers that suppress POCUS uptake, yet these constraints highlight lucrative niches for vendors that bundle remote coaching and AI-guided workflows. Siemens Healthineers’ ACUSON Maple, presented at AOCR 2025, combines battery operation, 5G uplink, and AI triage to address both metro ICUs and village health camps. Smartphone-linked handhelds from Clarius Mobile Health extend imaging to clinics lacking cart space or three-phase power, broadening reach among 25 million clinicians worldwide. Fujifilm SonoSite’s new Noida software hub reinforces local support and speeds India-specific firmware iterations.
Government Healthcare Initiatives
Union Budget 2025 raised health spending by 9.46% to INR 95,957.87 crore, financing diagnostics inside Health & Wellness Centres and subsidizing system purchases by district hospitals. The USD 400 million Production-Linked Incentive pool offsets capex for ultrasound assemblies that meet 50% domestic-value thresholds. Medical Device Parks in Himachal Pradesh and Tamil Nadu provide common utilities that cut overhead for vendors meeting India ultrasound devices market demand. National Medical Devices Policy 2023 targets USD 50 billion domestic output by 2030, anchoring long-term certainty for component suppliers.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent Regulatory Environment | -0.8% | National, higher on imports | Short term (≤ 2 years) |
| Shortage of Skilled Professionals | -0.6% | Rural & semi-urban | Long term (≥ 4 years) |
| High Cost of Advanced Systems | -0.7% | Tier-2/3 cities & rural | Medium term (2-4 years) |
| Infrastructure Gaps in Rural Areas | -0.5% | Central & North-East | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Stringent Regulatory Environment
CDSCO halted refurbished high-end imports in April 2024, citing safety, and its protracted MD-15 approvals encouraged several OEMs to divert assembly to Vietnam, delaying product refresh cycles in India. Although the National Single Window System aims to compress review times, compliance costs remain steep for start-ups. The 2024 marketing code further limits aggressive promotion but promises higher buyer trust long term.
Shortage of Skilled Professionals
Only one trained sonographer per 65,000 people serves rural clusters, restricting practical utilization once equipment arrives. New medical colleges will double graduate output by 2028, yet near-term shortages persist. GE HealthCare and NVIDIA’s autonomous scanning prototype can auto-position probes, easing operator dependence, while eSanjeevani offers remote consult layers that partially cover skill gaps.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Application: Critical Care Expands Point-of-Care Adoption
Radiology anchored a 37.31% India ultrasound devices market share in 2025 as tertiary hospitals conducted comprehensive abdominal, obstetric, and vascular exams in centralized imaging suites. Critical Care posted the highest 3.75% CAGR, propelled by trauma protocols requiring bedside echo within 5 minutes of admission and by the India ultrasound devices market size growth inside emergency departments. Portable probes allied with AI decision support amplify throughput in ICU rounds and cardiac arrest calls. Gynecology/Obstetrics sustains double-digit volume as maternal-mortality reduction remains a policy target, whereas Musculoskeletal imaging gains visibility through sports-injury clinics that value quick tendon assessments.
Cardiology extends share through AI-enabled speckle-tracking that standardizes ejection-fraction calculation, and Urology leverages ultrasound guidance for minimally invasive stone retrieval. Rising diabetic vasculopathy drives vascular-segment growth, aided by handheld Doppler integration. Unified multi-application consoles, such as GE’s Versana Premier, allow smaller hospitals to span seven specialties with a single purchase, reducing capex while widening procedure menus.


By Technology: 3D & 4D Retain Lead amid AI-Powered Upgrades
3D & 4D platforms held 43.95% of the India ultrasound devices market in 2025, favored for obstetric bonding and surgical-planning clarity. The India ultrasound devices market size for these systems benefits from AI plug-ins that shorten fetal-anomaly scans to under 90 seconds. HIFU registers a 3.42% CAGR as non-invasive liver and prostate therapies receive wider reimbursement and specialist training centers multiply. Legacy 2D scanners persist in primary centers where budgets remain tight, while Color Doppler advances in cardiology and peripheral-artery workups. GE HealthCare’s USD 51 million Intelligent Ultrasound buyout infused ScanNav Assist into workflow, highlighting competition pivoting to AI-first differentiators.
Portable “other technologies” wrap in smartphone connectivity and edge-AI lesion detection, broadening reach where radiologists are scarce. GE and NVIDIA’s self-navigating prototype underpins a future where novice users capture diagnostic-grade imagery, easing the skilled-workforce choke point across the India ultrasound devices market share landscape.
By Portability: Hand-Held Momentum Closes Access Gaps
Stationary Systems delivered 65.58% of 2025 revenues, supporting advanced studies demanding high power and multi-probe switching. The India ultrasound devices market size for hand-held/pocket units grows 4.63% annually as district hospitals deploy them in outreach vans and community health camps. Cart-based systems bridge versatility and mobility inside surgical theaters and labor wards. Handheld makers like Clarius exploit smartphone ubiquity, selling probes that weigh under 200 grams yet stream DICOM over 5G, a match for tele-supervision workflows in the India ultrasound devices market.
Siemens’ ACUSON Maple tailors rugged casings and long-life batteries to withstand intermittent power in rural South Asia. Regulatory scrutiny remains equal to stationary consoles, compelling vendors to embed hardware-level safeguards. AI diagnostic modules bundled into handhelds lift exam confidence, cementing their role as first-touch tools across triage, obstetrics, and musculoskeletal clinics.
By End User: Ambulatory Centers Surge in Outpatient Era
Hospitals secured 52.34% 2025 share as apex institutions purchase premium scanners with elastography and contrast-enhanced modes. Ambulatory Surgical Centres register a 4.31% CAGR, reflecting payer preference for same-day procedures that lower cost of care inside the India ultrasound devices industry. Diagnostic Imaging Centres retain relevance by offering bulk exam contracts to insurers and corporates. Tele-health hubs, corporate clinics, and community wellness sites emerge as “other end users,” absorbing portable systems tied to eSanjeevani’s national platform.
Ayushman Bharat coverage of ultrasound-guided biopsies lifts throughput at small ambulatory sites, reducing referral leakage. GE’s Voluson Expert refresh accelerates obstetric throughput in high-volume outpatient maternity chains, underpinning revenue diversification. AI auto-measure packages on mid-tier consoles compress exam turnaround, adding strategic value for India ultrasound devices market penetration.
Geography Analysis
Southern India leads adoption due to manufacturing clusters in Karnataka and Tamil Nadu, where Trivitron operates nine factories and Siemens staged the AOCR 2025 showcase. Western India follows, boosted by Maharashtra’s sprawling hospital networks and Gujarat’s electronic component ecosystem, including a USD 2.7 billion semiconductor facility that promises domestic transducer chip supply. Northern India capitalizes on policy proximity, with AIIMS installing India’s first indigenous MRI and piloting advanced ultrasound AI suites. Eastern India climbs on West Bengal’s public-health emphasis, though infrastructure still lags western metros. Central India Madhya Pradesh and Chhattisgarh records steady gains as state schemes finance district-hospital upgrades. The North-East, although the smallest in value, outpaces all regions in growth, fueled by CMAAY and PMJAY cashless coverage that sets ultrasound as a baseline diagnostic. Tele-medicine bridges specialist scarcity, letting scans captured in Itanagar reach radiologists in Delhi within minutes, reinforcing equitable access across the India ultrasound devices market.
Telangana’s 35 NCD clinics, having already uncovered 28,000 new diabetes and hypertension patients, illustrate how state-specific programs spike local scanner demand. NPCDCS uniform protocols ensure procurement homogeneity across all 36 states, easing vendor tendering. Manufacturing benefits cluster south and west where supply chains and skilled labor are deeper; north and east skew toward consumption. Such regional asymmetries shape inventory planning and channel strategies for companies competing in the India ultrasound devices market.
Regulatory Landscape
Ultrasound devices in India fall under the Drugs and Cosmetics Act, 1940 and the Medical Devices Rules (MDR), 2017. The Central Drugs Standard Control Organization (CDSCO) acts as the Central Licensing Authority for imports across all device classes, and for the manufacture of higher-risk Class C and Class D devices. State Licensing Authorities oversee manufacturing for Class A and Class B devices.
Registration and licensing follow the MDR 2017 classification pathway, which affects time-to-market for new and upgraded ultrasound platforms. The framework also supports localization efforts and audit readiness, as operators put supply chains and post-market compliance plans in place for both multinationals and domestic manufacturers.
Competitive Landscape
India's Ultrasound Devices Market is moderately competitive and consists of several major players. GE HealthCare, Siemens Healthineers, and Philips anchor the premium tier, each integrating AI suites that counteract operator shortages. Wipro GE’s INR 8,000 crore five-year pledge to scale local manufacturing and R&D underscores the premium players’ localization race. Trivitron leverages cost advantages from its Aloka ultrasound plant to undercut imports on mid-range carts.
Fujifilm SonoSite’s Noida hub develops AI algorithms that personalize settings for Indian body habitus, while considering probe assembly to meet PLI localization thresholds. Handheld challenger Clarius courts rural demand through smartphone-linked probes, whereas Shimadzu’s upcoming Karnataka plant hints at future diversification into medical imaging hardware. Refurbished-unit suppliers face shrinking share after CDSCO import curbs, tilting competitive leverage to firms meeting domestic content rules within the India ultrasound devices market.
India Ultrasound Devices Industry Leaders
Fujifilm Holdings Corporation
GE Healthcare
Siemens Healthineers AG
Koninklijke Philips N.V.
Mindray Medical International Ltd.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Opportunities in India are tied to policy measures that encourage domestic manufacturing and digital-enabled diagnostics. The USD 400 million Production-Linked Incentive (PLI) pool offsets capex for ultrasound assemblies that meet 50 percent domestic-value thresholds, and the Promotion of Research and Innovation in Pharma MedTech (PRIP) program backs local R&D and product development.
Philips reported that 50 percent of its AI-enabled healthcare devices are now made in India as of April 2026, and GE HealthCare committed INR 8,000 crore in 2024 for manufacturing output and local R&D. These signals align with continued expansion of diagnostic services in Tier-2 and Tier-3 cities, alongside further emphasis on portable and handheld ultrasound with AI-enabled workflows to extend rural access and care delivery.
Recent Industry Developments
- April 2026: Siemens Healthineers engaged in discussions with the Government of Karnataka to support centres of excellence in lifesciences, healthtech, and medical products, integrating R&D and manufacturing functions in its upcoming Bengaluru campus. The engagement expands Siemens Healthineers' footprint in Karnataka and deepens public-private collaboration for local capability building. The move enhances potential for localized production and advanced R&D in the regional healthcare ecosystem.
- January 2026: Fujifilm India unveiled an expanded diagnostic portfolio at IRIA 2026, including ultrasound and healthcare IT solutions to support preventive healthcare initiatives. The broadened portfolio expands Fujifilm's market reach and aligns with the government's emphasis on preventive care and digital health adoption. The development improves access to AI-enabled imaging and IT-driven workflows across Indian healthcare facilities.
- July 2025: Siemens Healthineers and Apollo Hospitals formalized a Master Research Agreement Addendum to collaborate on AI driven ultrasound imaging and liver disease management. The collaboration supports faster development of AI-based imaging capabilities and domain expertise across a leading hospital network. This partnership strengthens the deployment of advanced imaging analytics and liver disease programs in clinical settings.


Research Methodology Framework and Report Scope
Market Definition and Coverage
In this study, the market covers revenue earned from ultrasound imaging systems sold and installed in India, across hospital and non-hospital care settings. The sizing reflects device sales value in USD, aligned to how ultrasound systems are purchased, replaced, and upgraded by Indian providers.
Scope exclusions: We exclude ultrasound-related services, extended warranties, and standalone consumables, and we do not count patient procedure revenue earned by providers.
Segmentation Overview
- By Application
- Anesthesiology
- Cardiology
- Gynecology / Obstetrics
- Musculoskeletal
- Radiology
- Critical Care
- Urology
- Vascular
- Other Applications
- By Technology
- 2D Ultrasound Imaging
- 3D & 4D Ultrasound Imaging
- Doppler Imaging
- High-Intensity Focused Ultrasound
- Other Technologies
- By Portability
- Stationary Systems
- Portable Cart-based Systems
- Hand-held / Pocket Devices
- By End User
- Hospitals
- Diagnostic Imaging Centres
- Ambulatory Surgical Centres
- Other End Users
- By Region
- North India
- South India
- West India
- East India
- Central India
- North-East India
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts by mapping India-specific demand signals for imaging and diagnostics, and then linking them to device purchasing patterns. Public sources help us understand how quickly the installed base can expand and where utilization is rising, which we then convert into unit demand and value.
We typically review official and open sources such as Government of India health statistics (including NHM and MoHFW publications), the National Health Accounts series, trade and customs statistics (such as DGFT and related government trade tables), CDSCO and public procurement portals for tender activity, and peer reviewed clinical literature on ultrasound adoption and workload. These are complemented with company annual reports, investor presentations, reputable press coverage, and import-export shipment datasets accessed through an approved paid subscription when the trade split is important to validate the model. This list is not exhaustive, and we also use other sources for data collection, validation, and research clarification.
Primary Interviews and Surveys
Primary conversations are used to pressure test what we saw in public data, especially around replacement cycles, pricing moves, and which portable systems are being prioritized. We spoke with manufacturers, distributors, hospital procurement teams, and diagnostic center operators across major Indian regions, and we used their feedback to confirm assumptions and close gaps that desk sources cannot fully explain.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 26% | CXOs: 12% |
| Mid tier: 59% | Functional/Unit leaders: 40% |
| Smaller Players: 15% | Managers: 48% |
Market-Sizing & Forecasting
Market sizing is built using a top-down and bottom-up approach, but the starting point is a demand-pool reconstruction that fits India. We begin from the addressable diagnostic imaging need and translate that into ultrasound system demand using practical conversion steps, such as installed base growth, replacement activity, and procurement intensity by end user.
To keep the model grounded, a few inputs are tracked closely and refreshed during validation, such as annual ultrasound system imports versus domestic shipments, average selling price ranges by portability (portable versus stationary), replacement cycle expectations, tender driven buying in public hospitals, and the shift in case mix toward cardiology and obstetrics related usage. The totals are then cross-checked with selective bottom-up approximations, such as sampled unit volumes by channel, distributor sell-through checks, and ASP x unit builds for a subset of large states, and we scale these carefully to avoid over counting.
Forecasting is run using scenario analysis supported by a simple multivariate regression layer. Demand drivers like hospital capacity additions, diagnostic center expansion, and expected ASP movement are used as explanatory variables. Where bottom-up inputs are incomplete (for example, for smaller private clinics), we fill gaps using penetration assumptions validated in interviews, and we keep sensitivity ranges to prevent a single assumption from dominating the final number.
Data Validation & Update Cycle
Validation happens in several passes so the final numbers are not dependent on one dataset. We compare the model output with independent signals such as import trends, tender frequency, and observed replacement cycles, and then investigate any sharp jumps that do not match real purchasing behavior.
Before sign-off, the work is reviewed by another analyst, and we re-contact sources when pricing, unit demand, or policy triggers appear inconsistent with earlier inputs. Reports are refreshed annually, and interim updates are made when material events occur, such as policy changes affecting procurement or a visible shift in import pricing. Right before delivery, we complete a final check so clients receive the latest updated view.
麻豆视频's India Ultrasound Devices Market Size Versus Other Published Estimates
Published estimates for India ultrasound devices can look far apart because the underlying scope and counting rules are not the same, even when the titles sound similar. Differences usually come from whether the number is device only or device plus services, how refurbished systems are treated, and what exchange rate timing is used.
Some public figures appear to fold ultrasound service contracts and probe sales into the same total, and they can also assume a uniform price uplift across stationary and portable systems. In 麻豆视频, the value is counted as ultrasound system revenue in India, and it is kept separate from service and consumable lines so unit demand and ASP logic stay traceable.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 271.31 M (2025) | |
| Industry Association A | USD 315.00 M (2025) | Uses a broader revenue definition by combining device sales with annual maintenance contracts and probes, which lifts totals in years with large service renewals. |
| Trade Journal B | USD 240.00 M (2024) | Built from import-only tracking and a single average price, which can understate domestic shipments and can miss the portable mix shift that changes ASPs. |
Taken together, the spread mostly reflects scope and counting choices, rather than a disagreement that demand moved suddenly. Our approach stays consistent by tying value back to unit movement, realistic pricing bands, and repeat checks against trade and procurement signals, which makes the final total easier to reproduce and update.


Key Questions Answered in the Report
How large are ultrasound device sales in India in 2026?
Revenue stands at USD 285.98 million in 2026, with a projected rise to USD 372.08 million by 2031.
Which clinical area shows the fastest growth for ultrasound use?
Critical Care leads with a 3.75% CAGR through 2031, driven by emergency medicine and ICU protocols.
What is the expected growth rate for handheld ultrasound systems?
Hand-held/Pocket devices are forecast to expand at a 4.63% CAGR between 2026 and 2031.
How do government programs influence domestic production?
The USD 400 million Production-Linked Incentive plan reimburses up to 5% of local sales, prompting multinationals and Indian firms to scale India-based assembly lines.
What regulatory challenges do vendors face?
CDSCO approval timelines and a ban on refurbished high-end imports lengthen time-to-market and raise compliance costs.
Which regions are adopting point-of-care ultrasound fastest?
The North-East and Central states lead growth due to tele-medicine rollouts and targeted cashless-care schemes that reimburse diagnostic imaging.
Page last updated on:


