
Industrial AI Software Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 23.52 Billion |
| Market Size (2031) | USD 52.97 Billion |
| Growth Rate (2026 - 2031) | 17.62 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Industrial AI Software Market Analysis by 麻豆视频
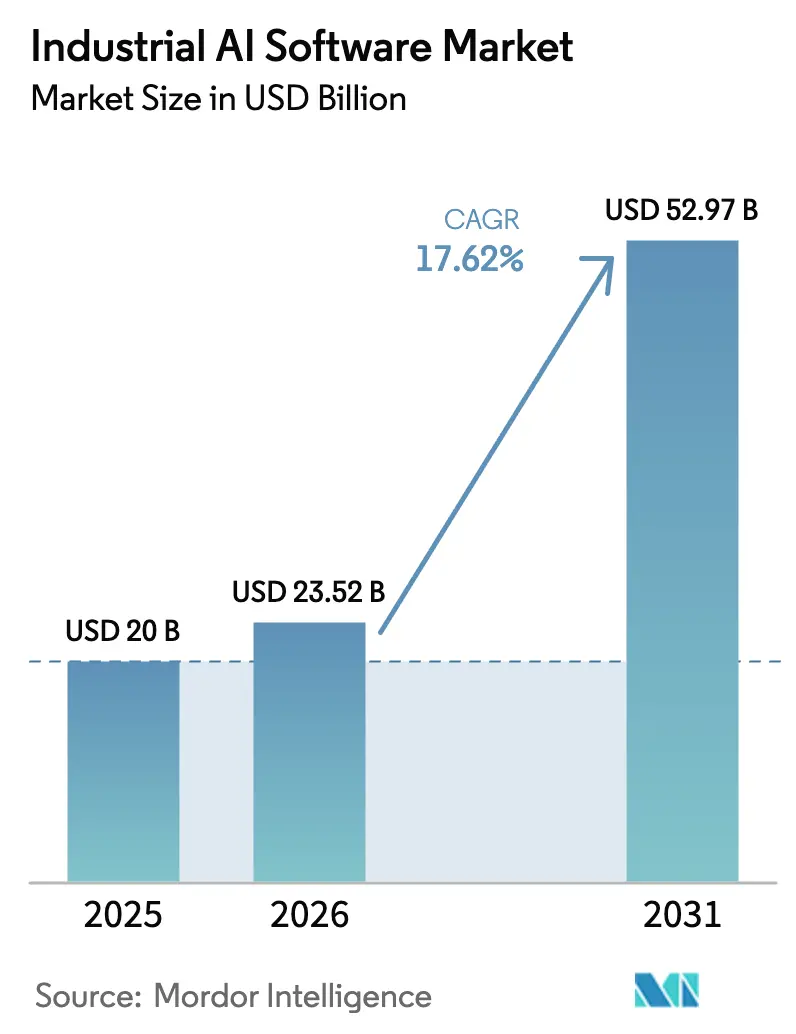
Industrial AI Software Market size in 2026 is estimated at USD 23.52 billion, growing from 2025 value of USD 20 billion with 2031 projections showing USD 52.97 billion, growing at 17.62% CAGR over 2026-2031.
This trajectory mirrors the rapid fusion of factory-floor operational technology with advanced artificial intelligence that now steers everything from process optimization to touchless documentation. Generative AI deployments spearhead this shift, Siemens recorded 90% touchless processing of delivery notes within weeks of going live, underscoring AI’s capacity to shrink manual workloads.[1]Roland Busch, “Industrial AI pushes touchless processing to new heights,” siemens.com Widespread investments in hybrid-cloud infrastructure strengthen scalability, while sovereign-cloud zones ease data-residency concerns and speed global rollouts. North America preserves its lead, but APAC’s manufacturing corridors inject the highest velocity, largely on the strength of Japan’s robotics ecosystem and China’s automation spending. Meanwhile, regulatory reforms such as the EU AI Act elevate demand for explainable solutions, encouraging vendors to add audit-grade transparency layers. Market rivalry stays moderate as hyperscalers, automation stalwarts, and niche startups jockey for early wins in predictive analytics and computer vision.
Key Report Takeaways
- By deployment type, cloud-based solutions led with 60.58% of the Industrial AI Software market share in 2025 and are projected to expand at a 19.65% CAGR to 2031.
- By end-user industry, automotive and transportation held 22.48% of the Industrial AI Software market size in 2025, while energy and utilities is poised to grow at a 21.95% CAGR between 2026-2031.
- By application, predictive maintenance was at 20.12% of the Industrial AI Software market size 2025, while the predictive maintenance sector is poised to grow at a rate of 25.75% CAGR between 2026-2031.
- By geography, North America commanded a 36.45% share of the Industrial AI Software market size in 2025; Asia-Pacific is advancing at a 20.55% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Industrial AI Software Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Predictive-maintenance adoption cuts downtime | +4.2% | Global, early uptake in North America and Europe | Medium term (2-4 years) |
| Growing volumes of industrial big-data streams | +3.8% | Global, APAC manufacturing hubs | Long term (≥ 4 years) |
| National Industry 4.0 incentive programs | +3.1% | Europe and APAC, spill-over to North America | Medium term (2-4 years) |
| Generative-AI copilots ease labor shortages | +4.5% | Global, acute impact in developed economies | Short term (≤ 2 years) |
| Carbon-accounting mandates (Scope 3) | +2.4% | Europe and North America, expanding into APAC | Long term (≥ 4 years) |
| Edge-AI deployment for real-time decisions | +2.7% | Global, asset-intensive industries | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Predictive-maintenance adoption cuts unplanned downtime
Plants now slash maintenance budgets by 25-30% and breakdowns by 70-75% after switching from calendar-based to AI-led routines. Tennessee Valley Authority spared 40,000 customer outages in two months by using AI-driven grid controls, proving that cost avoidance scales well in capital-intensive utilities. Bosch’s Ansbach site moved defect detection to edge-based vision AI, keeping latency low and inspectors focused on higher-value tasks.[2]Bosch Group, “AI Vision systems improve defect detection at Ansbach,” bosch.com Forward-looking operators view these gains as vital because every hour of unplanned stoppage can cost USD 50,000 or more.
Growing volumes of industrial big-data streams
Single factories now generate terabytes of sensor output per day, creating fertile ground for machine-learning models. Ndustrial processes 100 million data points daily across 122 plants, illustrating why data infrastructure is edging toward cloud-native lakes that feed AI pipelines. Yet inconsistent naming conventions and siloed historians remain bottlenecks, urging CIOs to invest in semantic layers that boost model accuracy and shorten training cycles.
National Industry 4.0 incentive programs
Germany’s Innovation Park Artificial Intelligence and Japan’s regional AI sandboxes subsidize pilot projects, lowering risk for small and mid-size manufacturers. Such shared testbeds accelerate learning curves, standardize data-sharing rules, and create positive network effects across supplier tiers.
Generative-AI copilots ease engineering labor shortages
Retiring experts take tacit know-how with them, yet generative AI plugs the gap by translating decades of ladder-logic scripts into modern code within seconds. Siemens Industrial Copilot now sits inside its TIA Portal and halves PLC programming time. Likewise, a Daikin-Hitachi AI agent diagnoses HVAC faults with 90% accuracy in 10 seconds, lifting junior technician productivity.
Restraints Impact Analysis of Industrial AI Software Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data-sovereignty and IP-protection concerns | -2.8% | Europe and APAC, regulatory spillover global | Medium term (2-4 years) |
| Scarcity of OT-AI integration talent | -2.1% | Global, acute in developed markets | Long term (≥ 4 years) |
| Legacy automation infrastructure lock-in | -1.9% | North America and Europe, aging asset base | Long term (≥ 4 years) |
| GPU hardware supply volatility | -1.4% | Global, concentrated impact on edge sites | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Data-sovereignty and IP-protection concerns
The EU AI Act categorizes many factory-floor algorithms as high-risk, mandating local data retention and audit trails. Multinational manufacturers, therefore, spin up sovereign clouds, AWS earmarked EUR 7.8 billion for such European zones, to meet residency rules while still tapping hyperscale AI services aws.amazon.com. Separate deployments inflate costs, but firms weigh them against the penalties of non-compliance.
Scarcity of OT-AI integration talent
Industrial AI demands rare hybrids who grasp both legacy PLC networks and modern ML frameworks. Hitachi plans to upskill 50,000 staffers in AI disciplines, highlighting the urgent workforce gap. Without these cross-domain professionals, AI pilots risk stalling at proof-of-concept stages, slowing adoption curves.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Industrial AI Software Market Segment Analysis
By Deployment Type:
Cloud Dominance AcceleratesCloud-based solutions accounted for 60.58% of the Industrial AI Software market share in 2025 and posted the strongest trajectory at 19.65% CAGR through 2031 as firms consolidate workloads on scalable, pay-as-you-grow platforms. The Industrial AI Software market size for cloud deployments is forecast to reach USD 35.54 billion by 2031, reflecting rising confidence in multi-tenant security models. Hybrid architectures further alleviate sovereignty fears by isolating sensitive datasets on regional nodes while feeding anonymized features to central model training hubs.
On-premise installations remain critical in regulated verticals that demand deterministic latency and strict asset control. Fortune 2000 manufacturers often retain on-site clusters to dodge unpredictable egress fees from cloud activity spikes, yet they increasingly orchestrate these clusters through the same containerized stacks used in the cloud. Consequently, both deployment archetypes now complement rather than cannibalize each other, stimulating continual spending across the Industrial AI Software market.


By End-User Industry:
Energy Transformation Leads GrowthEnergy and utilities is the breakout performer, advancing at 21.95% CAGR as autonomous refinery trains and self-healing grids transition from pilots to production. ENEOS and Preferred Networks unveiled full AI-run crude distillation units, proving industrial AI can handle multi-variable processes without human intervention. Automotive and transportation still tops revenue at 22.48% of the Industrial AI Software market size due to entrenched investments in autonomous driving and continuous-flow assembly lines.
Electric utilities funnel budgets into grid-aware reinforcement-learning models that shave peak-load spikes and optimize heat-rate efficiency. Conversely, aerospace, healthcare, and retail sectors diversify demand with domain-specific computer-vision and supply-chain tools, ensuring the Industrial AI Software market enjoys growth from multiple industry lanes rather than a single dependency.

By Application:
Predictive Maintenance Drives AdoptionPredictive maintenance secures the largest revenue slice as plants realize tangible savings, cost cuts hit 30% and breakdowns plunge 70% after AI implementation. The market benefits because these savings directly fund further AI rollouts across inspection, logistics, and safety. Quality inspection and vision follow, fueled by GPU-accelerated cameras that spot surface anomalies beyond human perception.
Process optimization applications ride on unsupervised-learning models that unearth hidden correlations between temperature curves, vibration signatures, and yield, driving incremental but compounding efficiency. Supply-chain and asset tracking gains momentum where AI fuses indoor RTLS signals with ERP data for end-to-end material visibility. Emerging safety and compliance analytics adds another high-growth pocket, converting video feeds into proactive hazard alerts that curtail workplace incidents.
Geography Analysis
North America Industrial AI Software Market
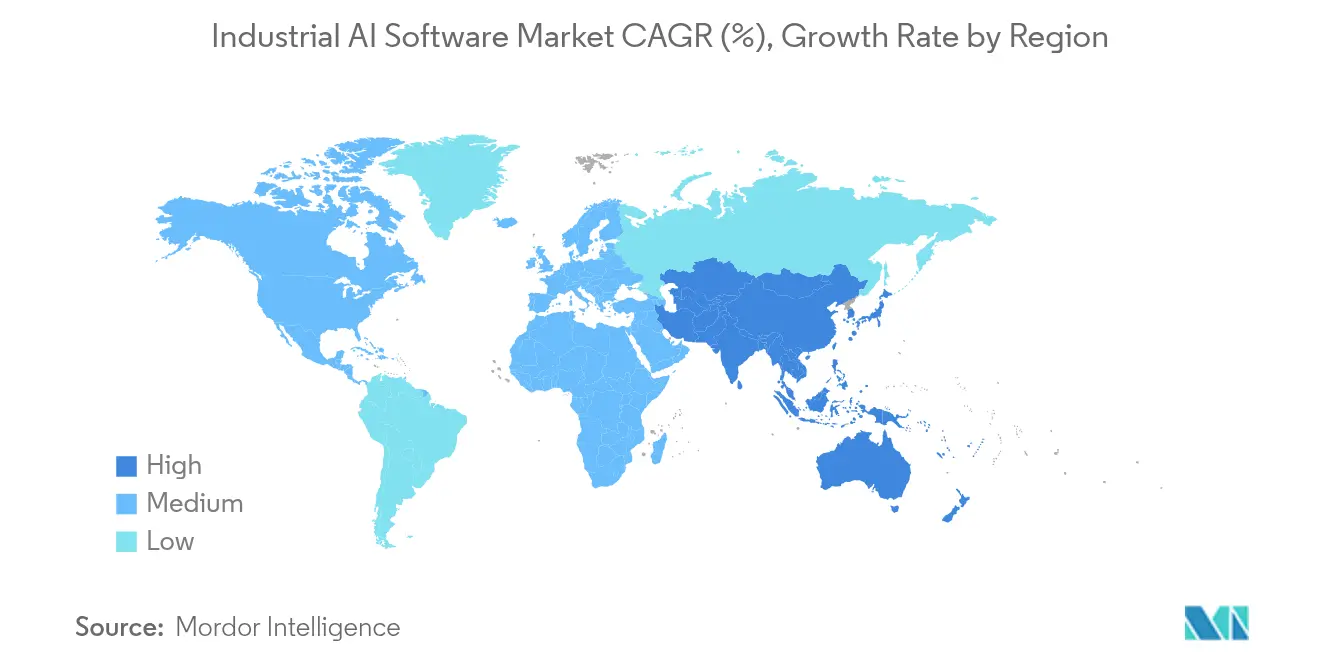
North America contributed 36.45% of the Industrial AI Software market size in 2025, thanks to strong vendor-customer ecosystems and deep cloud penetration. IBM alone booked USD 6 billion in generative-AI orders in 2025 as manufacturers prioritized cognitive upgrades over traditional IT refresh cycles. Microsoft surpassed USD 245 billion in revenue by integrating AI copilots into its software stack, supporting industrial developers with pre-trained models.
APAC Industrial AI Software Market
Asia-Pacific is the speed leader, expanding at 20.55% CAGR to 2031. Japan’s factories pilot AI-augmented robotics that showcase near-zero downtime, while Chinese state programs funnel subsidies into smart manufacturing clusters. Regional AI investments are set to reach USD 3.4 billion in 2025, nearly triple 2024 outlays, and a 160% bump in China alone illustrates policy-driven urgency.
EMEA and South America Industrial AI Software Market
Europe follows close behind, shaped by rigor around data sovereignty. The Industrial AI Software market here pivots on secure data-spaces such as GAIA-X that let suppliers share telemetry without ceding control to platform operators. Middle East, Africa, and South America charts show mixed but rising adoption. Oil-rich Gulf nations adopt AI to optimize refinery throughput, whereas Latin American producers leapfrog legacy MES layers by directly adopting cloud-native AI suites, sidestepping the technical debt faced in mature economies.

Regulatory Landscape
Regulation around industrial AI software is tightening around safety, transparency, and data governance, with particular focus on factory-floor and critical-infrastructure use cases. In the European Union, the EU AI Act (Regulation (EU) 2024/1689) entered into force in August 2024 and sets a timetable that culminates in broad applicability by August 2026, pushing suppliers toward high-risk system controls such as documented risk management, auditability, and human oversight. It also reinforces data-residency and sovereignty design choices in deployments.
In the United States, federal policy direction in late 2025 and March 2026 emphasized a more unified national approach, including recommendations for federal preemption of conflicting state AI laws and sector-specific standards development through established bodies. Standards and guidance activity, including NISTs 2026 roadmap for AI and machine learning in smart manufacturing, offers a practical reference point for manufacturers and vendors aligning industrial AI software to measurable implementation and governance practices. The United Kingdom continues with a regulator-led, principles-based approach, and its 2026 AI Adoption Plan for advanced manufacturing highlights programmatic support that complements compliance-driven adoption in Europe.
Value Chain Analysis
The industrial AI software value chain starts upstream with compute and infrastructure enablers (GPUs/accelerators, storage, networking, and edge hardware) that shape training and inference economics. It then moves into cloud and hybrid platforms that provide orchestration, security, and data services. Above this sits the industrial data foundation layer, including connectors to historians, SCADA/MES/ERP systems, and semantic modeling to normalize plant telemetry, which then feeds AI toolchains such as model frameworks, MLOps, and simulation or digital-twin environments. Vendor ecosystems increasingly bundle these layers, including GPU-accelerated libraries and digital-twin stacks, which industrial software providers integrate into design, engineering, and operations workflows.
Downstream, domain platforms and application software convert models into operational outcomes, including predictive maintenance, vision inspection, process optimization, and safety analytics. These solutions are often deployed as cloud, hybrid, or edge-managed packages depending on latency and sovereignty needs. Systems integrators and industrial automation providers handle OT/IT integration, validation, and lifecycle support, while governance requirements like audit trails and cybersecurity expectations referenced in industry standards and roadmaps, including NIST smart manufacturing guidance, influence vendor selection, deployment architectures, and ongoing monitoring services.
Competitive Landscape
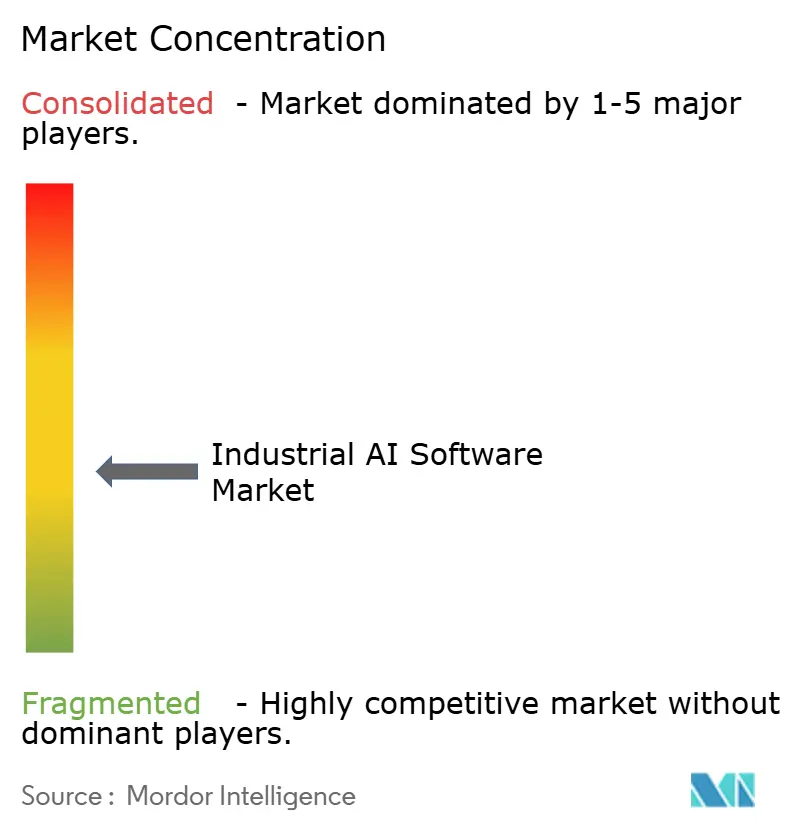
The Industrial AI Software market is moderately concentrated as automation giants, cloud hyperscalers, and deep-tech startups vie for early standard-setting positions. Siemens closed a USD 10.6 billion takeover of Altair Engineering to blend simulation with AI-guided design workflows, showcasing how incumbents acquire niche IP to keep pace with rapid algorithmic advances. IBM spent USD 7.1 billion on HashiCorp to bolster hybrid-cloud tooling that underpins industrial AI deployments.
Startups differentiate by focusing narrowly on pain points, computer-vision firms embed defect-detection models into smart cameras that drop into existing conveyor lines, while predictive-analytics vendors offer subscription models that tie fees to tangible downtime reductions. Partnerships further color the landscape: Honeywell joined forces with Chevron to encode decades of refining know-how into AI-assisted alarms that guide operators in real time. Patent filings spike around edge inference and continuous learning, signaling a race to lock in defensible micro-niches before the market settles.
Despite heightened competition, barriers to entry persist: success demands both domain knowledge and industrial-grade reliability standards such as IEC 62443 security compliance. Vendors that marry AI engines with established SCADA connectors or PLC libraries win easier acceptance, suggesting platform integration is as critical as algorithmic finesse.
Industrial AI Software Industry Leaders
IBM Corporation
Intel Corporation
Nvidia Corporation
Microsoft Corporation
Siemens AG
- *Disclaimer: Major Players sorted in no particular order
Industrial AI Software Market Companies Covered in this Report
- IBM Corporation
- Intel Corporation
- NVIDIA Corporation
- Microsoft Corporation
- Siemens AG
- Oracle Corporation
- Cisco Systems Inc.
- Veritone Inc.
- Advanced Micro Devices
- Google LLC
- GE Vernova
- Honeywell International
- ABB Ltd.
- Schneider Electric SE
- Rockwell Automation
- Bosch Rexroth AG
- Amazon Web Services
- Hitachi Ltd.
- PTC Inc.
- AspenTech

Market Opportunities and Future Outlook
A major whitespace area is productized agentic and copiloted workflows that reduce engineering effort across planning, commissioning, and continuous improvement, while still meeting industrial controls and audit requirements. In 2026, Siemens moved this direction by making its Industrial AI Suite and Eigen Engineering Agent generally available, signaling a shift from point analytics toward software that can execute defined automation engineering tasks within governed boundaries. The same agentic theme also appeared at Hannover Messe 2026, where Microsoft highlighted industrial intelligence scenarios built on Azure services, creating additional entry points for solution providers that package repeatable templates for specific production lines, plants, and asset classes.
Digital twin plus AI co-design is another opportunity area where interoperability and reference architectures remain fragmented across industries and geographies. In 2026, Siemens and NVIDIA expanded collaboration around an Industrial AI operating system concept and an adaptive manufacturing blueprint at Siemens Electronics Factory in Erlangen, while NVIDIA also broadened work with multiple industrial software leaders to bring GPU-accelerated AI into design, engineering, and manufacturing toolchains. Taken together, these initiatives leave room for industrial AI software vendors to bridge simulation, operations data, and edge execution with traceability controls aligned to tightening governance timelines, notably the EU AI Act milestones through August 2026, and to deployment patterns that address data sovereignty through hybrid and sovereign-cloud configurations.
Recent Industry Developments in Industrial AI Software Market
- July 2026: NVIDIA Corporation announces partnership with Noetra Corp. and METI to launch a national physical AI infrastructure factory for the FRONTia Project, including 13,750 Vera CPUs and 27,500 Rubin GPUs. The initiative establishes national-scale hardware infrastructure for industrial AI and accelerates agentic manufacturing capabilities across industry.
- July 2026: Kawasaki Heavy Industries collaborates with NVIDIA to implement a next-generation digital shipyard using physical AI and digital twin technology at the Sakaide Works. The collaboration supports AI-driven shipyard modernization and digital twin adoption, reinforcing industrial fleet optimization and AI integration in shipbuilding.
- April 2026: Siemens AG announces general availability of the Industrial AI Suite and Eigen Engineering Agent for automation planning and execution. The release expands a scalable industrial AI platform with autonomous agents and accelerates adoption of AI-native workflows across manufacturing lines.


Industrial AI Software Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the industrial AI software market covers paid software and platform revenue used in industrial operations to build, deploy, and run AI models for production, asset, and quality outcomes, across on-premise and cloud deployments.
Scope exclusions: Hardware (sensors, controllers, servers), pure connectivity, and non-software services such as standalone consulting and systems integration are excluded.
Segments Covered in This Report
- By Deployment Type
- Cloud-based
- On-premise
- By End-user Industry
- Automotive and Transportation
- Retail and CPG
- Healthcare and Life Sciences
- Aerospace and Defense
- Energy and Utilities
- Other Industries
- By Application
- Predictive Maintenance
- Quality Inspection and Vision
- Process Optimization
- Supply-chain and Asset Tracking
- Safety and Compliance Analytics
- By Geography
- North America
- South America
- Europe
- Asia-Pacific
- Middle East and Africa
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market context, build a clean demand map, and sanity-check the model with public indicators. We relied on public sources such as the US Census Bureau and Bureau of Labor Statistics for manufacturing output and investment signals, Eurostat for comparable industrial activity series, and the International Energy Agency for energy use and efficiency-linked digitization signals.
To anchor technology adoption and use-case language, references were also taken from sources such as NIST publications, ISO and IEC standards, and selected peer-reviewed papers that describe industrial AI deployment patterns. Company annual reports, earnings transcripts, product notes, and reputable press were reviewed to understand commercialization paths and typical packaging of industrial AI software inside broader digital offerings, usually supported by paid subscriptions for company financials, news, and patent lookups when details were unclear. This list is illustrative only, and many other sources were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on confirming what is actually purchased as industrial AI software, and how it is priced in real deployments (subscription, usage-based, or license plus maintenance). We spoke with a mix of software providers, industrial end users, and implementation partners across major regions, so assumptions around adoption timing, renewal behavior, and deployment split could be corrected when desk research signals were not specific enough.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 27% | CXOs: 12% | APAC: 47% |
| Mid tier: 56% | Functional/Unit leaders: 38% | EMEA: 30% |
| Smaller Players: 17% | Managers: 50% | Americas: 23% |
Market-Sizing & Forecasting
Sizing started with a top-down demand pool build-up that uses industrial production and digitization spend signals to reconstruct where AI software budgets sit inside plant and asset software stacks, followed by splits by deployment and major end-use industries. Results were then corroborated with selective bottom-up approximations, where sampled vendor revenue ranges, channel checks, and typical price-per-site or price-per-user bands were applied to adoption counts to check for overstatement.
Inputs that were tracked include manufacturing output trends, capital spending cycles in discrete and process industries, cloud versus on-premise preference in regulated plants, the mix of key applications such as predictive maintenance and visual quality inspection, and observed renewal and expansion behavior after initial pilots. For forecasting, scenario analysis was used, with adoption curves and average contract values adjusted using expert views on AI governance maturity, talent availability, and the pace of edge and cloud infrastructure readiness. When bottom-up signals were incomplete, gaps were handled by using conservative penetration ranges and then tightening them through follow-up calls on pricing and deployment intensity.
Data Validation & Update Cycle
Model outputs were checked against independent signals, such as software revenue disclosures, reported industrial digital investment themes, and consistency of implied spend per site versus what users described in interviews. Outliers were reviewed in a second pass, and assumptions were reworked when a single data point drove too much of a regional or application total.
Before sign-off, the work goes through multi-step analyst reviews that check variance by geography, unrealistic adoption jumps, and price inflation that does not match contract reality. Reports are refreshed annually, with interim updates when material events change demand, pricing, or deployment patterns. Right before delivery, a final refresh pass is completed so clients receive the latest updated view.
麻豆视频's Industrial AI Software Market Sizing Compared With Other Published Estimates
Published market sizes for industrial AI software can look far apart, even when the topic sounds similar, because the included revenue lines are not always consistent and base years are not aligned. Differences also come from how vendors bundle AI features into broader industrial software, which can cause double counting if not carefully separated.
Systems integration and consulting revenue sits outside 麻豆视频's scope for this market, and that single exclusion often pulls totals down versus estimates that treat full program spending as software. Other gaps usually come from counting hardware-enabled edge stacks, using aggressive adoption ramps after pilot announcements, applying uniform price growth without checking contract structures, and updating currency conversion at different times in the year.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 23.52 B (2026) | |
| Trade Journal A | USD 43.60 B (2024) | Uses a broader industrial AI definition that blends software with services and other stack elements, and it also cites a different base year which lifts the reported total versus a software-only view. |
| Industry Publisher B | USD 12.30 B (2024) | Appears to apply a narrower software perimeter and a slower adoption curve, which can undercount enterprise-wide rollouts where AI is purchased as part of industrial software suites. |
The table shows that the widest spreads usually come from what is counted as software revenue versus adjacent services, and from base-year alignment. By keeping the scope tied to software and validating adoption and pricing with repeatable checks, the estimate stays traceable to clear inputs and can be updated in a consistent way.


Key Questions Answered in the Report
What is the current size of the Industrial AI Software market?
The Industrial AI Software market is valued at USD 23.52 billion in 2026.
How fast will the Industrial AI Software market grow?
The market is forecast to post a 17.62% CAGR, reaching USD 52.97 billion by 2031.
Which deployment model grows the fastest?
Cloud-based deployment leads both revenue and growth, expanding at a 19.65% CAGR through 2031.
Which industry segment will be the top growth driver?
Energy and utilities is projected to lead with a 21.95% CAGR as utilities automate grids and refining.
What region shows the highest growth momentum?
Asia-Pacific records the strongest pace at 20.55% CAGR, powered by Japanese and Chinese manufacturing investments.
How does regulation affect adoption in Europe?
The EU AI Act classifies many factory applications as high-risk, driving demand for sovereign-cloud and explainable-AI solutions.
Page last updated on:



