
Japan Data Center Server Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Historical Data Period | 2020 - 2024 |
| Market Size (2026) | USD 26.92 Billion |
| Market Size (2031) | USD 58.16 Billion |
| Growth Rate (2026 - 2031) | 16.66 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Japan Data Center Server Market Analysis by 麻豆视频
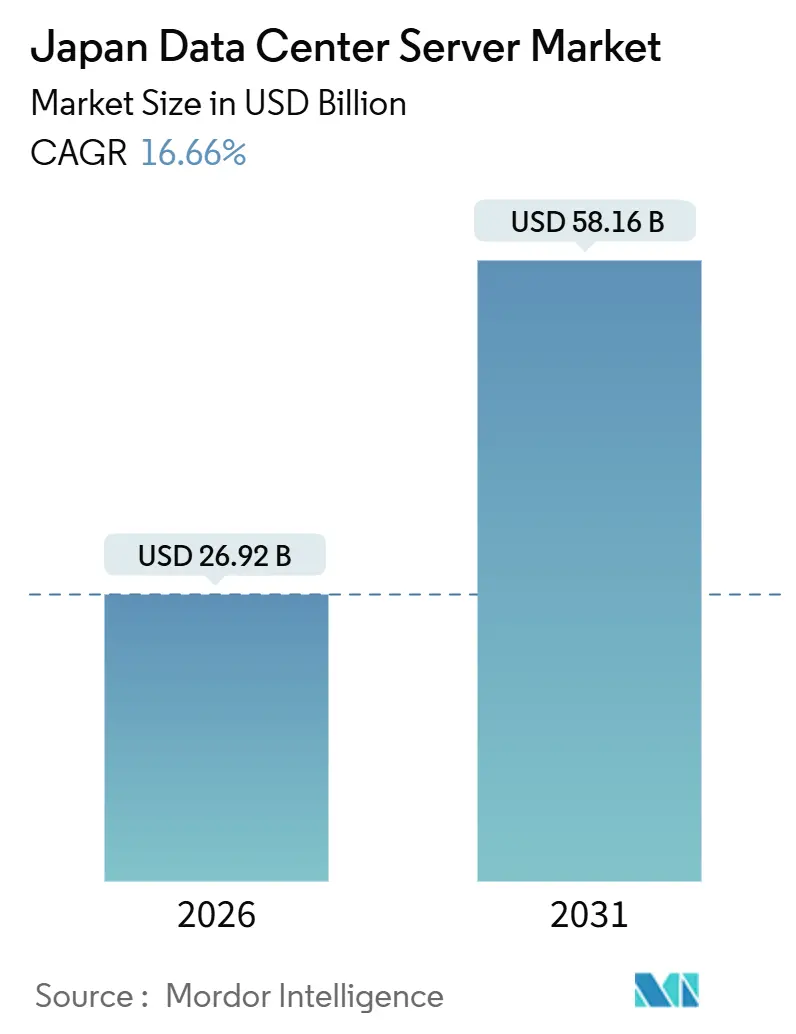
The Japan data center server market size stood at USD 26.92 billion in 2026 and is forecast to reach USD 58.16 billion by 2031, expanding at a 16.66% CAGR. Robust capital outlays by hyperscale cloud providers are accelerating fresh server deployments, while sovereign semiconductor programs shorten component lead times and encourage proprietary silicon adoption. Rapid densification of racks above 100 kilowatts, stricter energy-efficiency mandates, and growing availability of renewable power outside Tokyo and Osaka are reshaping investment priorities. Competitive tension is intensifying as global OEMs introduce liquid-cooled GPU systems to counter domestic incumbents embedding Arm-based processors. Simultaneously, edge-computing use cases in smart-factory automation foster demand for compact micro-blade servers that can fit inside industrial enclosures.
Key Report Takeaways
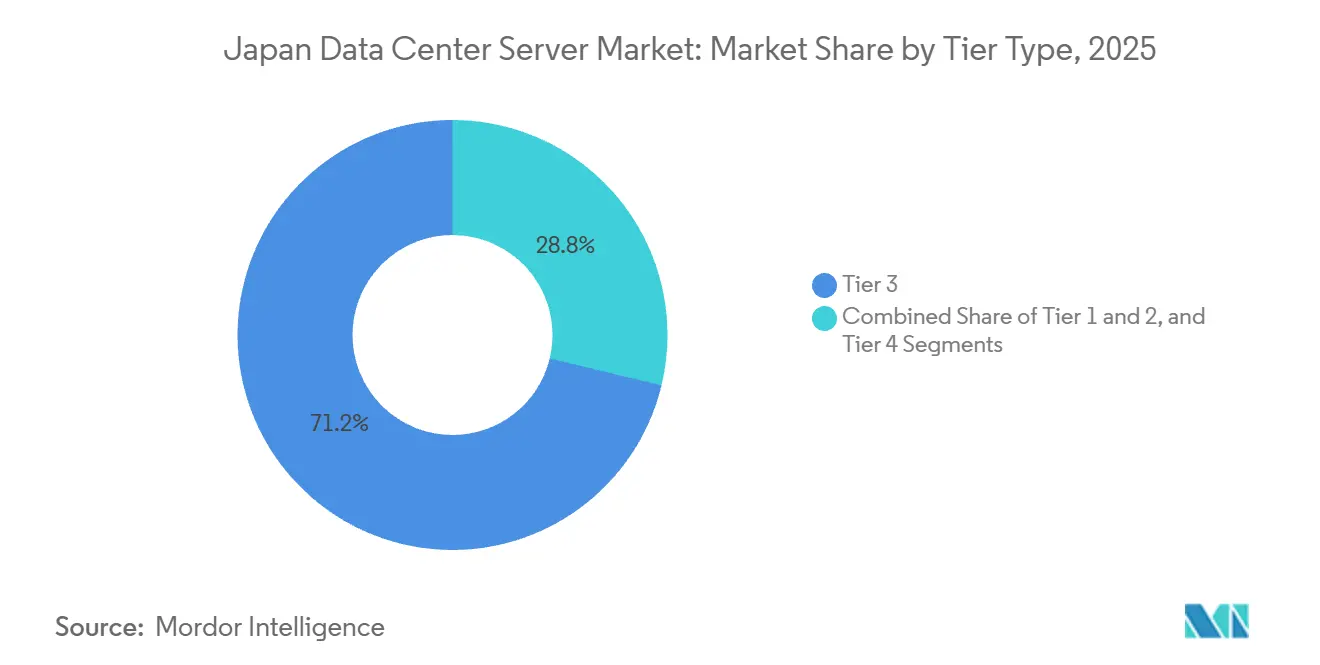
- By tier type, tier 3 facilities held 71.24% of 2025 revenue, while tier 4 deployments are projected to climb at a 17.21% CAGR through 2031.
- By data center size, hyperscale campuses commanded 44.54% of 2025 capacity and will expand at a 17.45% CAGR through 2031.
- By data center type, colocation operators controlled 56.87% of 2025 turnover, yet hyperscalers are expanding direct builds at a 17.63% CAGR through 2031.
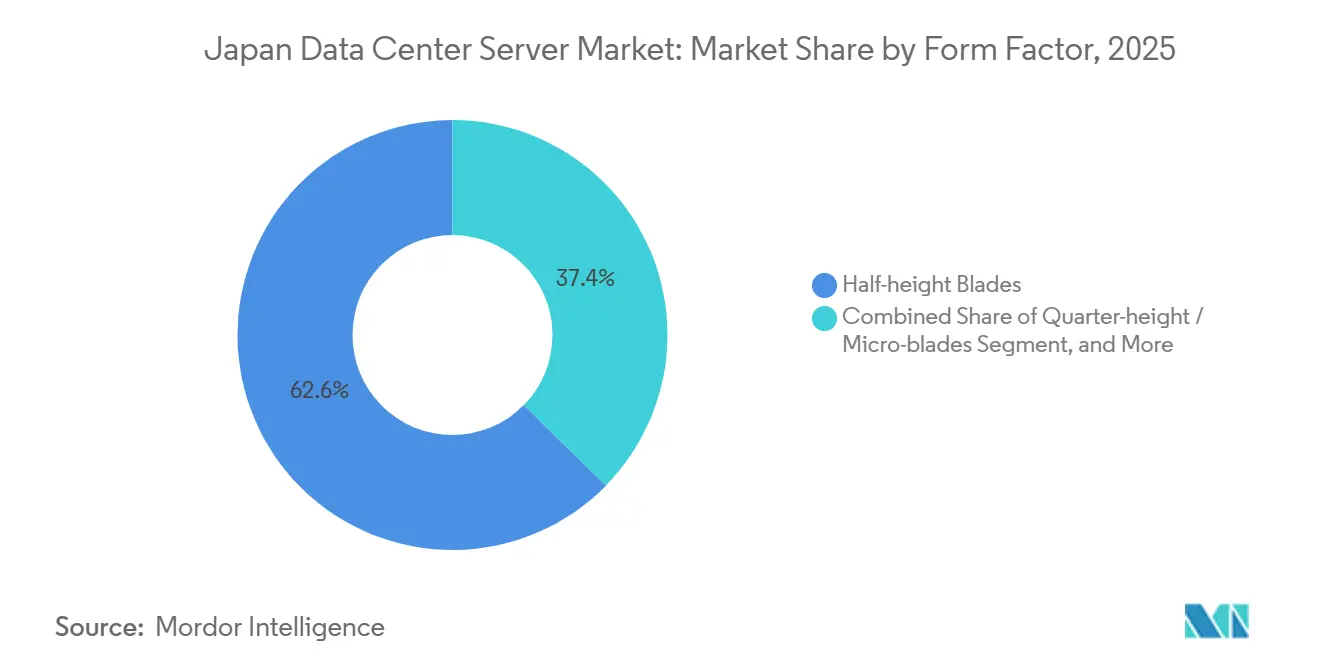
- By form factor, half-height blades captured 62.65% of 2025 shipments; quarter-height and micro-blade servers are rising at a 17.87% CAGR through 2031.
- By application, artificial intelligence and machine learning workloads represented 36.76% of 2025 demand, while virtualization and private cloud segments are growing at a 17.38% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Japan Data Center Server Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of hyperscale facilities by US cloud giants | +4.5% | National, with concentration in Greater Tokyo, Osaka, and emerging Hokkaido clusters | Medium term (2-4 years) |
| Accelerated refresh cycle to AI-optimized GPU servers | +4.2% | National, led by Tokyo and Osaka metro regions | Short term (≤ 2 years) |
| Rising edge-computing nodes for smart-factory rollouts | +2.8% | National, with early gains in manufacturing hubs: Aichi, Kanagawa, Shizuoka | Medium term (2-4 years) |
| Strategic semiconductor self-sufficiency programs | +2.1% | National, anchored in Kumamoto (TSMC) and Hokkaido (Rapidus) | Long term (≥ 4 years) |
| Corporate tax incentives for datacenter energy efficiency | +1.5% | National, with higher uptake in regional prefectures offering supplemental subsidies | Medium term (2-4 years) |
| Mandatory green procurement rules for government IT | +1.2% | National, driven by central government agencies and prefectural administrations | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Expansion Of Hyperscale Facilities By US Cloud Giants
Amazon Web Services, Microsoft Azure, and Oracle pledged more than USD 26 billion of capital between 2024 and 2026, dwarfing the previous decade’s cumulative investment and signaling a pivot toward in-country availability zones for regulated workloads.[1]AWS Press Center, “AWS Announces Plans to Invest USD 15.24 Billion in Japan by 2027,” amazon.com NTT DATA responded with a USD 10 billion build program targeting roughly 1 gigawatt by 2027, while EQUINIX deployed 3,700 cabinets at its TY15 site to satisfy rising interconnection demand. Mitsui Fudosan and Ares Management have likewise financed large campuses in Kanagawa and Tokyo. Faster project cycles favor modular racks that ship pre-integrated, enabling deployment in 90 days rather than 12 months, which benefits vendors with local assembly.
Accelerated Refresh Cycle To AI-Optimized GPU Servers
Japanese operators installed more than 10,000 NVIDIA H200 GPUs during 2025. Notable rollouts include GMO Internet’s 1,000-GPU cluster in May, SAKURA Internet’s 3,072-unit expansion in August, and AIST’s 6,128-GPU ABCI 3.0 supercomputer in January. Generative AI inference pushes rack power well beyond 100 kilowatts, compelling operators to retrofit liquid-cooling. Fujitsu and Super Micro Computer formed an April 2025 pact to embed direct liquid cooling in PRIMERGY servers, aiming for 40% lower energy use.[2]Fujitsu Ltd., “Fujitsu and Super Micro Computer Announce Collaboration on Direct Liquid Cooling,” fujitsu.com The refresh interval is compressing to 2.5 years as firms reap real-time analytics benefits.
Rising Edge-Computing Nodes For Smart-Factory Rollouts
NTT Communications and Toshiba proved a cloud-programmable logic controller in November 2025, cutting deployment cost by 30% against conventional distributed control systems.[3]NTT Communications, “Cloud-Programmable Logic Controller Demonstration,” ntt.com Demographic pressures and a working-age population that fell 0.6% annually through 2025 are driving manufacturers toward automated visual inspection and predictive maintenance. Internet Initiative Japan’s Phase 3 campus incorporates 10-kilowatt edge racks scheduled for 2026 start-up. Compact micro-blades that tolerate tighter thermal envelopes now outpace half-height blades in new edge nodes.
Strategic Semiconductor Self-Sufficiency Programs
TSMC’s first Kumamoto fab went live in December 2024 with 55,000 wafers per month, while a second line for 6-nanometer processes completes in 2027, bringing total spend to USD 20 billion. Rapidus, funded by a USD 33 billion commitment, targets 2-nanometer production in Hokkaido by 2027 to reclaim advanced-node capability. Domestic fabs promise shorter lead times for custom ASICs, letting hyperscalers field proprietary silicon that boosts power efficiency and lowers total cost of ownership.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High land and power costs in metro regions | -2.3% | Greater Tokyo, Osaka, and Nagoya metropolitan areas | Short term (≤ 2 years) |
| Escalating grid-power curtailment risks | -1.8% | National, most acute in Tokyo and Osaka service territories | Medium term (2-4 years) |
| Lengthy environmental approval timelines | -1.1% | National, with stricter enforcement in urban prefectures | Medium term (2-4 years) |
| Talent shortage in advanced server maintenance | -0.9% | National, concentrated in regions with semiconductor and AI infrastructure | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
High Land And Power Costs In Metro Regions
Data-center build costs climbed to USD 13.2 million per megawatt in Greater Tokyo during 2024, 35% above Singapore, fueled by scarce land and premium grid tariffs from TEPCO. Developers respond by densifying existing footprints with liquid-cooled racks and by expanding to Hokkaido and Kyushu, where land is 40% cheaper and renewable penetration exceeds 30%.
Escalating Grid-Power Curtailment Risks
Tokyo Electric Power Company and Kansai Electric Power Company impose connection waits of up to 10 years for projects above 10 megawatts, stalling hundreds of megawatts in the pipeline. SoftBank secured a JPY 30 billion (USD 200 million) subsidy in February 2024 to build a 50-megawatt site in Tomakomai, Hokkaido to tap surplus hydro and wind. Containerized, modular halls that scale with incremental power availability help operators avoid idle white space.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Mission-Critical Uptime Reshapes Infrastructure Mix
Tier 3 assets dominated the Japan data center server market share at 71.24% in 2025, a reflection of cost-sensitive colocation and enterprise deployments. Tier 4 facilities are projected to expand at a 17.21% CAGR as banks and government agencies demand 99.995% uptime, especially after the 2024 Noto Peninsula earthquake. NEXTDC’s TK1 campus launched in 2024 illustrates tenant willingness to pay 25% premium lease rates for higher redundancy.
Vendor strategies now emphasize direct liquid-cooled PRIMERGY and DLC-2 racks that temper the 250-kilowatt densities needed for GPU clusters. The Japan data center server market size for Tier 4 is therefore on track to outpace overall growth. Meanwhile, Tier 1 and Tier 2 rooms continue to decline as enterprises consolidate into regional colocation hubs.


By Data Center Size: Hyperscale Dominance Masks Regional Fragmentation
Hyperscale campuses controlled 44.54% of the Japan data center server market in 2025 and will grow at a 17.45% CAGR, buoyed by AWS and NTT DATA programs exceeding 1 gigawatt. Large 10-50 megawatt sites trail as grid delays impede metro builds. Medium facilities face margin pressure amid cloud migration, while small legacy rooms are being decommissioned.
The Japan data center server market size for hyperscale assets is further supported by long-term sale-leaseback deals such as Keppel DC REIT’s USD 707 million Tokyo DC 3 purchase, ensuring stable cash flows that attract institutional capital. Edge-oriented operators use modular 10-megawatt designs to match tenant ramp-up and grid schedules.
By Data Center Type: Colocation Leadership Faces Hyperscaler Vertical Integration
Colocation providers held 56.87% revenue in 2025; however, hyperscalers are expanding self-build capacity at a 17.63% CAGR, compressing third-party margins. Equinix pre-leased 60% of its 3,700-cabinet TY15 site, underscoring colocation’s interconnection appeal. NTT DATA’s USD 10 billion pipeline reflects a defensive stance to retain enterprise clients.
Conversely, Amazon Web Services and Microsoft favor sovereign-cloud compliance and latency gains through owned campuses. The Japan data center server market share for colocation will therefore erode moderately, although hybrid edge nodes embedded inside hyperscale compounds offer a new growth avenue.
By Form Factor: Density Demands Drive Micro-Blade Adoption
Half-height blades delivered 62.65% of shipments in 2025, yet quarter-height and micro-blade servers are growing at a 17.87% CAGR as factories and 5G sites pursue compact designs. Super Micro Computer’s DLC-2 solution supports 250-kilowatt racks and cuts energy use 40%.
The Japan data center server market size for micro-blades is lifted by Fujitsu’s Arm-based Monaka roadmap and Dell’s PowerEdge XE9712 launch with NVIDIA GB200 compatibility. Full-height blades retreat as GPU-dense rack-scale systems replace legacy chassis.
By Application And Workload: AI Inference Reshapes Compute Priorities
AI and machine learning workloads owned 36.76% of 2025 demand, while virtualization and private cloud functions are advancing at a 17.38% CAGR. GMO Internet, SAKURA Internet, and AIST collectively installed over 10,000 GPUs to support generative applications. The Japan data center server market size for AI inference is therefore poised to remain the fastest growing slice.
High-performance computing persists in academia, exemplified by Tohoku University’s 20-petaflop HPE Cray EX, while storage-centric workloads adopt NVMe-over-Fabrics for 8K video editing. Edge IoT gateways grow rapidly as manufacturers need sub-10-millisecond response times.
Geography Analysis
Greater Tokyo still hosts roughly 55-60% of installed capacity, but build costs of USD 13.2 million per megawatt motivate operators to densify rather than expand greenfield. Osaka benefits from lower land prices, though grid queues of 3-5 years delay large projects. Hokkaido and Kyushu, supported by renewable surpluses and government subsidies up to JPY 30 billion per project, are set to capture 10-15% of new capacity by 2027.
SoftBank’s 50-megawatt Tomakomai facility leverages hydro and wind resources, while EdgeConneX phases a 350-megawatt Osaka platform to grid-upgrade timelines. TSMC’s Kumamoto fab catalyzes a Kyushu ecosystem that shortens server-assembly supply chains. Rapidus’ 2-nanometer project is expected to attract co-located data centers near Chitose by 2027, exploiting Hokkaido’s cool climate to meet the 1.4 PUE ceiling mandated under the Act on Rationalizing Energy Use.
Latency-sensitive workloads like electronic trading remain Tokyo-centric, while AI training and archival storage shift to cooler northern sites. Operators race to lock grid capacity in secondary prefectures before hyperscalers internalize supply.
Regulatory Landscape
Japan’s data center server deployments sit at the intersection of telecom, energy, and building-safety compliance. The Ministry of Internal Affairs and Communications (MIC) plays a central role in digital infrastructure policy, and relevant Telecommunications Business Act obligations can apply where services mediate user communications. Build and operations compliance also ties to construction and electricity rules, including requirements around power reception ownership and bulk electricity supply arrangements, which shape how operators structure campuses and procure power in constrained utility territories.
Policy attention is sharpening around standards that enable higher-density, AI-oriented facilities while maintaining safety and energy objectives. The Regulatory Reform Promotion Council (advisory to the Prime Minister) has called for revisions to building and safety standards related to lithium-ion batteries at data centers, a topic that links back to Fire Service Act practices and can constrain on-site energy storage. In parallel, MIC has continued to promote regional digital infrastructure deployment via subsidy-type programs, reinforcing the government’s stated push to decentralize capacity beyond Tokyo and Osaka and align data center build-outs with coordinated power and digital infrastructure planning.
Competitive Landscape
The Japan data center server market features moderate fragmentation. Global OEMs like Dell Technologies, Hewlett Packard Enterprise, and Lenovo counter local incumbents Fujitsu and NEC by supplying liquid-cooled GPU systems. Fujitsu’s April 2025 pact with Super Micro Computer embeds direct liquid cooling in PRIMERGY racks, priming Arm-based Monaka servers for 2027 launch. HPE’s Cray EX at Tohoku University showcases liquid-cooling expertise, whereas Dell’s XE9712 readies for NVIDIA GB200 adoption.
Hyperscalers increasingly commission white-box gear from Quanta and Wistron, squeezing traditional margins. Hitachi’s October 2025 alliance with OpenAI extends its power-distribution and cooling portfolio into AI hubs. Edge opportunities invite automation vendors such as Siemens to integrate compute-embedded controllers.
Colocation leaders Equinix and NTT DATA deploy hybrid edge nodes within hyperscale campuses to retain enterprise tenants, yet Amazon Web Services and Microsoft continue vertical integration, signaling sustained pressure on third-party yields. Rapid liquid-cooling adoption, modular designs, and Arm CPU roadmaps emerge as key competitive differentiators.
Japan Data Center Server Industry Leaders
Dell Technologies Inc.
Hewlett Packard Enterprise
Cisco Systems Inc.
Lenovo Group Limited
Quanta Computer Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
AI-centric rack densification and power-access bottlenecks are creating near-term whitespace for server platforms that reduce facility friction, including liquid-cooled GPU systems, higher-efficiency designs that fit within energy targets, and modular or containerized approaches that scale with incremental grid allocations. Market pull shows up in the report context via faster GPU-oriented deployments during 2025 and in OEM actions such as Fujitsu and Super Micro Computer collaborating on direct liquid cooling for PRIMERGY servers. That emphasis aligns with a broader shift toward racks exceeding 100 kilowatts and tighter energy-efficiency mandates.
A second opportunity is regionalization of capacity and procurement, supported by specific policy and utility initiatives rather than only metro expansion. MIC programs emphasize local digital infrastructure deployment, and the Digital Infrastructure Development Plan 2030 frames integrated data center and submarine cable development under the Watt-Bit collaboration concept, encouraging coordinated siting with power infrastructure. On the utility side, Shikoku Electric Power has established a Digital Infrastructure Development Promotion Office, supporting a pipeline of non-Tokyo/Osaka locations where server vendors can compete on pre-integrated, fast-deploy systems, edge-capable micro-blades, and power-aware configurations for renewables-linked campuses.
Recent Industry Developments
- June 2026: Dell Technologies modernizes NTT DOCOMO internal IT private cloud using PowerStore, PowerMax, and APEX subscriptions; migration completion targeted for late 2026. The shift toward consumption-based models supports enterprise-scale AI and private cloud deployments in Japan.
- April 2026: Cisco Systems Inc. forms Wide-Area APN and Workload Shift Innovation Promotion Council with J-Power, Hitachi, and others to develop operating models for distributed AI data centers. The collaboration establishes a framework for network-enabled AI data centers and distributed compute resources in Japan.
- February 2026: Cisco Systems Inc. announces Silicon One G300 chip for AI data center switches, with products supporting 1.6 TbE to ship in the second half of 2026. The move strengthens silicon-optimized networking to boost GPU utilization in large-scale AI clusters in the region.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market is the value of servers purchased and deployed for use inside data centers located in Japan, including new installs and planned refresh cycles across enterprise, colocation, and cloud facilities.
Scope exclusions: We exclude consumer PCs, on-premise office servers not used in a data center environment, and data center construction or services revenue that is not tied to server hardware value.
Segmentation Overview
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small Data Center
- Medium Data Center
- Large Data Center
- Hyperscale Data Center
- By Data Center Type
- Colocation Data Center
- Hyperscalers Data Center/CSPs
- Enterprise and Edge Data Center
- By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
- By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the starting structure of the model and confirm the definitions match how data centers and IT hardware are described in public statistics. We reviewed official and public sources such as Japan's Ministry of Internal Affairs and Communications, the Statistics Bureau of Japan, the Ministry of Economy, Trade and Industry, and OECD indicators to frame digital activity and infrastructure buildout.
To translate those signals into server demand, we also used sources such as customs and trade statistics for Japan, energy and electricity datasets (for IT load and facility scaling context), and peer reviewed papers that discuss data center power and cooling constraints. Company filings, investor presentations, and reputable press were used to cross-check timing of capacity adds and procurement cycles. In addition, a paid subscription covering company financials and another covering patent data were used selectively to validate product roadmaps and revenue exposure. This list is not exhaustive, and many other public and paid sources were referred to for data collection, validation, and research clarification.
Primary Interviews and Surveys
Primary work focused on interviews and short surveys with data center operators, IT infrastructure buyers, systems integrators, and server supply chain participants across Japan, followed by targeted re-contacts when a model assumption moved materially. Inputs gathered included typical refresh timing, mix shifts toward high density compute, the extent of accelerated replacement for AI workloads, and practical pricing movement seen in bids and contracts. These inputs helped close gaps left by public sources.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 31% | CXOs: 12% |
| Mid tier: 49% | Functional/Unit leaders: 34% |
| Smaller Players: 20% | Managers: 54% |
Market-Sizing & Forecasting
Sizing starts with a top-down build that reconstructs server spending from Japan data center expansion signals, then links it to realistic refresh and deployment cycles observed in the field. The model uses indicators such as planned and commissioned data center capacity, rack and power density direction, server refresh cadence by facility type, and the mix of general-purpose compute versus accelerated servers. Those inputs then drive unit demand and average selling price ranges.
Results are subsequently checked using selective bottom-up approximations, including sampled ASP times estimated shipment volumes for key form factors and channel checks on procurement timing. This allows totals to be adjusted when a sub-segment appears overstated. Where visibility is weaker, for example for smaller private deployments, we apply penetration assumptions derived from interviews and test sensitivity through scenario analysis. Forecasts were built using scenario analysis anchored on expected capacity additions, AI workload adoption timing, and price normalization assumptions agreed in primary discussions, and then reconciled with macro IT spending direction in a final pass.
Data Validation & Update Cycle
Model outputs are validated through multiple checks, starting with internal consistency tests across units, pricing, and implied refresh rates, followed by comparisons against independent signals such as capacity additions and public investment announcements. When a variance is large, the driver is isolated, assumptions are reworked, and experts are re-contacted to confirm what changed in procurement behavior or supply conditions.
Before sign-off, the work goes through multi-step analyst review, including a separate review of formulas, year alignment, and currency conversion timing so anomalies do not carry through. Reports are refreshed annually, and interim updates are made when material events occur that can shift server demand or pricing. Right before delivery, a fresh analyst pass is completed so clients receive the latest updated view.
麻豆视频's Japan Data Center Server Market Size Versus Other Published Estimates
Published estimates for Japan data center servers often differ because the underlying scope and counting logic are not the same, even if the titles appear similar. Differences typically come from what is treated as a server, whether the figure reflects shipment value or an installed base, and how refresh cycles and accelerated compute are priced over time.
Some published figures blend adjacent IT hardware or broader data center spending into a single total, which can inflate the market number if storage, networking, or facility items are included. In the 麻豆视频 model, only server hardware value deployed in Japan data centers is counted. Refresh timing, form factor mix, and ASP movement are validated through operator and buyer checks before the final total is locked.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 26.92 B (2026) | |
| Trade Journal A | USD 20.40 B (2026) | Often stays conservative by using a narrower definition that undercounts accelerated servers, and it may apply older price baselines that do not reflect recent high density demand. |
| Industry Association B | USD 33.10 B (2026) | Can run higher when adjacent data center hardware categories are bundled into server totals, and when currency timing and refresh assumptions are not consistently reconciled across buyer types. |
The spread in the table is mainly explained by scope alignment and the practical inputs used to price newer deployments. By keeping the demand pool tied to Japan data center server procurement and then stress-testing assumptions with repeatable checks, the result stays traceable to clear variables instead of broad infrastructure spending proxies.


Key Questions Answered in the Report
How large is the Japan data center server market in 2026?
The market reached USD 26.92 billion in 2026 and is on a trajectory to surpass USD 58 billion by 2031.
What is the forecast CAGR for servers deployed in Japanese data centers?
The compound annual growth rate is projected at 16.66% through 2031.
Which server form factor is growing fastest in Japan?
Quarter-height and micro-blade servers are expanding at a 17.87% CAGR as edge deployments proliferate.
Why are Tier 4 data centers becoming more popular in Japan?
Financial institutions and government agencies require higher uptime, driving Tier 4 capacity to grow at 17.21% annually.
How are power constraints shaping data center locations?
Limited grid capacity in Tokyo and Osaka diverts hyperscale builds to Hokkaido and Kyushu, where renewable energy is abundant and land costs are lower.
What cooling technologies are most in demand?
Direct liquid cooling and immersion systems are being adopted rapidly to support racks exceeding 100 kilowatts and to meet efficiency mandates.
Page last updated on:
- Data Center Construction Market Construction across all regions, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities across all regions, split by facility type, component and tier.
- France Hyperscale Data Center Market Hyperscale sites in France, split by facility type, component and tier.
- China Hyperscale Data Center Market Hyperscale sites in China, split by facility type, component and tier.
- Germany Hyperscale Data Center Market Germany hyperscale sites, split by facility type, component and tier.



