
Railway System Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 40.39 Billion |
| Market Size (2031) | USD 52.36 Billion |
| Growth Rate (2026 - 2031) | 5.35 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | Asia Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? Â鶹ÊÓƵ. Reuse requires attribution under CC BY 4.0. | |
Railway System Market Analysis by Â鶹ÊÓƵ
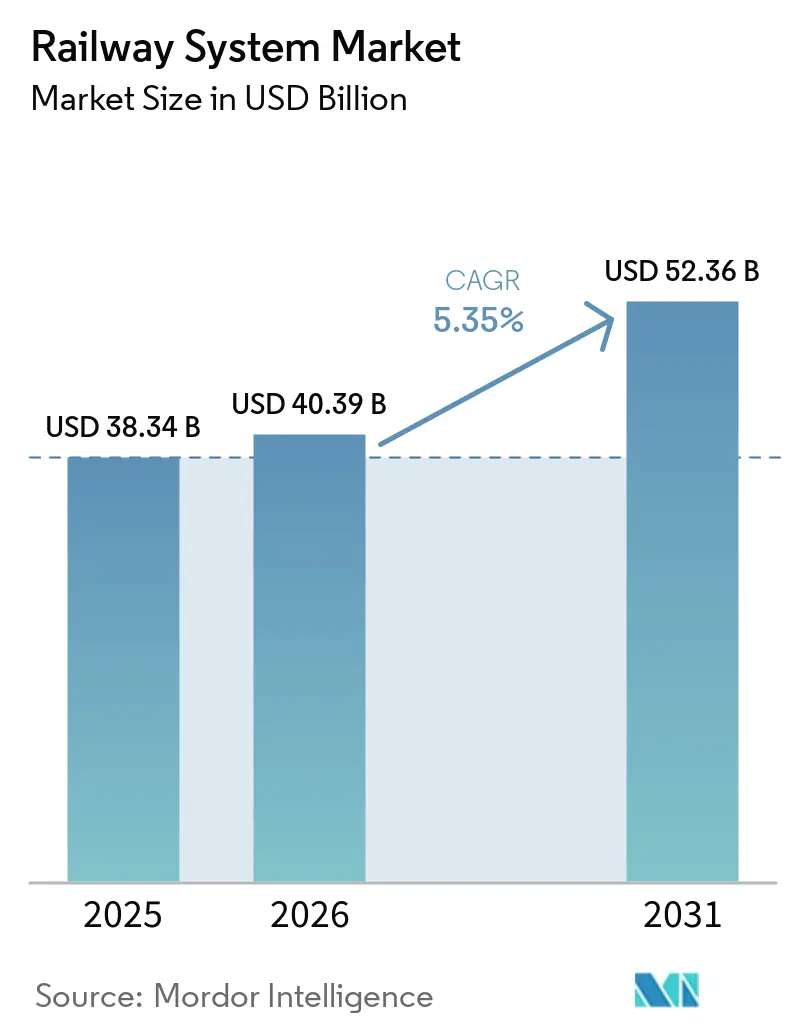
The railway system market size was valued at USD 38.34 billion in 2025, is estimated at USD 40.39 billion in 2026, and is projected to reach USD 52.36 billion by 2031, at a CAGR of 5.35% during the forecast period (2026¨C2031). Decarbonization mandates are reshaping procurement priorities as governments channel stimulus toward electrification and zero-emission rolling stock, while digital train control platforms, particularly European Train Control System Level 2 and Automatic Train Operation, cut operating expenses by reducing headways and enabling predictive maintenance. Operators prioritize smart, energy-efficient rolling stock and software-defined control systems that lower whole-life operating costs and help cities meet net-zero carbon targets. Sovereign infrastructure funds across Asia-Pacific, alongside policy incentives in Europe and North America, continue to redirect transportation budgets from highways to rail corridors.
Key Report Takeaways
- By system type, propulsion systems led with 36.12% of the railway system market share in 2025 while expanding at a 5.88% CAGR through 2031.
- By transit type, conventional rail accounts for 62.15% of the railway system market share in 2025, whereas rapid transit recorded the fastest growth at 6.41% CAGR.
- By application, passenger transportation commanded 69.33% of the railway system market share in 2025 and is forecast to rise at a 6.03% CAGR to 2031.
- By vehicle type, locomotives retained 41.24% of the railway system market share in 2025, while light rail achieved the highest 7.12% CAGR.
- By end use, public operators controlled 73.66% of the railway system market share in 2025, but private operators are projected to post a 7.53% CAGR through 2031.
- By geography, Asia-Pacific captured 49.13% of the railway system market share in 2025 and is expected to grow at a 6.25% CAGR.
Note: Market size and forecast figures in this report are generated using Â鶹ÊÓƵ¡¯s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Railway System Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rail Decarbonization Gets Government Stimulus | +1.2% | Europe, North America, China | Medium term (2-4 years) |
| Digital Control Lowers Rail OPEX | +0.9% | Europe leading, expanding to North America and Asia-Pacific | Medium term (2-4 years) |
| Congestion Drives Shift to Rail | +0.8% | Asia-Pacific core, spill-over to Middle East and Africa and South America | Long term (¡Ý 4 years) |
| Hydrogen and Battery-Electric Trains | +0.7% | Germany, United Kingdom, India, Japan | Long term (¡Ý 4 years) |
| Asset-as-a-Service Business Models | +0.6% | North America and the Europe, emerging in Asia-Pacific | Short term (¡Ü 2 years) |
| Reshoring Semiconductors Boosts Local Suppliers | +0.5% | North America, Europe, allied nations | Medium term (2-4 years) |
| Source: Â鶹ÊÓƵ | |||
Government Stimulus for Rail Decarbonization
Major economies use green stimulus packages to accelerate electrification, signaling upgrades, and next-generation propulsion projects. Germany earmarked EUR 86 billion (~USD 101 billion) through 2030, with 60% set aside for catenary expansion and digital interlocking upgrades, creating long-tail demand for inverter drives, pantographs, and ETCS components [1]¡°Strengthening Rail for Climate Policy,¡± Federal Ministry for Digital and Transport, bmdv.de. Canada¡¯s transit plan funds zero-emission rolling stock procurement, while India has ring-fenced 100% network electrification. The United States Federal Railroad Administration allocated USD 2.04 billion through the Consolidated Rail Infrastructure and Safety Improvements program in fiscal 2026, prioritizing grade separations and catenary extensions that reduce diesel dependency. India's Union Budget 2026 earmarked INR 2.81 lakh crore (approximately USD 33.7 billion) for railway capital expenditure, including 100 new electrification projects and hydrogen-corridor pilots in Rajasthan and Gujarat. These predictable pipelines enable suppliers to raise R&D spending on hydrogen stacks, battery modules, and software-defined train control without balance-sheet stress. Vendors able to certify components under evolving cybersecurity and safety norms secure preferred-bidder status, reinforcing entry barriers for late movers. As diesel bans accelerate, long-term contracts linked to availability guarantees protect operator cash flows and elevate recurring revenue participation in the railway system market.
Digital-Train Control (ETCS/ATO) Lowering OPEX
Operators adopt ETCS Levels 2 and 3 paired with ATO to unlock capacity without laying new track. Hamburg¡¯s S-Bahn achieved 15% energy savings and 20% throughput gains post-deployment, validating the payback model for midsize commuter lines [2]¡°Digital S-Bahn Hamburg Achieves Performance Milestones,¡± Deutsche Bahn Netz, dbnetze.com . Stuttgart shortened headways from 120s to 90s, raising trains per hour. Eliminating 300 legacy signal boxes on the UK East Coast Main Line will cut annual maintenance and improve punctuality benchmarks significantly. Finland became the first Nordic nation to deploy Automatic Train Operation over the European Train Control System on a mainline corridor in late 2025, with Siemens Mobility delivering the signaling package under a €60 million (approximately USD 70.1 million) contract for Hamburg's S-Bahn network. Operating-cost reductions of 12% to 18% make the business case compelling for public operators facing subsidy constraints, yet the 8-to-12-year payback period limits adoption among private concessionaires with shorter contract horizons. Compliance with Technical Specifications for Interoperability under European Union Agency for Railways oversight ensures cross-border compatibility, a critical factor for freight corridors linking Scandinavia to the Mediterranean.
Urban Congestion Pushing Modal Shift to Rail
Congestion costs reaching double-digit percentages of city GDP spur planners to prioritize track-based transit over road widening. Malaysia quantified annual congestion losses at MYR 20 billion (~USD 5 billion) and fast-tracked MRT 3, along with LRT extensions to cut commuter travel times [3]¡°Congestion Impact Assessment,¡± Ministry of Transport Malaysia, mot.gov.my. Berlin¨CMunich¡¯s high-speed corridor reduced the four-hour drive to 3.5 hours by rail and drew a notable share away from aviation within 18 months, underscoring rail¡¯s competitiveness on a 300¨C800 km corridor. Rapid transit segments such as metro and light rail benefit because grade-separated alignments bypass gridlock, offer higher passenger throughput per corridor, and justify land-value-capture financing. Metro elasticity studies in Chinese tier-1 cities reveal a -0.36 coefficient for private-vehicle trips, meaning each 10% increase in metro capacity reduces road congestion by 3.6%. Mumbai Metro Line 3, which commenced full operations in late 2025, eliminates an estimated 155 metric tons of carbon dioxide daily by diverting 1.2 million commuters from personal vehicles. Cities now embed transit-oriented development rules that integrate affordable housing and last-mile micro-mobility hubs, entrenching rail as the backbone of sustainable urban mobility strategies.
Hydrogen and Battery-Electric Multiple Units
Alternative propulsion systems move from demonstration to scaled purchase orders despite infrastructure constraints. Germany¡¯s hydrogen multiple units now deliver significant fleet availability, compared to early trials, after durability upgrades to fuel-cell stacks. India unveiled a 180 km/h hydrogen train for 5,000 km of non-electrified routes by 2030. Stadler¡¯s RS Zero battery unit provides a 200 km range that covers 80% of Central European regional services. Romania's Ministry of Transport awarded Siemens Mobility a RON 1.6 billion contract (approximately USD 350 million) for 12 Mireo Plus H hydrogen trainsets in early 2026, targeting non-electrified branch lines in Transylvania. Hydrogen suits long-regional corridors where catenary is uneconomic, while battery-electric addresses commuter lines able to recharge at terminals. Weight penalties still constrain seat capacity, and hydrogen refueling corridors remain sparse, but long-term carbon-pricing trajectories make these platforms economically viable.
Restraints Impact Analysis of Railway System Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Fiscal Pressure Delays Projects | ¨C0.6% | Global, higher impact in developing markets | Short term (¡Ü 2 years) |
| Volatile Prices Inflate CAPEX | ¨C0.4% | Global, sensitive in price-competitive contracts | Medium term (2-4 years) |
| Right-Of-Way Hurdles In Cities | ¨C0.3% | APAC urban centers, European cities, North American metros | Long term (¡Ý 4 years) |
| Skilled Labor Shortages Persist | ¨C0.2% | North America, Europe, emerging in Asia-Pacific | Medium term (2-4 years) |
| Source: Â鶹ÊÓƵ | |||
Fiscal Pressure Post-COVID Delaying Projects
Public debt levels in advanced economies are projected to remain high, averaging nearly 88% of GDP in 2025. This limits governments' capacity to allocate discretionary spending for large-scale infrastructure projects. In Latin America, several rail investments have been postponed, with countries like Argentina choosing to extend existing freight concessions instead of initiating new long-term tenders. In North America, smaller transit agencies are delaying rolling-stock replacement cycles by 18¨C24 months, opting for cost-effective life-extension programs that extend service life by 5¨C7 years at a significantly lower cost. Additionally, procurement strategies are increasingly phased, with large contracts divided into multiple tranches to better manage budget constraints and cash flows. Victoria, Australia, cut transport spending, delaying the Suburban Rail Loop by 18 months. Singapore deferred a significant amount of MRT work to reorient cash toward public-health safeguards. Such deferrals compress order books for signaling and rolling-stock suppliers and elongate revenue recognition cycles. Although multi-year frameworks remain intact, suppliers hedge with shorter lead-time service contracts to bridge near-term volume volatility.
Volatile Steel and Copper Prices Inflating CAPEX
Steel prices have experienced a significant increase, reflecting substantial growth compared to previous levels, while copper crossed USD 9,200 per ton, inflating budgets for catenary and transformers. Copper spot prices surged to USD 12,500 to USD 13,000 per metric ton in early 2026¡ªa 40% to 50% increase year-on-year¡ªdriven by artificial-intelligence data-center demand that created a 150,000-ton supply deficit. These materials account for up to 30% of track and power-supply project costs, pressuring developers to seek fixed-price bids that transfer risk to contractors. Smaller fabricators lacking hedging instruments face insolvency threats, accelerating industry consolidation. Operators are exploring modular track-form solutions with reduced steel content and are recycling scrap rails more aggressively. Cost-plus contracts now integrate escalation clauses tied to commodity indices, stabilizing cash flows yet capping margin upside.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Railway System Market Segment Analysis
By System Type:
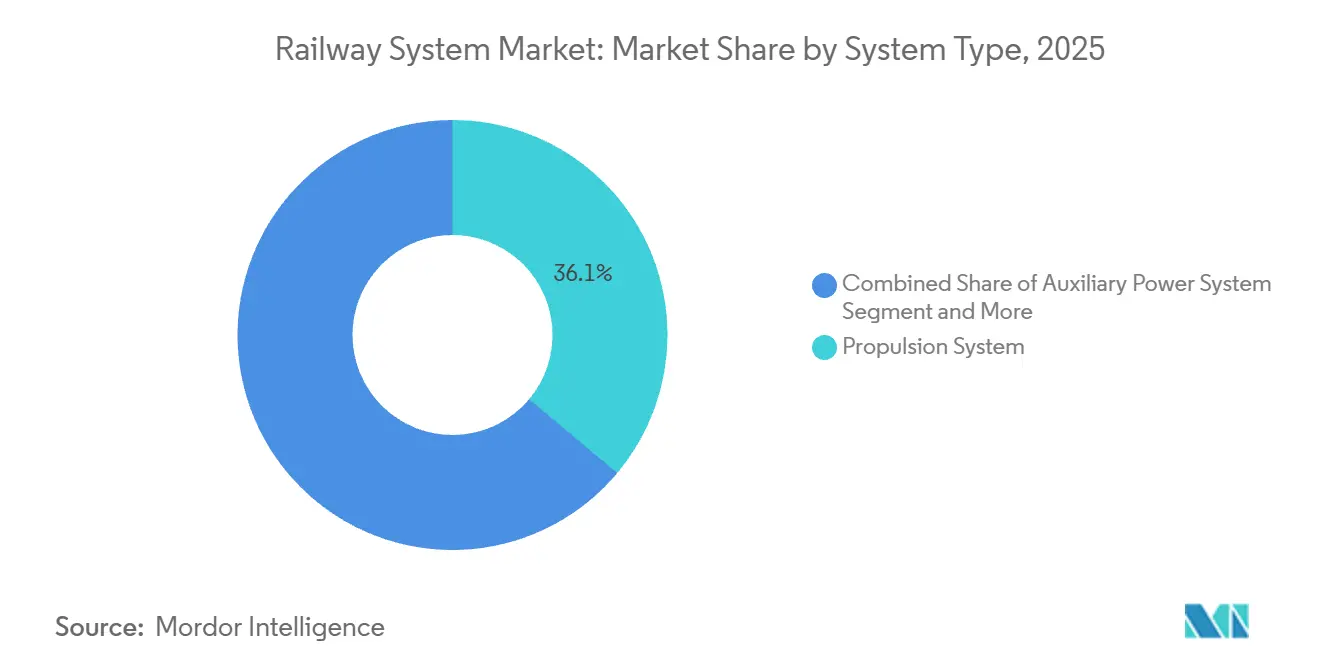
Propulsion Dominance Drives ElectrificationIn 2025, propulsion platforms accounted for 36.12% of the railway system market. They are projected to grow at a 5.88% CAGR through 2031, driven by diesel phase-out mandates and declining costs of batteries and hydrogen fuel cells. Electric traction reduces energy expenses by up to 30% compared to diesel, leading to faster fleet renewals due to favorable paybacks. Modern traction inverters support various power inputs, enabling operators to transition from catenary systems to onboard energy storage without replacing traction motors. Increasing ridership has elevated demand for train information and passenger infotainment systems, particularly for Wi-Fi and journey-time updates. Additionally, HVAC retrofits now include HEPA filtration to comply with post-pandemic ventilation standards.
Auxiliary power modules and safety systems exhibit steady replacement demand while undergoing enhancements through software upgrades and remote monitoring. Propulsion-control software with over-the-air update capabilities is becoming critical, optimizing efficiency and reducing unexpected downtime. Siemens Mobility¡¯s modular Vectron locomotives exemplify this trend, allowing operators to retrofit hydrogen or battery packs on a single chassis, fostering deeper lifecycle engagement. The railway system market increasingly favors suppliers offering integrated solutions that combine hardware, firmware, and analytics.


By Transit Type:
Rapid Transit AccelerationIn 2025, conventional rail represents 62.15% of the railway system market, supported by established freight and intercity passenger services. However, the expansion of urban rapid transit is directing supplier R&D toward innovations such as higher acceleration rates, regenerative braking systems, and communications-based train control, which enhance throughput without requiring additional tracks. Bangkok¡¯s Orange Line monorail, achieving notable on-time performance within six months, highlights the operational benefits of grade-separated corridors. Consequently, the railway system market is focusing on modular vehicle platforms adaptable to metro, monorail, and automated line applications.
Rapid transit, with a 6.41% CAGR, leads all transit formats, driven by urbanization and the need to address congestion. In China and India, metro systems dominate, with cities like Shenzhen and Dongguan increasing corridor ridership through integrated cross-boundary services. Southeast Asian cities are adopting monorails and automated people movers due to their narrow footprints and lower expropriation costs. High-speed rail, while a premium niche, enhances capacity on corridors exceeding 300 km, positioning rail as a competitive alternative to aviation and reducing per-passenger emissions.
By Application:
Passenger Transportation StrengthIn 2025, passenger services accounted for 69.33% of the railway system market size, with a projected growth of 6.03% CAGR. This growth is driven by government initiatives positioning rail as a sustainable alternative to private vehicles and short-haul flights. The return-to-office mandates and unified ticketing systems integrating rail with micro-mobility options have increased ridership on suburban and regional lines. High-speed corridors, with average load factors exceeding 75%, demonstrate strong farebox recovery and benefit from policy support.
Freight rail is expanding steadily through intermodal hubs connecting port operations with e-commerce supply chains. Trucks maintain dominance on routes under 500 km, but driver shortages and carbon pricing are influencing modal preferences for longer distances. Rail access charges tied to dynamic energy pricing are encouraging operators to adopt energy-efficient locomotive software, increasing the use of real-time driver advisory systems. Passenger-focused investments continue to shape technology advancements within the railway system market.
By Vehicle Type:
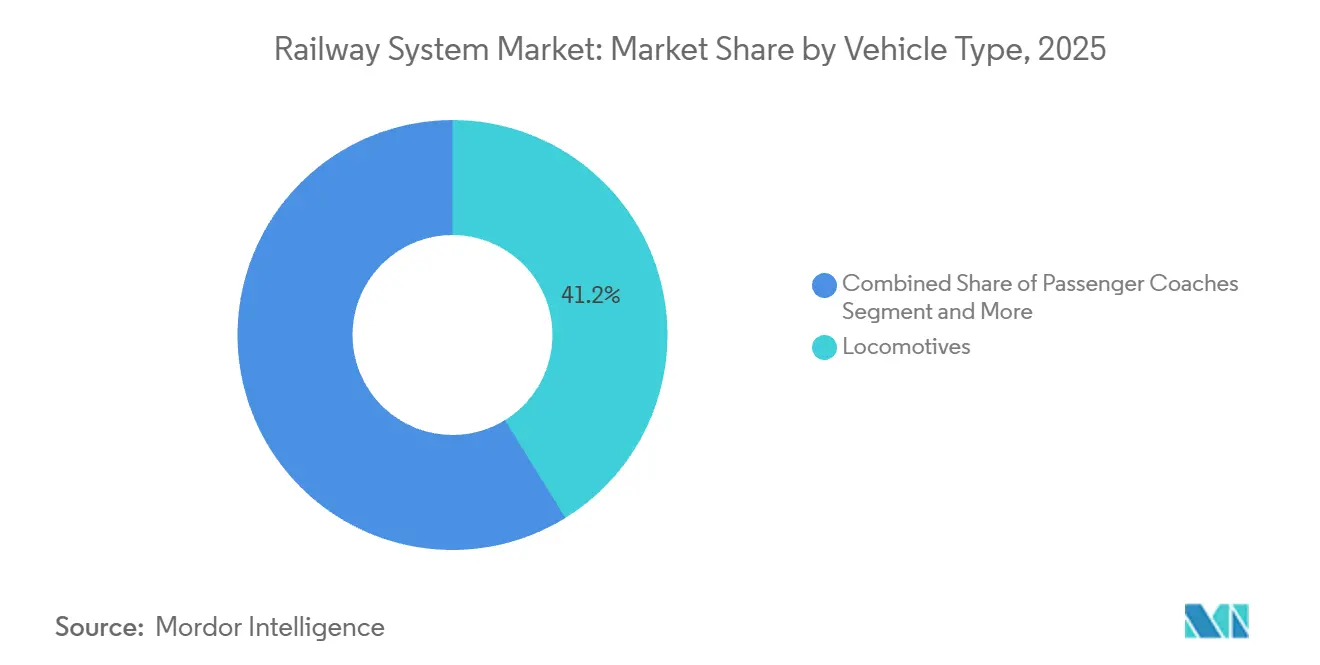
Light Rail MomentumIn 2025, locomotives constitute 41.24% of the railway system market. However, growth remains modest as operators prioritize mid-life refurbishments and digital upgrades to optimize existing fleets. Battery-electric and hydrogen technologies are increasingly adopted for shunting and short-haul freight. In Europe, tram systems are expanding in car-free inner cities, where curbside running lanes utilize existing streetscapes and provide permanent right-of-way advantages over buses. These trends reflect diverse vehicle demand patterns in the railway system market.
Light rail recorded a 7.12% CAGR, driven by municipalities favoring cost-effective, flexible alignments. These alignments are constructed at USD 60¨C80 million per kilometer, significantly lower than the USD 150 million or more required for heavy metro systems. Vehicle standardization and shorter construction schedules accelerate project approvals and reduce surface traffic disruptions. Portland¡¯s MAX network demonstrates success with notable farebox recovery, validating financial viability supported by dense land-use zoning.
By End Use:
Private Sector AccelerationIn 2025, public agencies accounted for 73.66% of the railway system market, reflecting their historic control over core infrastructure and rolling stock. Private operators, supported by European liberalization and public-private partnerships in Asia and the Americas, recorded a 7.53% CAGR. Open access frameworks enable independent passenger services to operate alongside established players, increasing competition in timetables and diversifying revenue streams.
Private freight rail is consolidating through cross-border mergers such as the Canadian Pacific¨CKansas City Southern transaction, expanding continental reach, and attracting volumes from long-haul trucking. Private concessionaires are investing in digital platforms for door-to-door booking, enhancing service differentiation. Safety certification under ISO 45001 is now a tender requirement, favoring well-capitalized players. As asset-as-a-service models evolve, private lessors are expanding leased fleet portfolios and influencing procurement specifications in the railway system market.
Geography Analysis
APAC Railway System Market
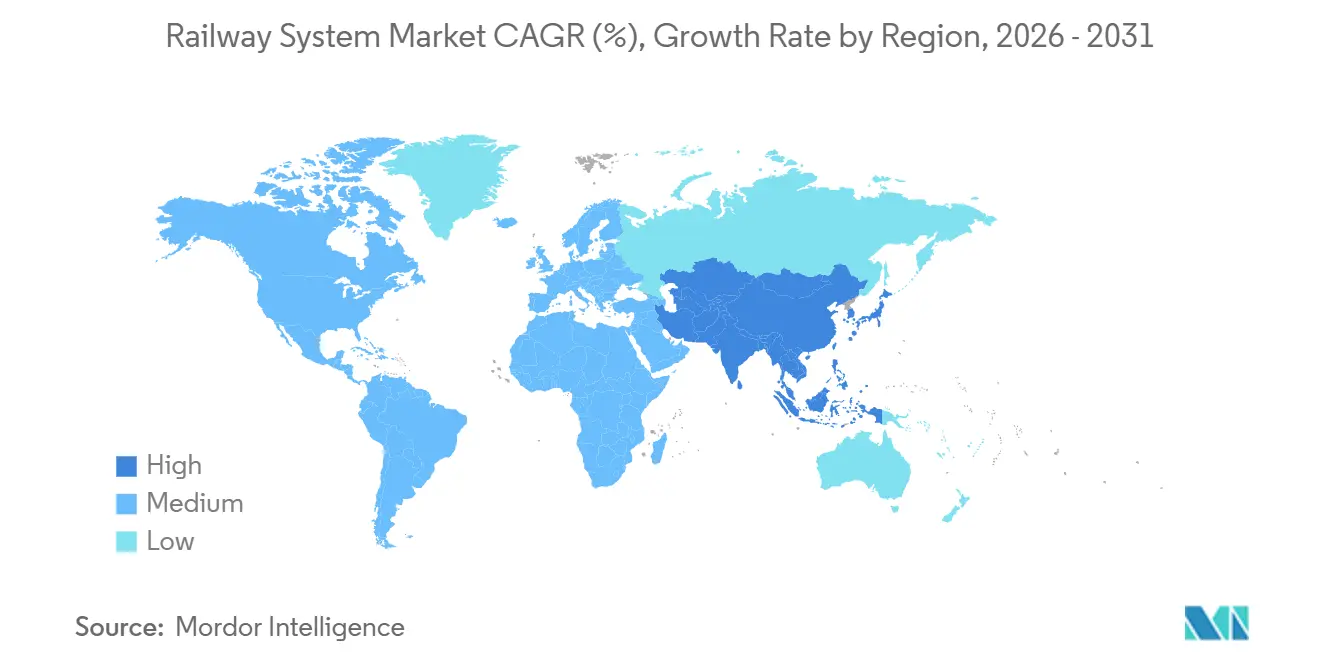
Asia-Pacific held a significant share of the railway system market and is expected to maintain growth with a 6.25% CAGR through 2031. China is expanding its high-speed rail network to 70,000 km by 2035. Urban metro systems added 1,200 km of new lines, while freight corridors improved coal and container throughput. India is modernizing with the Vande Bharat Express and USD 30 billion for electrification, alongside dedicated freight corridors. Southeast Asia highlights projects like Indonesia¡¯s Jakarta¨CBandung line and Malaysia¡¯s East Coast Rail Link, supported by Belt and Road financing. Japan and South Korea focus on exporting railway technology and expertise.
Europe Railway System Market
Europe, with mature infrastructure, emphasizes digital upgrades and decarbonization. The Trans-European Transport Network mandates ETCS across 35,000 km by 2030, driving demand for signaling systems. Germany leads with a EUR 86 billion (~USD 101 billion) investment, while France¡¯s Grand Paris Express adds 200 km of driverless metro lines. The United Kingdom continues with HS2, and Poland and the Czech Republic utilize EU funds to electrify and increase line speeds. Investments in station accessibility and last-mile connectivity support spending on elevators, ticketing, and bike-share systems.
North America Railway System Market
North America prioritizes freight performance and passenger corridor enhancements. The Infrastructure Investment and Jobs Act allocates USD 66 billion for Amtrak expansion and safety upgrades, focusing on the Northeast Corridor and intercity routes like Cleveland-Chicago. The Canadian Pacific¨CKansas City Southern merger creates a network linking Canada, the United States, and Mexico, enhancing supply chain efficiency. Freight carriers invest in train control systems, bridge replacements, and intermodal terminals.

Competitive Landscape
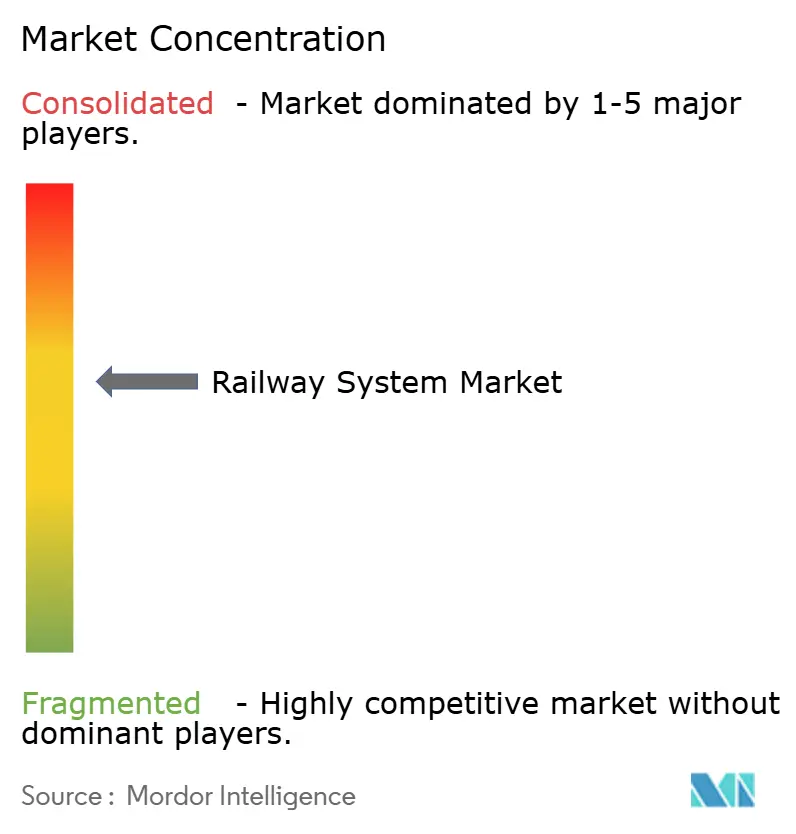
The railway system market is moderately concentrated, with major players combining extensive product offerings and digital services. Companies such as Alstom, Siemens Mobility, and CRRC maintain significant global presence across rolling stock, signaling, and turnkey project delivery. These firms are transitioning from traditional equipment sales to subscription-based models, focusing on condition monitoring, onboard data analytics, and integrated mobility-as-a-service platforms. Notable acquisitions include Hitachi Rail¡¯s EUR 1.66 billion (USD 1.94 billion) purchase of Thales Ground Transportation Systems, enhancing its signaling and cybersecurity capabilities, and Wabtec¡¯s USD 960 million acquisition of Dellner Hitachi, expanding its coupler and suspension product range.
Market strategies emphasize cross-domain systems integration over standalone component performance. Operators prioritize vendors that deliver reliability, punctuality, and energy efficiency under long-term service contracts. Suppliers are investing in cloud-native software platforms, edge computing gateways, and cybersecurity certifications such as ISO 27001 to meet tender requirements. Emerging players include AI-driven predictive maintenance firms and startups developing hydrogen refueling infrastructure in collaboration with energy companies.
Supply chain resilience is a key competitive advantage. Companies are entering long-term agreements with domestic semiconductor manufacturers and establishing regional assembly facilities to reduce delivery times. Rising costs of materials like steel and copper have led to advanced procurement strategies and materials-light design innovations. The shortage of skilled labor in advanced signaling has prompted collaborations with universities and coding boot camps to expand the talent pool. These measures enhance market positioning and create barriers to entry for new competitors in the railway system market.
Railway System Industry Leaders
CRRC Corporation Limited
Alstom SA
Siemens Mobility
Hitachi Rail
Stadler Rail AG
- *Disclaimer: Major Players sorted in no particular order
Railway System Market Companies Covered in this Report
- CRRC Corporation Limited
- Alstom SA
- Siemens Mobility
- Hitachi Rail
- Wabtec Corporation
- Stadler Rail AG
- Kawasaki Heavy Industries
- Construcciones y Auxiliar de Ferrocarriles (CAF)
- Mitsubishi Electric Corporation
- ABB Ltd.
- Hyundai Rotem
- Bharat Heavy Electricals Ltd.
- Talgo S.A.
- Nippon Sharyo, Ltd
- Voith Group
- Knorr-Bremse AG
- Bombela Consortium

Recent Industry Developments in Railway System Market
- March 2026: Alstom secured a €915 million (approximately USD 1.05 billion) contract in March 2026 to deliver Belgrade¡¯s first metro line, including 32 Metropolis trainsets along with signaling and full turnkey system integration for Serbia¡¯s capital.
- September 2025: Concord Control Systems unveiled India¡¯s first fully indigenous zero-emission propulsion package, aligning with the nation¡¯s 2030 net-zero rail target.
- July 2025: DB Cargo retrofitted a locomotive with Automatic Train Operation and Remote Train Operation features, enabling autonomous long-distance freight runs.


Global Railway System Market Report Scope
The scope of the report includes system type, transit type, application, vehicle type, end use, and geography. By system type, the market is segmented into propulsion systems, auxiliary power systems, HVAC systems, onboard vehicle control, train information systems, and train safety systems. By transit type, the market is segmented into conventional rail and rapid transit, with rapid transit further segmented into metro, monorail, and high-speed rail. By application, the market is segmented into passenger transportation and freight transportation. By vehicle type, the market is segmented into locomotives, passenger coaches, freight wagons, light rails, and trams. By end use, the market is segmented into the public sector (government railways) and private operators. By geography, the market is segmented into North America, South America, Europe, Asia-Pacific, and the Middle East and Africa.
| Propulsion System |
| Auxiliary Power System |
| HVAC System |
| Onboard Vehicle Control |
| Train Information System |
| Train Safety System |
| Conventional Rail | |
| Rapid Transit | Metro |
| Monorail | |
| High-Speed Rail |
| Passenger Transportation |
| Freight Transportation |
| Locomotives |
| Passenger Coaches |
| Freight Wagons |
| Light Rails |
| Trams |
| Public Sector (Government Railways) |
| Private Operators |
| North America | United States |
| Canada | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| Spain | |
| Italy | |
| France | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | India |
| China | |
| Japan | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East and Africa | United Arab Emirates |
| Saudi Arabia | |
| Turkey | |
| Egypt | |
| South Africa | |
| Rest of Middle East and Africa |
| By System Type | Propulsion System | |
| Auxiliary Power System | ||
| HVAC System | ||
| Onboard Vehicle Control | ||
| Train Information System | ||
| Train Safety System | ||
| By Transit Type | Conventional Rail | |
| Rapid Transit | Metro | |
| Monorail | ||
| High-Speed Rail | ||
| By Application | Passenger Transportation | |
| Freight Transportation | ||
| By Vehicle Type | Locomotives | |
| Passenger Coaches | ||
| Freight Wagons | ||
| Light Rails | ||
| Trams | ||
| By End Use | Public Sector (Government Railways) | |
| Private Operators | ||
| By Geography | North America | United States |
| Canada | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| Spain | ||
| Italy | ||
| France | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | India | |
| China | ||
| Japan | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | United Arab Emirates | |
| Saudi Arabia | ||
| Turkey | ||
| Egypt | ||
| South Africa | ||
| Rest of Middle East and Africa | ||


Key Questions Answered in the Report
What is the projected revenue for global railway systems by 2031?
Revenue is expected to reach USD 52.36 billion by 2031, reflecting consistent 5.35% CAGR growth.
Which region leads current and future railway investment?
Asia-Pacific holds 49.13% of 2025 and will advance at a 6.25% CAGR, driven by high-speed expansion in China and metro build-outs across Southeast Asia.
Which system segment delivers the strongest growth?
Propulsion platforms record a 5.88% CAGR because operators replace diesel fleets with hydrogen and battery-electric units.
How are asset-as-a-service models changing procurement?
Leasing bundles shift large upfront costs into predictable OPEX, expanding private-operator participation and generating annuity-style revenue for suppliers.
Page last updated on:



