
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.21 Billion |
| Market Size (2026) | USD 0.22 Billion |
| Market Size (2031) | USD 0.24 Billion |
| Growth Rate (2026 - 2031) | 2.17 % |
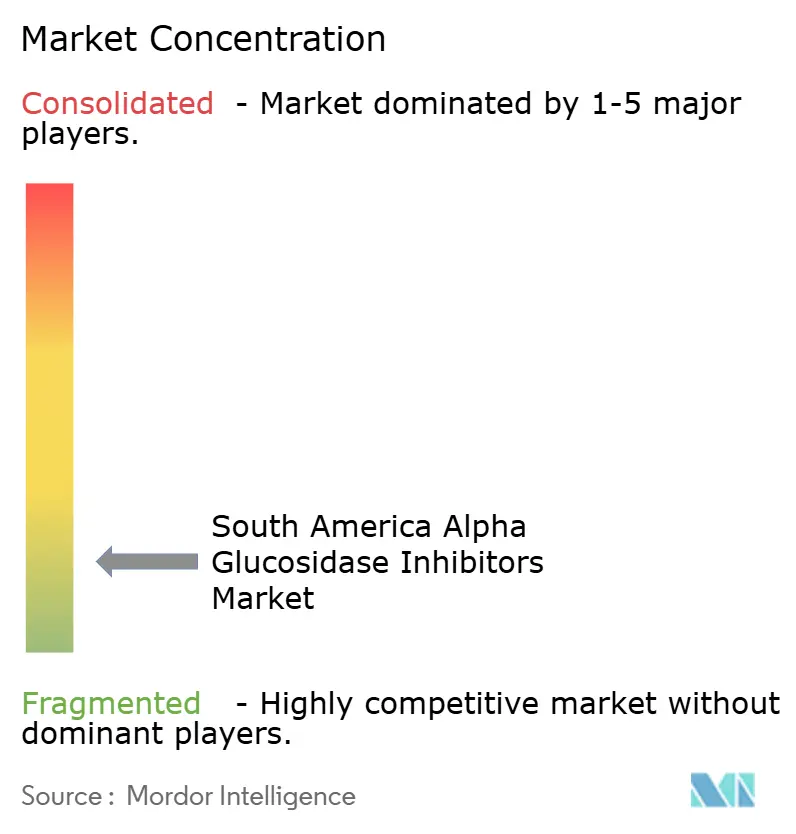
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
South America Alpha Glucosidase Inhibitors Market Analysis by 麻豆视频
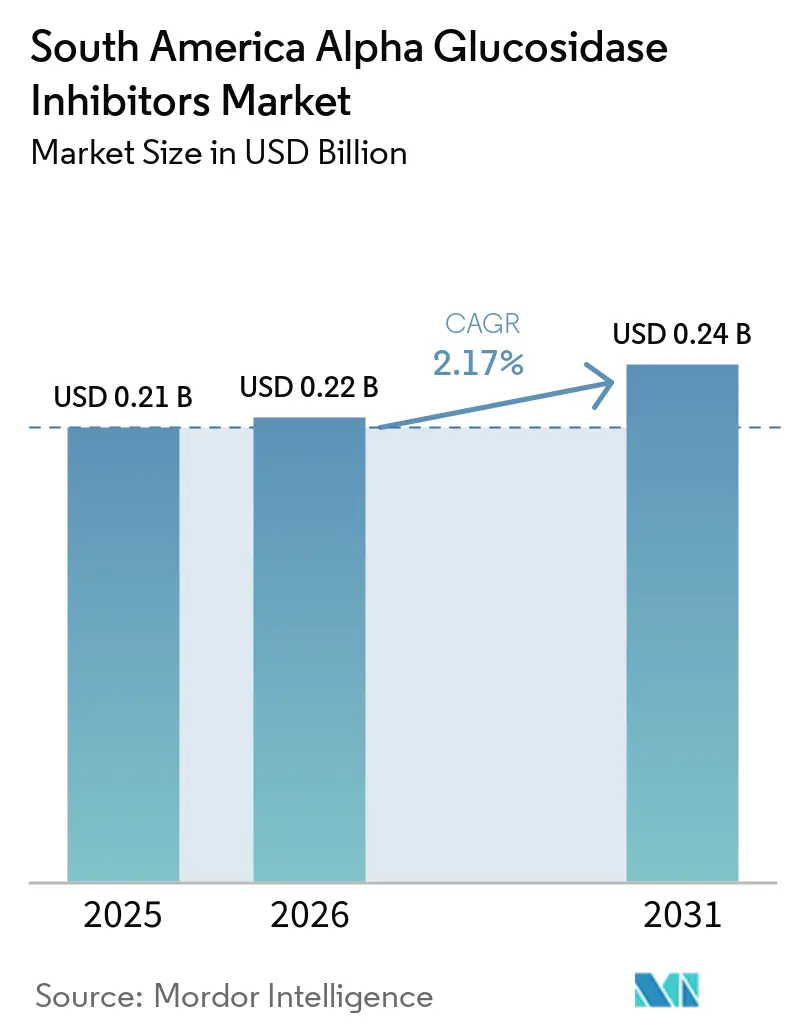
The South America Alpha Glucosidase Inhibitors Market size was valued at USD 0.21 billion in 2025 and is estimated to grow from USD 0.22 billion in 2026 to reach USD 0.24 billion by 2031, at a CAGR of 2.17% during the forecast period (2026-2031).
The category served a durable yet price-sensitive segment of oral diabetes care amid intensifying therapeutic competition. The International Diabetes Federation estimated that 35.4 million adults aged 20–79 lived with diabetes in South and Central America in 2024, with 30.4% of cases undiagnosed. This diagnosis gap supported demand for oral treatments as more patients entered care. Generic availability, private pharmacy access, and postprandial glucose management needs supported the drug class, while lower-cost alternatives in newer therapy classes influenced prescribing decisions in Brazil and other major countries.
Key Report Takeaways
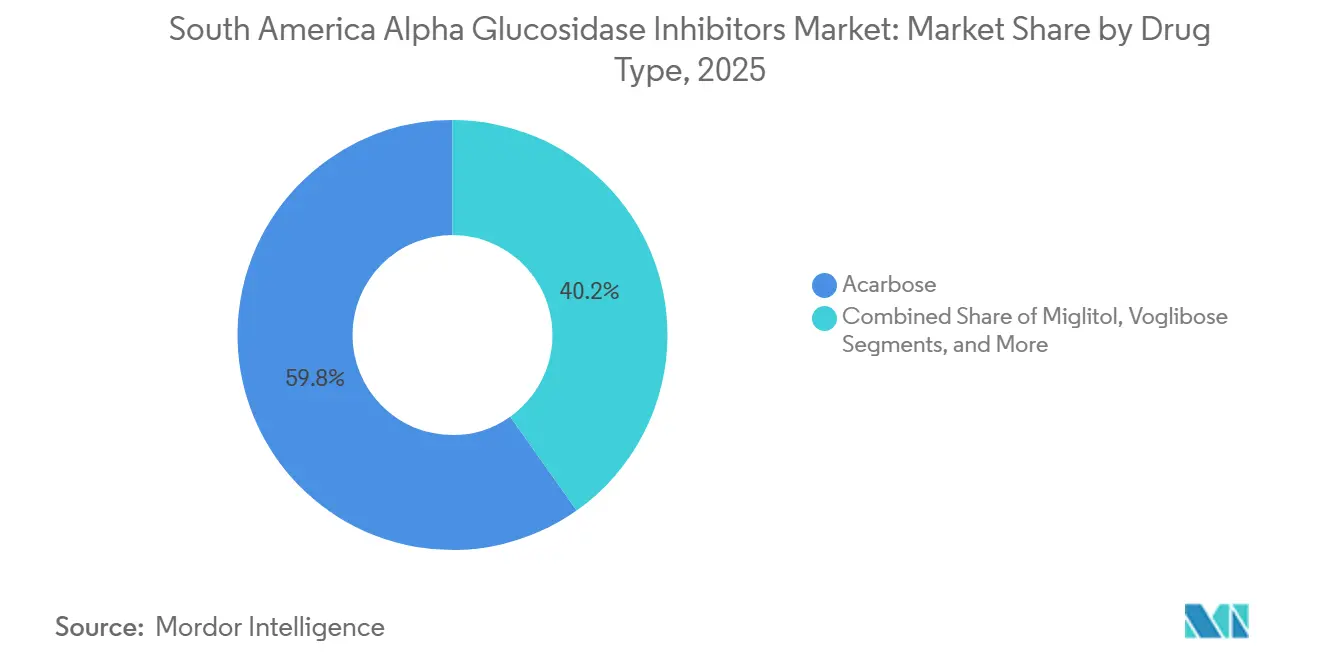
- By drug type, acarbose held 59.80% of the South America alpha glucosidase inhibitors market share in 2025, while miglitol is projected to grow at a 6.89% CAGR through 2031.
- By indication, type-2 diabetes accounted for 53.56% of the South America alpha glucosidase inhibitors market size in 2025 and is projected to advance at a 6.22% CAGR through 2031.
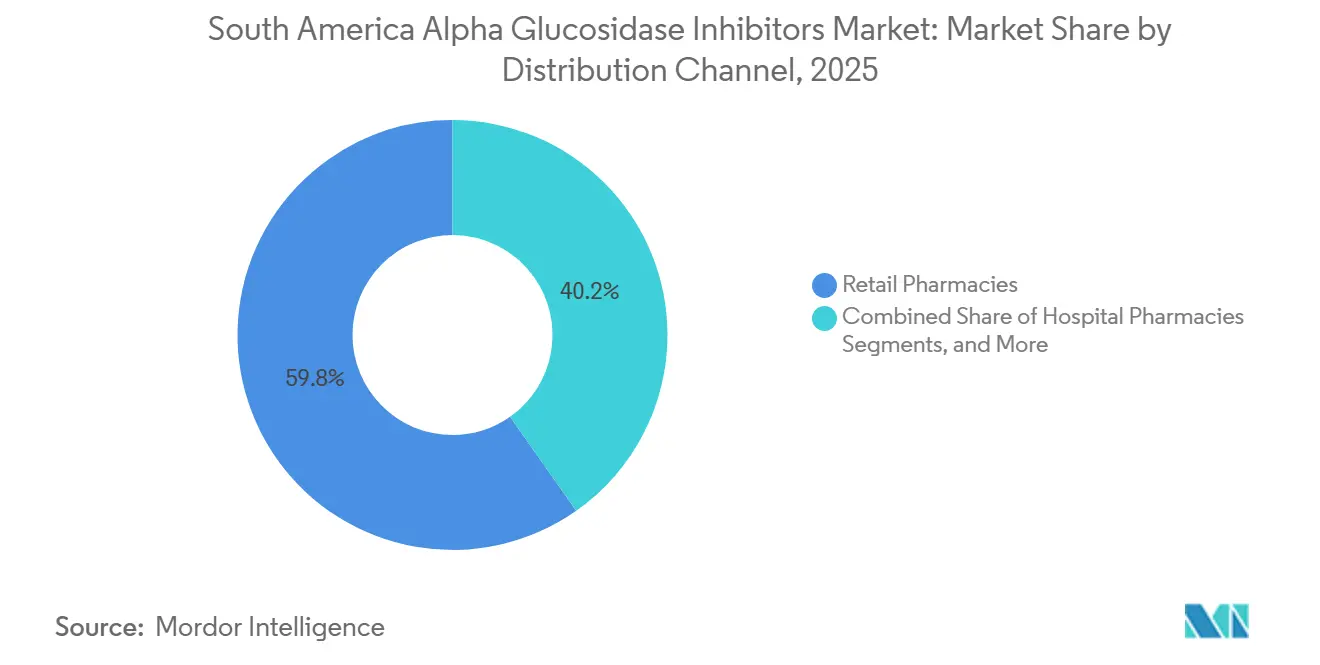
- By distribution channel, retail pharmacies captured 59.76% of the South America alpha-glucosidase inhibitors market share in 2025, while online pharmacies are projected to expand at a 5.72% CAGR through 2031.
- By geography, Brazil held 45.87% of the regional value in 2025, while Argentina is projected to grow at a 5.45% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of South America Alpha Glucosidase Inhibitors Market*
| DRIVER | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Rising type-2 diabetes burden | +0.60% | Brazil, Argentina, Colombia | Long term (≥ 4 years) |
| Increasing use of oral antidiabetic therapy | +0.50% | Brazil, Argentina, Colombia | Medium term (2-4 years) |
| Demand for low-cost generic treatment | +0.45% | All South America, strongest in Brazil and Peru | Medium term (2-4 years) |
| Expansion of private diabetes-care networks | +0.30% | Brazil, Argentina, Colombia | Medium term (2-4 years) |
| Limited public formulary access for alpha glucosidase inhibitors | +0.25% | Brazil, Chile, Argentina | Short term (≤ 2 years) |
| Reliance on legacy brands and generic substitution | +0.20% | Brazil and Rest of South America | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Rising Type-2 Diabetes Burden
Type 2 diabetes provides a broad patient base for the South America alpha-glucosidase inhibitors market. The International Diabetes Federation estimated that 35.4 million adults in South and Central America lived with diabetes in 2024, generating USD 81 billion in diabetes-related healthcare expenditure.[1]International Diabetes Federation, “South and Central America Region,” IDF Diabetes Atlas, diabetesatlas.org It also reported that 30.4% of people with diabetes, or more than 10.7 million individuals, were undiagnosed. Colombia had 3.0 million adults with diabetes in 2024, with 16.2% of cases undiagnosed. The regional diabetes population is projected to reach 52 million by 2050, supporting demand for postprandial glucose-control therapies.[2]International Diabetes Federation, “Diabetes Data in Colombia,” IDF Diabetes Atlas, diabetesatlas.org
Oral Therapy Access and Lower-Cost Generic Treatment
Oral medications remain important in Type 2 diabetes management, as injectable treatments can be unaffordable for patients without private coverage. Clinical guidelines across Latin America position established oral therapies as core treatments, while newer drugs primarily target patients with cardiovascular or kidney risks. Alpha-glucosidase inhibitors retain a role when patients cannot tolerate metformin or require postprandial glucose control. Generic acarbose and miglitol improve affordability, while Brazil’s pricing framework requires generics to be priced at least 35% below reference products. However, increasing generic competition may pressure unit prices.
Expansion of Private Diabetes-Care Networks
Private diabetes care networks in Brazil, Argentina, and Colombia expand prescribing channels for oral antidiabetic medications. Specialist practices in Buenos Aires, Bogotá, and S?o Paulo manage chronic disease patients requiring multiple therapies, supporting alpha-glucosidase inhibitors as add-on treatments for postprandial glucose control. Private retail pharmacies remain important where public procurement programs do not routinely supply these products. Brazil’s pharmacy networks and digital pharmacy services support prescription refill access outside the public healthcare system. Consequently, the market remains linked to household purchasing power, private reimbursement, and retail pharmacy coverage.
Public Formulary Gaps and Established Prescribing Patterns
Limited availability in selected public formularies affects patient access to alpha-glucosidase inhibitors. Acarbose and miglitol are not standard medications for Type 2 diabetes management under Brazil’s public essential medicines framework, shifting many prescriptions to private retail outlets. This increases the importance of pharmacy availability and out-of-pocket affordability while reducing exposure to public tender cycles. The established use of acarbose supports continued prescribing among physicians familiar with the reference product and its generic versions. This retail-led distribution model supports demand in areas with active private care while limiting access in regions dependent on public reimbursement.
Restraints Impact Analysis of South America Alpha Glucosidase Inhibitors Market*
| RESTRAINT | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Competition from metformin, SGLT2 inhibitors, GLP-1 receptor agonists, and DPP-4 inhibitors | -0.55% | Brazil, Argentina, Colombia, Chile | Medium term (2-4 years) |
| Gastrointestinal tolerability and treatment discontinuation | -0.35% | All of South America | Short term (≤ 2 years) |
| Exclusion from selected public reimbursement protocols | -0.25% | Brazil, Colombia, Chile | Medium term (2-4 years) |
| Weak demand visibility across fragmented retail and tender channels | -0.20% | Peru and Rest of South America | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Competition from Newer Diabetes Therapies
Competition from metformin, SGLT2 inhibitors, GLP-1 receptor agonists, and DPP-4 inhibitors is a key restraint on the South America alpha-glucosidase inhibitors market. In May 2026, Brazil’s National Health Surveillance Agency registered Eurofarma’s first generic fixed-dose combination of dapagliflozin and metformin hydrochloride, expanding access to lower-cost oral treatment options for type 2 diabetes. Clinical guidelines prioritize SGLT2 inhibitors for patients with cardiovascular disease, heart failure, or diabetic kidney disease, reducing the target patient pool for alpha-glucosidase inhibitors. Competition is strongest in private insurance formularies and urban specialist settings, although the class remains relevant where newer therapies are unsuitable, unavailable, or unaffordable.
Gastrointestinal Tolerability and Uneven Access
Alpha-glucosidase inhibitors can cause flatulence, bloating, and diarrhea due to carbohydrate fermentation in the colon, which may lead to treatment discontinuation and lower refill volumes. These effects create challenges where physician counseling and treatment monitoring are limited. Miglitol’s absorption profile partly mitigates these concerns and supports its faster growth within the drug class. Fragmented retail and tender channels in Peru and smaller countries, along with limited public reimbursement, uneven pharmacy coverage, and inadequate adherence support, constrain market access and supply consistency.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
South America Alpha Glucosidase Inhibitors Market Segment Analysis
By Drug Type:
Acarbose Retains the Largest Position While Miglitol ExpandsAcarbose held 59.80% of the South America alpha-glucosidase inhibitors market in 2025. Its leadership reflects Bayer’s Glucobay presence as a reference product across South American regulatory systems and the availability of generic alternatives. Familiarity among endocrinologists and general practitioners, particularly in Brazil’s interior states and Argentina’s provincial markets, continues to support prescribing. Generic supply from Brazilian and Indian manufacturers improves access for price-sensitive patients, while voglibose and combination products maintain limited roles.
Miglitol is forecast to grow at a 6.89% CAGR from 2026 to 2031, making it the fastest-growing drug type. Its absorption profile supports selected patients with early-stage type 2 diabetes and high post-meal glucose levels, particularly when renal conditions limit metformin use. Prescribers in Brazil and Colombia are becoming more familiar with its use, although careful patient selection remains necessary because glucagon cannot be used to manage associated hypoglycemia. Local generic availability can further support segment growth.


By Indication:
Type-2 Diabetes Provides the Main Demand BaseType 2 diabetes accounted for 53.56% of the South American alpha-glucosidase inhibitors market in 2025 and is forecast to grow at a 6.22% CAGR through 2031. The regional adult diabetes population is projected to reach 52 million by 2050, up from 35.4 million in 2024. Alpha-glucosidase inhibitors are used when post-meal hyperglycemia is prominent, metformin is not tolerated, or avoiding hypoglycemia is important. The class remains a second-line option when newer medicines are contraindicated or unaffordable.
Type 1 diabetes represents a smaller and more stable indication in the South American alpha-glucosidase inhibitors market. Specialist-managed care may use these drugs off-label to reduce post-meal glucose fluctuations in patients on intensive insulin regimens. However, formal guidance does not strongly support routine use, while continuous glucose monitoring and insulin adjustment remain preferred approaches. Gastrointestinal side effects and strict dietary regimens further limit repeat prescriptions.
By Distribution Channel:
Retail Pharmacies Lead While Online Pharmacies Grow FasterRetail pharmacies captured 59.76% of the distribution value in 2025, making them the leading channel in the South American alpha-glucosidase inhibitors market. Their position reflects the limited availability of acarbose and miglitol through public procurement systems across the region. In Brazil, private pharmacies fill prescriptions not covered by the public essential medicines framework. Household income and private insurance reimbursement remain key factors influencing channel performance.
Online pharmacies are forecast to grow at a 5.72% CAGR from 2026 to 2031. Digital refill systems support treatment continuity for patients using chronic oral medicines, while expanding e-commerce adoption in Brazil, Argentina, and Colombia improves access beyond traditional pharmacy locations. Although GLP-1 products have driven initial online diabetes sales, the digital infrastructure also supports oral therapies. The channel is becoming increasingly relevant for scheduled refills and patient support.
Geography Analysis
Brazil and Colombia Alpha Glucosidase Inhibitors Market
Brazil held 45.87% of the regional market value in 2025, supported by its large diabetes population, pharmaceutical manufacturing base, and extensive retail pharmacy network. An estimated 16.6 million people in Brazil lived with diabetes in 2024, representing a national prevalence of 10.6%. The Northeast recorded diabetes prevalence above the national average but had less developed distribution infrastructure than the Southeast, creating opportunities for lower-cost generics through retail and online channels. Colombia contributes through public hospital procurement and private retail distribution, with 3.0 million adults living with diabetes in 2024, according to the International Diabetes Federation.
Argentina Alpha Glucosidase Inhibitors Market
Argentina is forecast to grow at a 5.45% CAGR through 2031, the highest rate among the geographic markets. The country had a diabetes population of 4.3 million and a national prevalence of 14%, among the highest in the region. Its pharmaceutical base in Buenos Aires Province supports generic oral antidiabetic production.
Broader South American Markets
Chile represents a mid-tier opportunity because branded alpha-glucosidase inhibitors retain a stronger presence in private insurance channels. However, SGLT2 inhibitors are increasingly displacing the class in some private formularies. Peru and the Rest of South America, including Ecuador, Bolivia, Paraguay, Uruguay, and Venezuela, rely heavily on imported medicines and public procurement systems that do not prioritize alpha-glucosidase inhibitors. Peru’s private healthcare market in Lima and Arequipa supports modest branded acarbose demand. At the same time, Bolivia, Ecuador, and Paraguay offer early-stage opportunities as screening, primary care access, formulary inclusion, and pharmaceutical distribution improve.
Competitive Landscape
The South America alpha-glucosidase inhibitors market is fragmented, with no single company holding a commanding share. Bayer’s Glucobay remains a key reference product among clinicians familiar with the original acarbose formulation. Indian suppliers, including Sun Pharmaceutical, Glenmark, Torrent, Zydus Lifesciences, and Unichem, compete with Brazilian manufacturers such as Eurofarma, EMS, Hypera, Biolab, and Uni?o Química through pricing, local registration expertise, active pharmaceutical ingredient access, production capabilities, and commercial reach. Competition is driven by price, pharmacy coverage, regulatory standing, and product availability, with supplier performance varying by country, city, and retail network.
Bayer has signaled a move toward innovative products in Latin America, while commercial partnerships have managed its off-patent portfolio in selected countries, creating opportunities for generic suppliers in established acarbose categories. Fixed-dose combinations of acarbose and metformin are emerging as simpler treatment options, although no company has established a dominant regional position. Generic suppliers continue to benefit from acarbose’s established treatment role and patient affordability requirements, while regulatory compliance, reliable supply, and pharmacy access are increasingly important. Manufacturers with broad diabetes portfolios may leverage existing pharmacy relationships but may prioritize faster-growing therapies, allowing smaller suppliers to compete through stock availability and generic value.
Investment in GLP-1 therapies and newer diabetes medicines has increased competitive pressure on alpha-glucosidase inhibitors. In May 2026, ANVISA approved the first synthetic semaglutide pen for diabetes in Brazil, and in July 2026, EMS and BD announced a collaboration to commercially launch EMS’s semaglutide therapy, Ozivy, in Brazil; Eurofarma’s generic dapagliflozin and metformin combination also added a lower-cost oral alternative during 2026. However, acarbose and miglitol retain a role where affordability, postprandial glucose control, and avoidance of hypoglycemia guide treatment selection. Demand will vary by local pharmacy availability, prescribing familiarity, reimbursement rules, and pricing, supporting continued market expansion despite stronger competition from newer therapies.
South America Alpha Glucosidase Inhibitors Industry Leaders
Bayer AG
Pfizer Inc.
Sun Pharmaceutical Industries Limited
Takeda Pharmaceutical Company Limited
Glenmark Pharmaceuticals Limited
- *Disclaimer: Major Players sorted in no particular order
South America Alpha Glucosidase Inhibitors Market Companies Covered in this Report
- Aché Laboratórios Farmacêuticos S.A.
- Bayer
- Biolab Sanus Farmacêutica Ltda.
- EMS S/A
- Eurofarma Laboratórios S.A.
- Glenmark?Pharmaceuticals
- Hypera S.A.
- Laboratório Teuto Brasileiro S.A.
- Laboratorios Bagó S.A.
- Laboratorios Roemmers S.A.
- Merck
- Merck
- Pfizer
- Prati-Donaduzzi & Cia Ltda.
- Siegfried Holding AG
- Sun Pharmaceuticals Industries
- Takeda Pharmaceuticals
- Torrent Pharmaceuticals Limited
- Uni?o Química Farmacêutica Nacional S/A
- Unichem Laboratories Limited
- Zydus Lifesciences Limited

Recent Industry Developments in South America Alpha Glucosidase Inhibitors Market
- July 2026: EMS and BD collaborated to commercially launch EMS’s semaglutide therapy, Ozivy, in Brazil, targeting first-year sales of 1.2 million units.
- May 2026: ANVISA registered Eurofarma’s first generic dapagliflozin and metformin hydrochloride combination, priced at least 35% below Xigduo XR.


South America Alpha Glucosidase Inhibitors Market Report Scope
As per the scope of the report, Alpha-glucosidase inhibitors are a class of oral medications used to treat Type 2 diabetes by slowing down the digestion and absorption of carbohydrates in the small intestine. Instead of modifying insulin production, they target digestive enzymes to flatten blood sugar curves.
The South America alpha-glucosidase inhibitors market is segmented by drug type, indication, distribution channel, and geography. By drug type, the market includes acarbose, miglitol, voglibose, and combination products containing an alpha-glucosidase inhibitor. By indication, the market is segmented into the type 1 diabetes population and the type 2 diabetes population. By distribution channel, the market is segmented into retail pharmacies, hospital pharmacies, and online pharmacies. By geography, the market is analyzed across Brazil, Argentina, Colombia, Chile, Peru, and the Rest of South America. The report offers market sizes and forecasts in terms of value (USD) for the above segments.
By Drug Type
| Acarbose |
| Miglitol |
| Voglibose |
| Combination Products Containing an Alpha Glucosidase Inhibitor |
By Indication
| Type-1 Diabetes Population |
| Type-2 Diabetes Population |
By Distribution Channel
| Retail Pharmacies |
| Hospital Pharmacies |
| Online Pharmacies |
By Geography
| Brazil |
| Argentina |
| Colombia |
| Chile |
| Peru |
| Rest of South America |
| By Drug Type | Acarbose |
| Miglitol | |
| Voglibose | |
| Combination Products Containing an Alpha Glucosidase Inhibitor | |
| By Indication | Type-1 Diabetes Population |
| Type-2 Diabetes Population | |
| By Distribution Channel | Retail Pharmacies |
| Hospital Pharmacies | |
| Online Pharmacies | |
| By Geography | Brazil |
| Argentina | |
| Colombia | |
| Chile | |
| Peru | |
| Rest of South America |


Key Questions Answered in the Report
What is the value of the South America alpha glucosidase inhibitors market in 2026?
The value is USD 0.222 billion in 2026 and is forecast to reach USD 0.247 billion by 2031 at a 2.17% CAGR. The forecast reflects steady demand for established oral diabetes treatments in a price-sensitive regional setting.
Which alpha glucosidase inhibitor drug type leads in South America?
Acarbose led with a 59.80% value share in 2025, supported by established physician familiarity and generic availability. Its use is reinforced by the long-standing recognition of the reference product across many national regulatory systems.
Which drug type is growing fastest through 2031?
Miglitol is forecast to grow at a 6.89% CAGR from 2026 to 2031, supported by its use in selected patients needing post-meal glucose control. Local generic availability and use in selected patients with renal limitations also support its position.
Why do retail pharmacies have the largest distribution role?
Retail pharmacies accounted for 59.76% of the distribution value in 2025 because many prescriptions are filled outside public procurement systems. Their role makes private reimbursement, household income, local stock, and pharmacy important to continued access.
Which country has the largest regional share?
Brazil held 45.87% in 2025, reflecting its diabetes burden, pharmacy network, and pharmaceutical manufacturing base. The country also combines active retail channels with a large population that needs ongoing diabetes care.
Page last updated on:



