
South America Insulin Pens Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.83 Billion |
| Market Size (2026) | USD 0.88 Billion |
| Market Size (2031) | USD 1.15 Billion |
| Growth Rate (2026 - 2031) | 5.51 % |
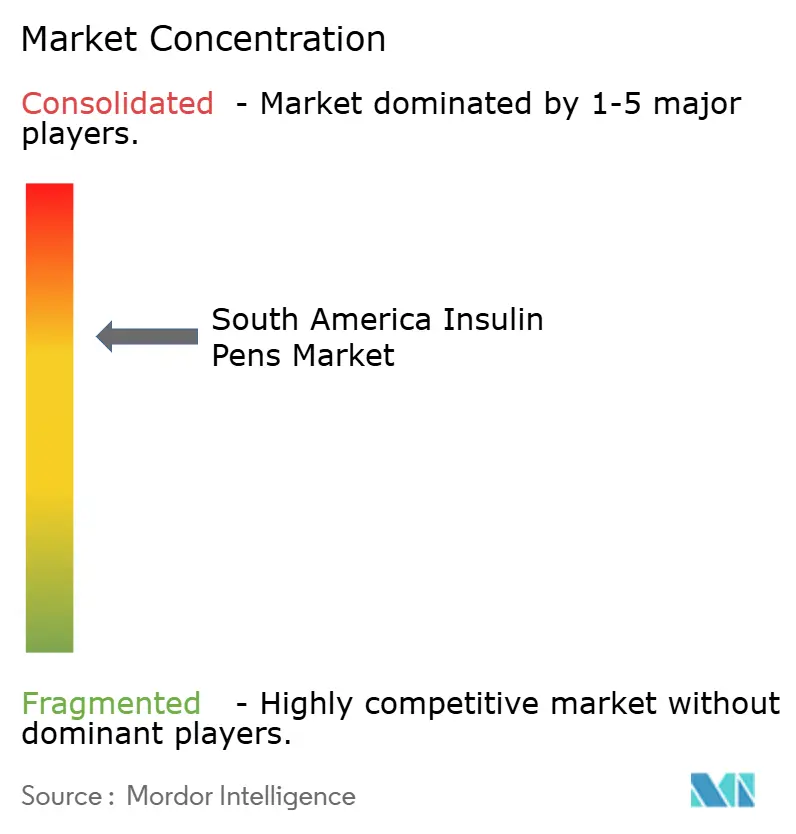
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
South America Insulin Pens Market Analysis by 麻豆视频
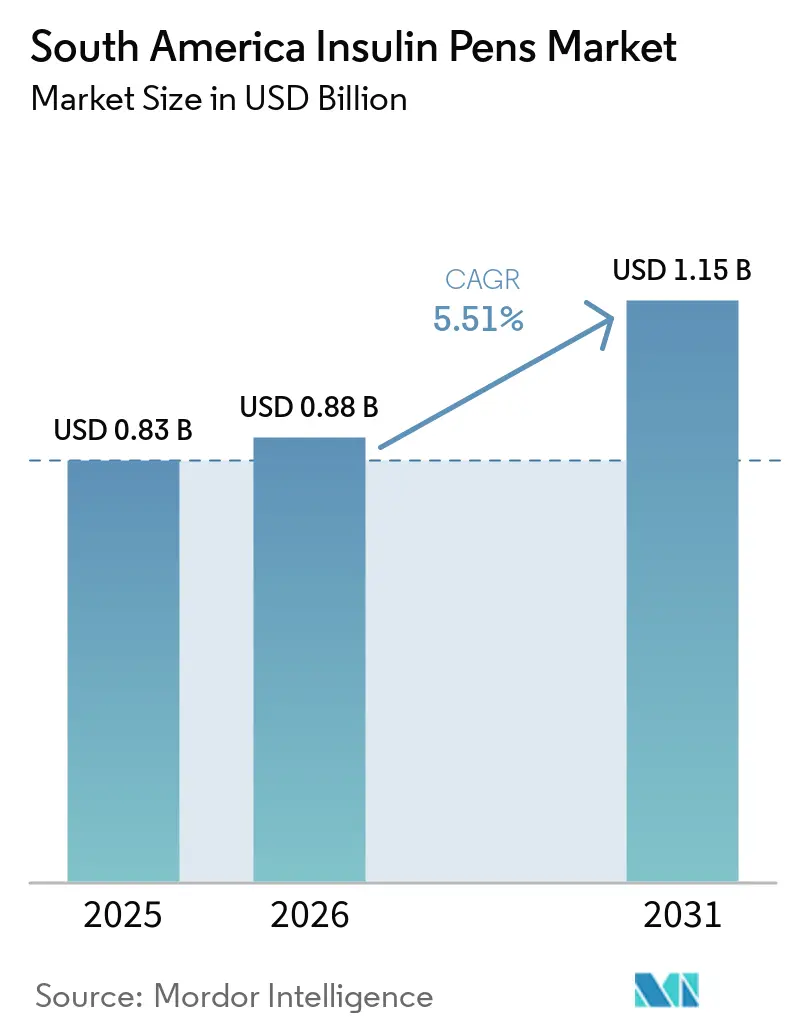
The South America Insulin Pens Market size is expected to grow from USD 0.83 billion in 2025 to USD 0.88 billion in 2026 and is forecast to reach USD 1.15 billion by 2031 at 5.51% CAGR over 2026-2031.
The South America insulin pens market is supported by a growing population that needs insulin treatment, while screening can bring more undiagnosed people into care pathways. The region had 35 million adults with diabetes in 2024, equal to 1 in 10 adults, and 30.4% of those adults were undiagnosed. Regional diabetes-related expenditure reached USD 81 billion in 2024. Public procurement remains important because Brazil and Argentina can provide predictable demand, although tender pricing can limit supplier margins. The transition toward glargine cartridges, reusable devices, and connected adherence tools gives suppliers opportunities that are tied to local reimbursement, training, and distribution capacity.
Key Report Takeaways
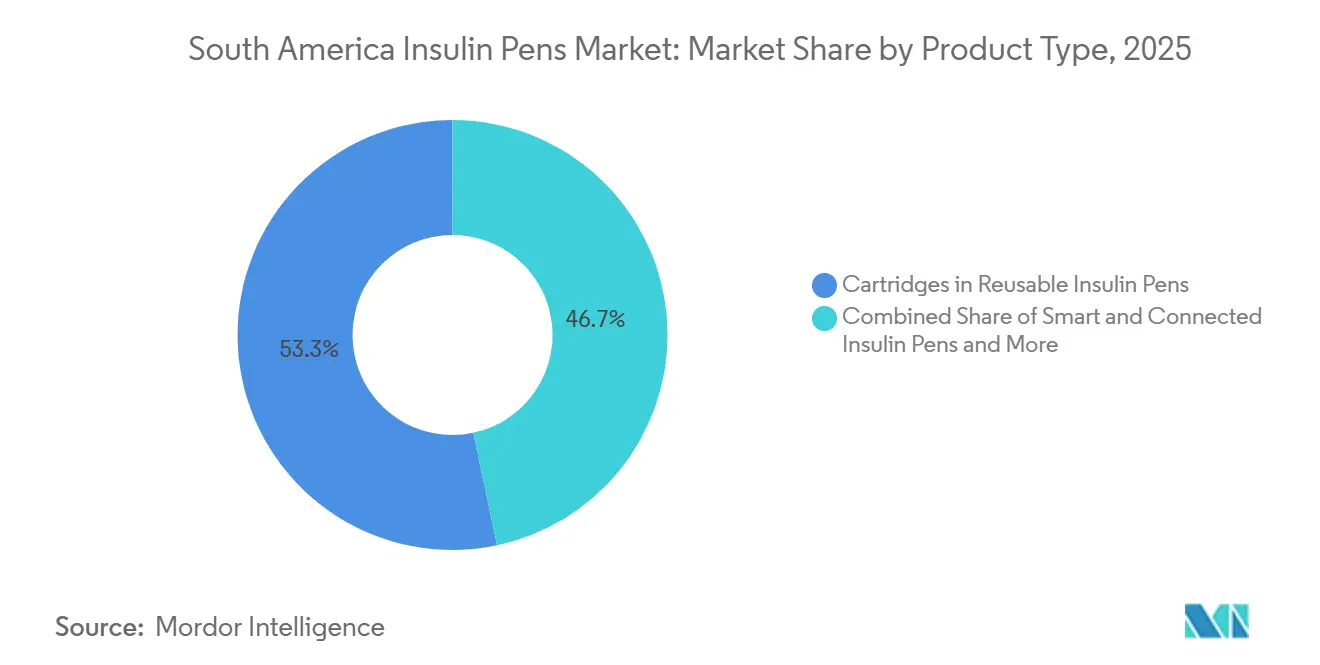
- By product type, cartridges in reusable insulin pens held 53.31% of the South America insulin pens market share in 2025, while smart and connected insulin pens are forecast to grow at a 9.58% CAGR through 2031.
- By diabetes type, type 2 diabetes held 86.24% of the South America insulin pens market share in 2025 and is expected to have a 7.22% CAGR through 2031.
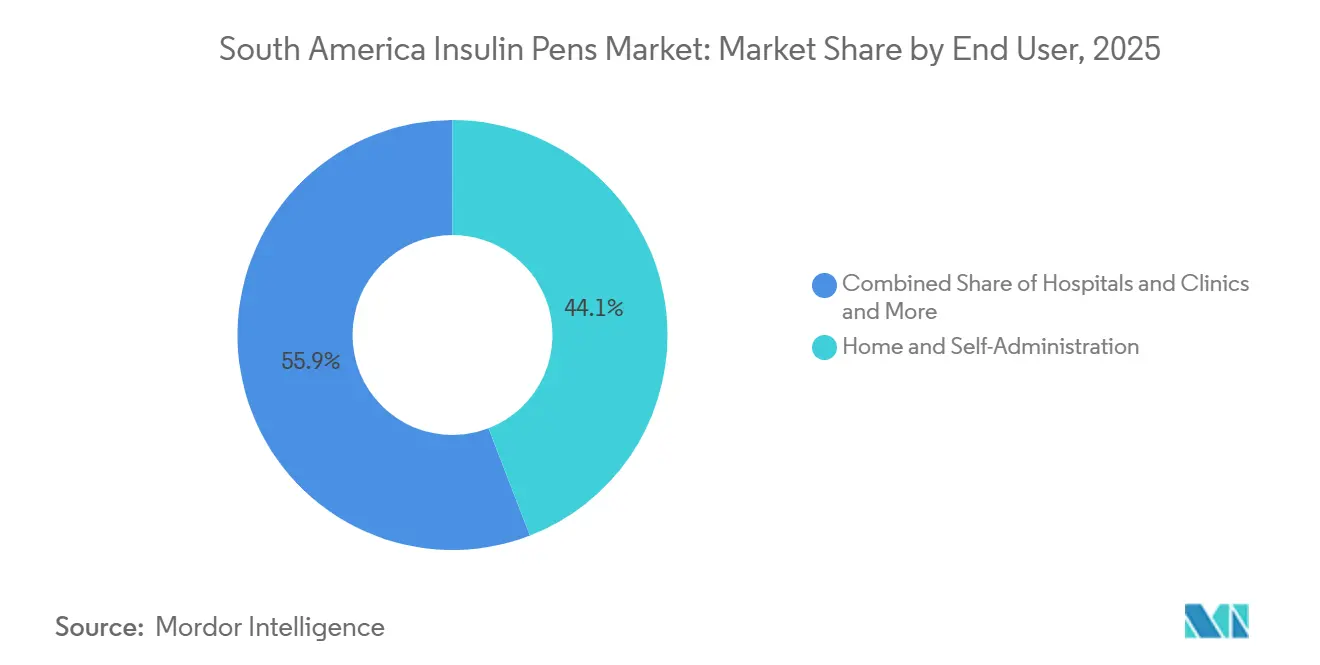
- By end user, home and self-administration held 44.14% of revenue in 2025, while hospitals and clinics are forecast to grow at an 8.82% CAGR through 2031.
- By distribution channel, retail pharmacies held 44.65% of revenue in 2025, while online pharmacies and e-commerce are forecast to grow at a 9.65% CAGR through 2031.
- By country, Brazil held 48.61% share in 2025, and Argentina is forecast to grow at a 9.75% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of South America Insulin Pens Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Diabetes Burden and Insulin-Treated Population | +1.5% | Global, concentrated in Brazil, Argentina, and Colombia | Long term (≥ 4 years) |
| Shift From Syringes to Patient-Friendly Pen Administration | +1.0% | Brazil, Argentina, spillover to Colombia, Peru | Medium term (2-4 years) |
| Expansion of Public Diabetes Programs and Pen Access | +0.9% | Brazil, Argentina, Colombia | Medium term (2-4 years) |
| Growth of Connected Diabetes Management Ecosystems | +0.7% | Urban Brazil, Argentina, Chile, emerging in Colombia | Long term (≥ 4 years) |
| Local Biosimilar Insulin and Cartridge Manufacturing | +0.5% | Brazil, Argentina | Medium term (2-4 years) |
| Digital Refill and Adherence Services in Underserved Areas | +0.3% | Brazil Northeast and North, Peru, Rest of South America | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Rising Diabetes Burden and Insulin-Treated Population
The South America insulin pens market is linked to a diabetes burden that is expected to expand across the region. The adult diabetes population in South and Central America is projected to increase 46% to 52 million by 2050. The 30.4% undiagnosed share recorded in 2024 represented more than 10.7 million people who may enter treatment after screening improves. Brazil's Ministry of Health distributed 59 million units of NPH insulin and 12 million units of regular insulin through SUS in 2024. As glargine cartridges replace some NPH vials, reusable pen use can rise per treated patient without requiring a comparable rise in patient numbers[1]Brazil Ministry of Health, “Ministério da Saúde Inicia Transi??o de Tratamento de Diabetes no SUS Com Amplia??o do Uso de Insulina Mais Moderna,” gov.br..
Shift From Syringes to Patient-Friendly Pen Administration
The South America insulin pens market is also shaped by the move away from syringe-and-vial therapy in major urban care settings. Pen systems can simplify dose administration for patients who receive education through public health units. The American Diabetes Association issued a Grade B recommendation in 2025 to offer connected insulin pens to people using multiple daily injections. This guidance can influence prescribing discussions within diabetes societies in Brazil and Argentina. Cost-sensitive public systems still favor reusable devices because cartridge refills can lower the cost of ongoing administration. Suppliers with cartridge and reusable pen platforms are therefore better placed than suppliers focused only on disposable formats[2]American Diabetes Association, “What Is a Smart Insulin Pen?,” American Diabetes Association, diabetes.org..
Expansion of Public Diabetes Programs and Pen Access
The South America insulin pens market benefits when public programs expand access to insulin and compatible devices. Brazil's Ministry of Health began a glargine transition pilot in February 2026 for more than 50,000 patients in Amapá, Paraná, Paraíba, and the Federal District. The program moves part of SUS treatment from NPH insulin in vials to glargine supplied in cartridges. Each cartridge requires a compatible reusable pen system. Regulatory requirements for cartridge compatibility can determine which platforms qualify for public tenders. Argentina's Law 26.914 requires full reimbursement for pen injectors across public and private payers, which supports demand among covered patients.
Growth of Connected Diabetes Management Ecosystems
The South America insulin pens market is developing a connected-device opportunity in urban private health networks. Connected pens record dose information through Bluetooth or NFC and can send it to apps or electronic health records. Medtronic received FDA 510(k) clearance on January 12, 2026, for its MiniMed Go Smart MDI system, which combines the InPen reusable smart pen with Abbott's Instinct CGM in one app. Data from the earlier system showed time in range increasing from 55.7% to 67.2% when patients responded to missed-dose alerts. A 2025 randomized trial published in Diabetologia found better glycemic control with a connected pen-cap system than with disconnected controls among adults with type 1 diabetes. In South America, add-on caps can be more practical because they keep standard reusable pens compatible with existing formulary cartridges.
Restraints Impact Analysis of South America Insulin Pens Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Uneven Reimbursement and High Out-of-Pocket Spending | -1.2% | Colombia, Peru, Chile, Rest of South America | Medium term (2-4 years) |
| Currency Volatility and Import Dependence | -0.8% | Argentina, Brazil, Colombia | Short term (≤ 2 years) |
| Limited Specialist Training and Device Support | -0.4% | Rural Brazil, Colombia, Peru, Rest of South America | Long term (≥ 4 years) |
| Cold-Chain Exposure Across Remote and Climate-Stressed Routes | -0.3% | Brazil Amazon basin, Andean Peru, remote Colombia | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Uneven Reimbursement and High Out-of-Pocket Spending
The South America insulin pens market has uneven access beyond Brazil and Argentina. Brazil's SUS and Argentina's mandatory coverage framework support access for many patients. Other countries have narrower reimbursement arrangements for pen cartridges and needles. These gaps can make pens less affordable for patients who pay directly. The result is a concentration of revenue in the countries with stronger coverage, while other countries retain unmet treatment demand. Broader insurance coverage and a reliable supply would be necessary for this demand to become active device use.
Currency Volatility and Import Dependence
The South America insulin pens market remains exposed to exchange-rate changes because many finished devices and insulin cartridges are imported. Import dependence can create price pressure when local currencies weaken against supplier invoicing currencies. It also creates friction with public-tender price ceilings that can adjust more slowly than input costs. Argentina faces a particularly acute risk because its insulin supply has been heavily import-dependent. Brazil is building domestic capacity, but its procurement needs remain large. Local manufacturing of insulin and cartridges can reduce this exposure over time, although imported inputs can still affect costs.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
South America Insulin Pens Market Segment Analysis
By Product Type:
Reusable Cartridges Lead Through Public ProcurementCartridges in reusable insulin pens accounted for 53.31% of the South America insulin pens market size in 2025. Their position reflects how public procurement programs evaluate the ongoing cost of insulin administration. SUS in Brazil favors compatible cartridge systems within its public dispensing structure. Argentina's reimbursement framework also supports the continued use of pen injectors for covered patients. Refillable formats can lower recurring treatment costs compared with single-use devices. This makes reusable products more suitable for systems that serve large numbers of patients over long periods.
Disposable insulin pens remain relevant in private care and at clinical initiation; their higher cost per use limits wider uptake where public systems control most dispensing volumes. Smart and connected insulin pens are projected to grow at a 9.58% CAGR through 2031. Urban private networks in Brazil are early channels for connected delivery tools. Modular Bluetooth caps can be fitted to reusable pens that patients already use. The clinical support for dose tracking strengthens the rationale for providers to adopt these tools.


By Diabetes Type:
Type 2 Diabetes Provides the Broadest Treatment BaseType 2 diabetes held 86.24% of the South America insulin pens market size in 2025. Most insulin-treated people in the region have a type 2 diagnosis. This creates a larger volume base than in markets where type 1 diabetes has historically led to premium pen adoption. Basal insulin initiation is important for patients whose glucose levels remain uncontrolled. Glargine cartridges and compatible reusable pens fit this pattern of treatment. The expected expansion of diabetes in South and Central America will largely add to the type 2 treatment population.
Type 1 diabetes has a smaller revenue position but remains important for device use. People with type 1 diabetes generally need multiple daily injections. That need can create higher per-patient use of pens, cartridges, and needles. Brazil's 2026 glargine pilot prioritized children and adolescents aged 2 to 17 with type 1 diabetes. It also included adults aged 80 and older with type 1 diabetes. Gestational and other diabetes is the smallest category, even though 1 in 6 live births in the region were affected by hyperglycemia in pregnancy in 2024.
By End User:
Home Use Leads While Hospital Initiation ExpandsHome and self-administration represented 44.14% of the South America insulin pens market share in 2025. Home use reflects the long-standing aim of helping patients manage insulin therapy outside hospitals. It can reduce avoidable pressure on healthcare facilities. Reusable systems suit this setting because patients can continue treatment with cartridge replacements. Home care also creates demand for accessible education and dependable supplies. Remote adherence support can be useful for patients who have limited mobility or cannot easily attend clinics.
Hospitals and clinics are forecast to grow at an 8.82% CAGR through 2031. They remain important points for starting insulin therapy and teaching correct pen use. Public hospitals in Brazil can act as both prescribing and dispensing centers. Hospitals also have a stronger role in Colombia, Peru, and Chile, where outpatient infrastructure is less developed. Ambulatory care centers are becoming more relevant in Argentina and Chile. These settings can provide pen training and monitor treatment adherence before patients shift to routine self-administration.
By Distribution Channel:
Retail Leads as Online Fulfillment ExpandsRetail pharmacies held 44.65% of the South America insulin pens market share in 2025. They provide pen needles and cartridge refills to patients in major urban areas. Private patients in Brazil, Argentina, and Colombia continue to use pharmacy outlets for recurring supplies. Hospital pharmacies handle institutional volume through public and reimbursed care pathways. Community health agents and primary care units also dispense products in Brazil's interior. Manufacturers need to account for the large public volumes that move through tenders rather than pharmacy trade channels.
Online pharmacies and e-commerce are forecast to grow at a 9.65% CAGR through 2031. The channel supports home delivery of cartridges and needles for patients with chronic treatment needs. Brazil's Meu SUS Digital platform and pharmacy delivery integrations support prescription-linked delivery services. Online fulfillment can reduce the need for repeated pharmacy visits in urban and peri-urban areas. It can also help reach locations where physical pharmacy networks are less developed. Reliable cold-chain handling and last-mile logistics remain necessary for this channel to expand safely.
Geography Analysis
Brazil Insulin Pens Market
Brazil accounted for 48.61% of the South America insulin pens market size in 2025. SUS gives Brazil a central role because it procures and distributes treatment supplies on a national scale. The February 2026 glargine pilot covered more than 50,000 patients in Amapá, Paraná, Paraíba, and the Federal District. It created direct demand for compatible reusable pen platforms. Novo Nordisk announced a BRL 6.4 billion (USD 1.09 billion) investment in April 2025 to expand its Montes Claros facility. Construction is expected to be completed in 2028, supporting long-term local production capacity.
Argentina Insulin Pens Market
Argentina is forecast to grow at a 9.75% CAGR through 2031. Its adult diabetes prevalence was 14%, the highest among South America's larger economies. Law 26.914 supports demand by requiring reimbursement for pen injectors across public and private payers. The country still faces supply risk from its reliance on imported insulin. Local biosimilar manufacturing could reduce some of this exposure. Currency changes and procurement timing remain important considerations for cartridge suppliers.
Broader South America Insulin Pens Market
Colombia, Chile, Peru, and the Rest of South America make up an underpenetrated group within the South America insulin pens market. Diabetes prevalence is increasing, but reimbursement and pharmacy infrastructure remain less developed than in Brazil. Colombia has faced periodic availability pressure and gaps in coverage for pen consumables. Chile has partial coverage through private insurance and the public Fonasa system. Peru has nationally representative diabetes data from the past 5 years, which can support more focused procurement planning. Growth in this group depends on better access, broader insurance, and more reliable supply arrangements.
Competitive Landscape
The South America insulin pens market is moderately concentrated around Novo Nordisk, Sanofi, Eli Lilly, and Becton, Dickinson and Company. Novo Nordisk, Sanofi, and Eli Lilly hold leading positions in insulin cartridge brands. Cartridge selection can influence the compatible pen platform selected by patients and public formularies. Becton, Dickinson and Company and Embecta provide pen needles that generate recurring demand with each injection. Public tenders in Brazil and Argentina favor companies with scale, competitive pricing, local affiliates, and established regulatory filings. Ypsomed and Owen Mumford compete in original equipment pen supply, while Terumo and HTL-Strefa participate in injection accessories.
Biomm, Fiocruz, and Gan & Lee aligned guidelines for national insulin glargine production in April 2025. Gan & Lee formalized its technology transfer and supply agreement in Brazil in 2025. These steps support local production of glargine and can affect price competition in public tenders. Biomm delivered its first insulin glargine batch in November 2025 and targets a capacity of 36 million cartridges by the end of 2026. Domestic production can lower the price floor for glargine cartridges while expanding public supply options. This strategy may also encourage other biosimilar suppliers to consider South American manufacturing arrangements[3]Fiocruz, “Fiocruz, Biomm and Gan & Lee Align Guidelines for National Production of Insulin Glargine,” Portal Fiocruz, fiocruz.br..
Connected systems are another area of competition in the South America insulin pens market. Medtronic's InPen platform is linked to the MiniMed Go Smart MDI system, which was cleared in January 2026. Novo Nordisk's NovoPen 6 uses NFC dose logging, which adds a digital layer to reusable pen use. The clinical trial on connected caps supports the relevance of compatibility across multiple cartridge formats. Rural and peri-urban areas in Brazil's North and Northeast and in Peru have thinner last-mile pharmacy coverage. Refill reminders and connected support tools may help providers maintain contact when in-person pharmacy support is limited.
South America Insulin Pens Industry Leaders
Novo Nordisk A/S
Sanofi
Eli Lilly and Company
Ypsomed Holding AG
Becton, Dickinson and Company
- *Disclaimer: Major Players sorted in no particular order
South America Insulin Pens Market Companies Covered in this Report
- B. Braun
- Beckton Dickinson
- Biocon
- Biomm S.A.
- Eli Lilly and Company
- embecta Corp.
- Funda??o Oswaldo Cruz
- Gan & Lee Pharmaceuticals Group Co., Ltd.
- HTL-Strefa S.A.
- Julphar
- Lupin
- Medtronic
- Novo Nordisk
- Owen Mumford Limited
- Roche
- Sanofi
- Sun Pharmaceuticals Industries
- Terumo
- Wockhardt Limited
- Ypsomed

Recent Industry Developments in South America Insulin Pens Market
- February 2026: Brazil's Ministry of Health initiated a pilot transition from NPH human insulin to long-acting glargine in SUS, covering over 50,000 patients across 4 states, Amapá, Paraná, Paraíba, and the Federal District, with training for primary-care professionals on insulin injection pen use.
- April 2025: Novo Nordisk announced a BRL 6.4 billion (USD 1.09 billion) investment to expand its Montes Claros, Minas Gerais facility. Construction began immediately, and operations are expected to start in 2028. The project adds a 74,000-square-meter plant with aseptic production capacity, a quality-control laboratory, and 600 permanent jobs. The investment targets GLP-1 products, including insulin pen-compatible formats.


South America Insulin Pens Market Report Scope
As per the scope of the report, an insulin pen is a medical device used to inject insulin for managing diabetes. It consists of a slender, portable pen-shaped container that holds a cartridge of insulin, a dose-setting dial, and a needle. The user can dial the required dose and inject insulin subcutaneously, making it a convenient and discreet alternative to traditional syringes.
The South America insulin pens market is segmented by product type into disposable insulin pens, cartridges for reusable insulin pens, and smart and connected insulin pens; by diabetes type into type 1 diabetes, type 2 diabetes, and gestational diabetes and other types of diabetes; by end user into home and self-administration, hospitals and clinics, ambulatory care centers, and other end users; by distribution channel into retail pharmacies, hospital pharmacies, online pharmacies and e-commerce platforms, and other distribution channels; and by country into Brazil, Argentina, Colombia, Chile, Peru, and the rest of South America. For each segment, the market size and forecast are provided in terms of value (USD).
| Disposable Insulin Pens |
| Cartridges in Reusable Insulin Pens |
| Smart and Connected Insulin Pens |
| Type 1 Diabetes |
| Type 2 Diabetes |
| Gestational and Other Diabetes |
| Home and Self-Administration |
| Hospitals and Clinics |
| Ambulatory Care |
| Other End Users |
| Retail Pharmacies |
| Hospital Pharmacies |
| Online Pharmacies and E-Commerce |
| Other Distribution Channels |
| Brazil |
| Argentina |
| Colombia |
| Chile |
| Peru |
| Rest of South America |
| By Product Type | Disposable Insulin Pens |
| Cartridges in Reusable Insulin Pens | |
| Smart and Connected Insulin Pens | |
| By Diabetes Type | Type 1 Diabetes |
| Type 2 Diabetes | |
| Gestational and Other Diabetes | |
| By End User | Home and Self-Administration |
| Hospitals and Clinics | |
| Ambulatory Care | |
| Other End Users | |
| By Distribution Channel | Retail Pharmacies |
| Hospital Pharmacies | |
| Online Pharmacies and E-Commerce | |
| Other Distribution Channels | |
| By Country | Brazil |
| Argentina | |
| Colombia | |
| Chile | |
| Peru | |
| Rest of South America |


Key Questions Answered in the Report
What is driving demand for insulin pens in South America?
Demand is supported by the growing insulin-treated population, public procurement, and the move toward glargine cartridges and reusable delivery systems.
How large is the South America insulin pens market in 2026?
The market was USD 0.88 billion in 2026 and is forecast to reach USD 1.15 billion by 2031 at a 5.51% CAGR.
Which product format leads to insulin pen use in South America?
Cartridges in reusable insulin pens led with 53.31% of revenue in 2025 because public systems favor lower recurring treatment costs.
Which country is growing fastest for insulin pens in South America?
Argentina is forecast to grow at a 9.75% CAGR through 2031, supported by mandatory reimbursement for pen injectors.
Why are smart insulin pens becoming more relevant in South America?
Smart and connected insulin pens are forecast to grow at a 9.58% CAGR through 2031, supported by dose-tracking features and clinical evidence.
What are the main barriers to broader insulin pen access?
Uneven reimbursement, patient out-of-pocket spending, import dependence, training gaps, and cold-chain challenges limit access in several countries.
Page last updated on:



