
Vietnam Data Center Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.79 Billion |
| Market Size (2026) | USD 0.86 Billion |
| Market Size (2031) | USD 1.33 Billion |
| Growth Rate (2026 - 2031) | 9.03 % |
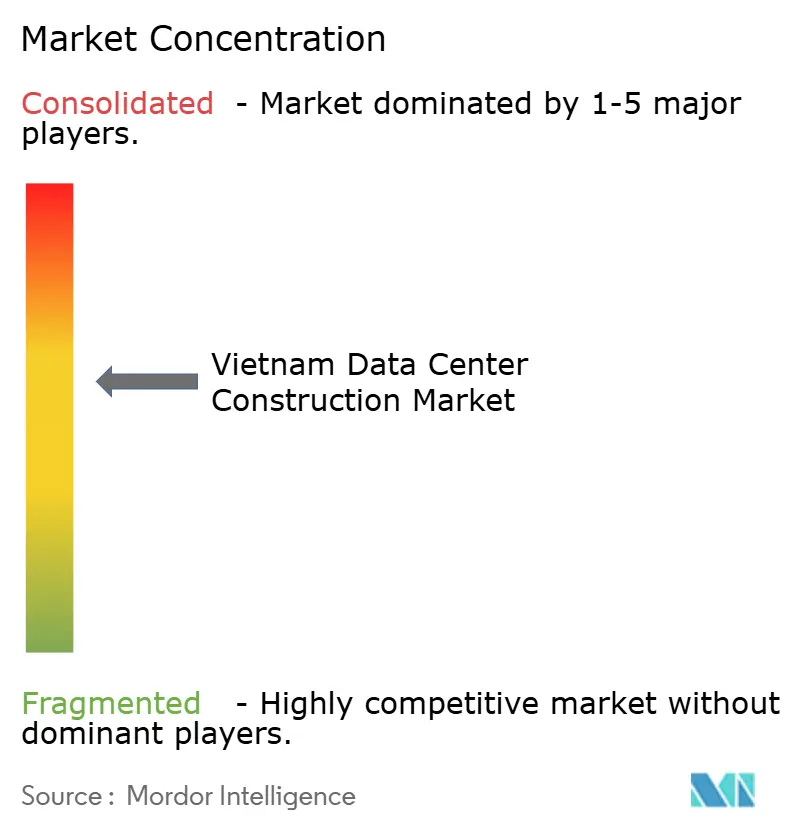
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Vietnam Data Center Construction Market Analysis by 麻豆视频
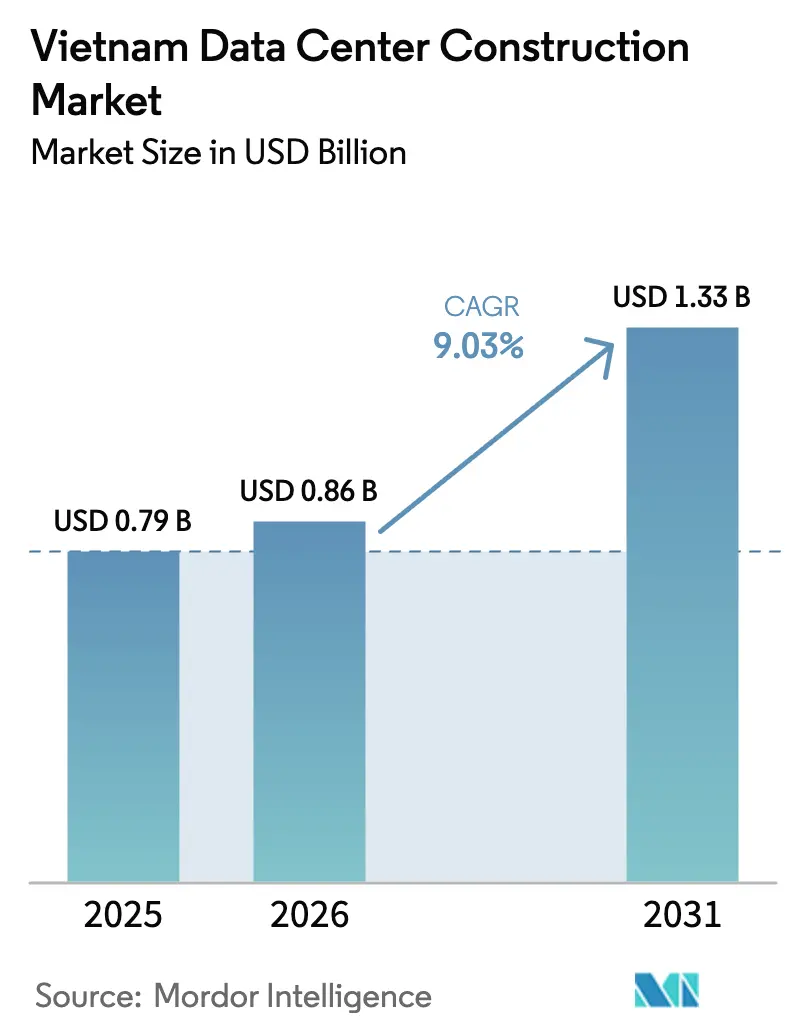
The Vietnam data center construction market size was valued at USD 0.79 billion in 2025 and estimated to grow from USD 0.86 billion in 2026 to reach USD 1.33 billion by 2031, at a CAGR of 9.03% during the forecast period (2026-2031). Rapid digital-sovereignty regulations, the rollout of renewable power-purchase agreements, and record submarine-cable expansions have combined to position Vietnam as Southeast Asia’s next large-scale hosting hub. A national data center scheduled for completion in late-2025, full foreign-ownership liberalization, and a 50 Tbps Asia Direct Cable now in service collectively lower market-entry barriers while lifting demand visibility. Domestic telcos leverage legacy fiber assets and early‐mover colocation campuses to retain dominant share, yet hyperscalers now deploy self-build facilities to meet localization mandates faster. Investor appetite remains buoyant despite grid-stability concerns because long-term PPAs cut energy-cost risk, while 5G densification pushes compute closer to users and unlocks edge-center opportunities.
Key Report Takeaways
- By tier rating, Tier 3 sites led with 60.75% of the Vietnam data center construction market share in 2025, whereas Tier 4 sites are projected to grow at 11.7% CAGR through 2031.
- By data-center type, the colocation segment held 56.70% revenue share of the Vietnam data center construction market size in 2025, while the self-build hyperscaler segment records the fastest 12.9% CAGR to 2031.
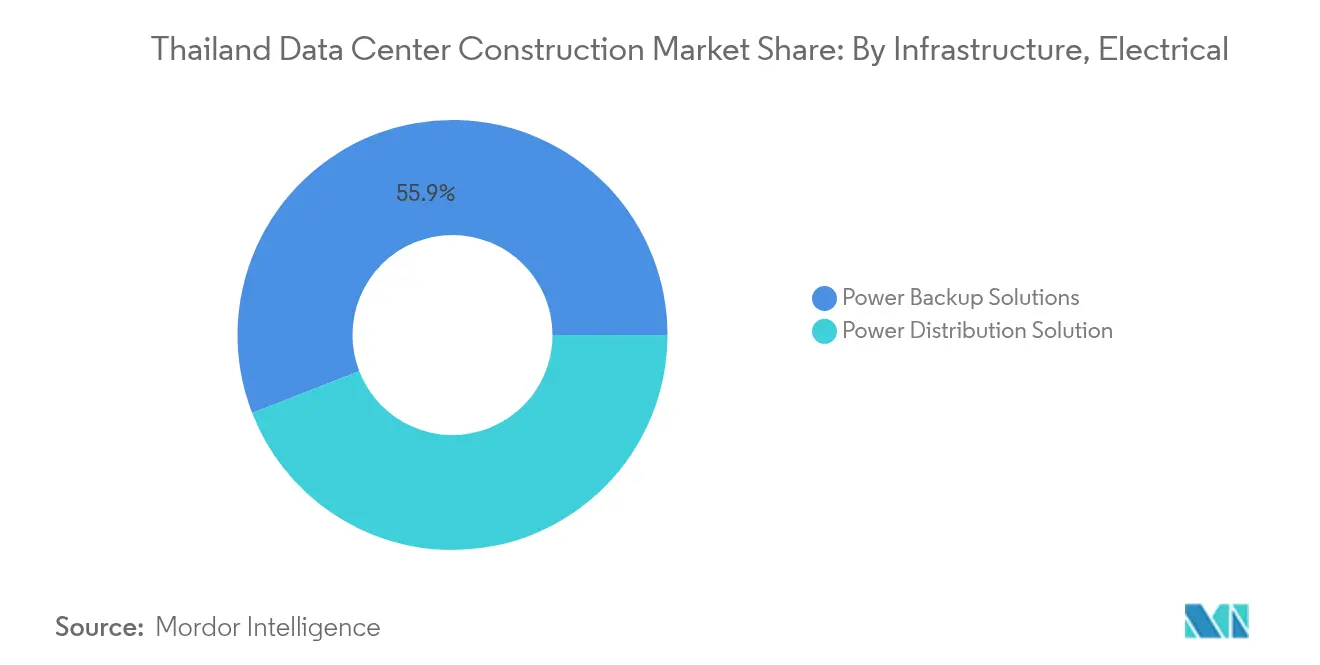
- By electrical infrastructure, power-backup solutions captured 55.90% of the Vietnam data center construction market share in 2025; power-distribution systems expand at 13.6% CAGR during 2026-2031.
- By mechanical infrastructure, cooling systems accounted for 44.85% of the Vietnam data center construction market size in 2025, yet server & storage hardware advances at a 13.9% CAGR to 2031.
- Viettel, VNPT, FPT, and CMC Telecom collectively commanded roughly 96.60% market share in 2025.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Vietnam Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data-localization mandate (Decree 53) | +2.1% | National, with concentration in Ho Chi Minh City and Hanoi | Short term (≤ 2 years) |
| Cloud and OTT traffic boom | +1.8% | National, with spillover to secondary cities | Medium term (2-4 years) |
| Low power tariffs and renewable PPAs | +1.4% | National, with advantages in renewable-rich provinces | Long term (≥ 4 years) |
| Nationwide 5G + fiber backhaul rollout | +1.2% | National, with early gains in major urban centers | Medium term (2-4 years) |
| Sub-sea cable expansion (ADC2, SJC2) | +0.9% | National, with primary impact on coastal landing points | Short term (≤ 2 years) |
| Green-finance access for "net-zero" DCs | +0.7% | National, with focus on industrial parks | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Data-Localization Mandate Drives Demand
Vietnam’s Decree 53 and the comprehensive Data Law effective July 2025 oblige global platforms to store designated “important” and “core” data onshore.[1]Hogan Lovells — “Vietnam’s New Data Law Enters Into Force July 2025,” hoganlovells.com Compliance timelines accelerate facility sourcing, evidenced by Alibaba shifting from state-rented racks to dedicated builds. The government-funded National Data Center, due late-2025, sets common security and redundancy baselines that raise enterprise expectations. Google’s plan for its first domestic hyperscale site underlines how sovereignty statutes now dictate footprint strategies. Together these policies create a predictable, captive pipeline for local construction contractors.
Cloud and OTT Traffic Surge Amplifies Infrastructure Needs
Commercial 5G went live nationwide in October 2024 and averaged 247.78 Mbps download by March 2025, enabling UHD streaming and cloud gaming that swell back-end compute demand. Government targets guarantee 200 Mbps fixed speeds for 90% of households by 2025,[2]Developing Telecoms — “Vietnam Targets 200 Mbps Universal Fixed Broadband,” developingtelecoms.com while enterprises gain symmetric 1 Gbps pipes. Viettel’s ongoing 140 MW campus with 60 kW racks epitomizes how service-provider traffic forecasts translate directly into high-density design. Each incremental rise in last-mile capacity multiplies local processing workloads, sustaining utilization rates well above regional averages.
Renewable-Energy Access Transforms Economics
Direct Power Purchase Agreements effective March 2025 permit data-center buyers to source electricity straight from wind and solar producers. Power Plan VIII targets up to 36% renewables by 2030, channeling USD 136.3 billion into grid expansion. Viettel’s Hoa Lac campus secured the nation’s first green credit loan from HSBC, signalling capital-market preference for low-carbon builds nld.com.vn. Regional solar tariffs ranging 1,012–1,383 VND/kWh let operators arbitrage geography for cheaper and greener electrons.[3]Ministry of Industry and Trade — “Solar Tariff Framework 2025,” moit.gov.vnLong-dated PPAs therefore curb OPEX volatility and advance ESG credentials simultaneously.
Nationwide 5G Rollout Creates Edge-Compute Demand
Decree 88/2025 subsidizes carriers installing 20,000+ 5G sites by end-2025, front-loading latency-sensitive use cases. The Science & Technology ministry’s digital infrastructure plan allocates 788 MW total designed capacity by 2030, stipulating green builds that support AI at the edge. As spectrum utilization climbs, content providers shift workloads to micro-edge modules co-located within aggregation nodes, expanding addressable construction beyond primary metros.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High imported CAPEX / OPEX | -1.6% | Stronger effect on foreign builders | Short term (≤ 2 years) |
| Skilled MEP commissioning talent gap | -1.2% | Ho Chi Minh City & Hanoi | Medium term (2-4 years) |
| Grid instability in hydropower-lean seasons | -0.9% | Northern provinces | Short term (≤ 2 years) |
| Speculative AI-DC overbuild bubble risk | -0.8% | Major urban centers | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
High Import Dependency Raises Costs
Vietnam’s semiconductor base still emphasizes design, forcing imports of precision switchgear, chillers, and GPUs, exposing builders to freight surcharges and currency swings. Construction-cost benchmarks issued under Decision 409/Q?-BXD cannot offset equipment price escalation when global supply tightens. Schneider Electric’s pivot to expand manufacturing in the United States underscores how suppliers are regionalizing, leaving Southeast Asian buyers vulnerable to lead-time gaps
MEP-Skills Shortage Delays Projects
The domestic ICT workforce will be 200,000 specialists short by 2025, with acute deficits in high-density cooling, UPS commissioning, and AI-optimized rack integration. Government program 1002/Q?-TTg targets skills uplift through 2035, but near-term gaps inflate labor premiums and extend ramp-up schedules. Binh Dinh’s plan to train 7,500 semicon and AI engineers is promising yet insufficient at national scale, magnifying execution risk for concurrent hyperscale builds
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Reliability Push Elevates Tier 4 Growth
Tier 3 sites retained 60.75% market share in 2025 as most enterprises still balance redundancy and capex prudence. The Vietnam data center construction market size for Tier 3 therefore remained largest, while Tier 4 operations set the fastest 11.7% CAGR trajectory into 2031. Investors interpret frequent power-quality incidents as justification for moving workloads to fully concurrent systems, even when capital costs rise. Viettel’s 140 MW Tan Phu Trung campus targets Tier III certification yet benches Tier IV-ready modules for AI clusters, signalling a transitional design mindset.
Higher-tier momentum also mirrors hyperscaler tolerance thresholds; GPU training clusters cannot risk downtime without jeopardizing multi-day job runs. NVIDIA’s memorandum with the Vietnamese government to open an AI R&D center imposes Tier 4 baselines on supply-chain partners. As the Vietnam data center construction market broadens, Tier 4 build-to-suit contracts drive premium service revenues, while Tier 1/2 footprints contract toward dev-test and local-edge use cases.


By Data Center Type: Hyperscaler Self-Build Era
Colocation retained 56.70% share in 2025, anchoring the Vietnam data center construction market. Nonetheless, self-build hyperscale programs clock a 12.9% CAGR as Google, Alibaba, and regional OTT players prioritize full-stack control. Deregulation in 2024 allowing 100% foreign ownership eliminates equity constraints that once steered entrants toward colocation leases.
Joint-venture blueprints remain relevant; STT GDC’s alliance with VNG combines local permits and land banks with international best-practice construction. Yet most hyperscalers favor outright greenfield builds to integrate proprietary network fabrics, specialized security, and custom-AI chip clusters. The trend forces colocation incumbents to chase differentiation via edge-site density, sovereign-cloud tiers, or sector-specific compliance wrappers.
By Electrical Infrastructure: Distribution Overhauls Outpace Backup
Power-backup equipment still comprised 55.90% of Vietnam data center construction market share in 2025 because diesel gensets and UPS strings remain foundational amid grid curtailments. However, Vietnam data center construction market size for power-distribution gear expands at a stronger 13.6% CAGR through 2031, propelled by AI rack densities hitting 60 kW. Schneider Electric and NVIDIA jointly launched reference designs that embed busway-level telemetry and software-defined power quality, redefining distribution architectures.
Hydropower-shortfall episodes saw 11 dams shut units in 2024, cutting 50.8 million kWh supply in single days, underscoring that redundant power paths alone are insufficient without intelligent distribution. Consequently, developers deploy adaptive switchboards, battery-energy-storage systems, and grid-interactive controllers that shave peak and harvest tariff arbitrage. Power-usage-effectiveness targets below 1.4 now hinge more on smart distribution than on backup runtime alone.
By Mechanical Infrastructure: AI-Optimized Servers Gain Ground
Cooling held 44.85% share in 2025; Vietnam’s tropical humidity makes advanced chillers and CRAH arrays unavoidable base cost. Yet servers and storage post the highest 13.9% CAGR as generative-AI pipelines proliferate. Here, the Vietnam data center construction market size rise stems from 8-GPU baseboards and NVMe over-fabric arrays that push per-rack draw sixfold.
Viettel’s upcoming facility integrates back-door liquid exchangers to sustain 60 kW racks without raising white-space temperatures above 27 °C. Off-site examples such as Digital Edge’s PUE 1.193 Manila plant prove tropical AI halls can hit efficiency benchmarks through aisle containment and heat-recovery loops. Vietnamese operators now embed AI-based building-management systems that tune fan curves, thereby shrinking chiller energy by up to 12%, reinforcing the link between mechanical innovation and OPEX competitiveness.
Geography Analysis
Ho Chi Minh City anchors capacity deployment, hosting Viettel’s 140 MW flagship—Vietnam’s first triple-digit-megawatt campus and a top-10 Southeast-Asian facility. Its pull factors include clustered submarine-cable landings, industrial-park land reserves, and a dense digital-economy customer base. Hanoi ranks second; CMC’s USD 300 million CCS complex widens the capital region’s footprint and caters to ministries seeking compliant sovereign-cloud hosting.
Da Nang is maturing as the third node; six active sites now offer 500 racks, and a 1,000-rack expansion broke ground in March 2025, leveraging the city’s ambitions as an international financial center. National cable policy adds up to four new 60 Tbps systems by 2025, dispersing connectivity resilience and enabling secondary-city feasibility. The Asia Direct Cable, live since April 2025, multiplies available international bandwidth, letting operators optimize latency and disaster-recovery topologies across the coastal axis.
Regional differentials in solar PPA tariffs (South 1,012 VND/kWh versus North 1,383 VND/kWh) guide hyperscalers to southern provinces for mega-campuses while encouraging northern builds to over-spec backup and establish renewable microgrids. Consequently, the Vietnam data center construction market exhibits a hub-and-spoke layout in which primary metros host multi-story flagships, and edge clusters fan out along 5G aggregation rings.
Regulatory Landscape
Vietnam regulates data center development through a mix of telecom classification, data-sovereignty rules, and technical standards. Under the Law on Telecommunications No. 24/2023/QH15 (effective 1 July 2024), data center services are treated as value-added telecommunications services, keeping oversight centered on the Ministry of Information and Communications (MIC) and its implementing bodies such as the Authority of Information Security (AIS). Data governance tightened further when the Data Law took effect on 1 July 2025, reinforcing onshore storage requirements for designated data categories and positioning data centers as part of national infrastructure.
From 2026, compliance and investment mechanics shift again. The Personal Data Protection Law (effective 1 January 2026) introduces stricter cross-border transfer assessments and breach-notification obligations, shaping how global platforms design Vietnam footprints and security controls. Separately, Decree No. 96/2026/ND-CP (effective 31 March 2026) streamlines investment procedures and expands incentives for AI/cloud data centers and green technology. On the technical side, Circular 03/2013/TT-BTTTT (as amended by Circular 23/2022/TT-BTTTT) and TCVN 9250:2021 guide infrastructure requirements, including reference international benchmarks such as ANSI/TIA-942-B and Uptime Institute Tier standards, which influence specification choices for Tier 3 and Tier 4 builds.
Value Chain Analysis
Vietnam's data center construction value chain begins with site selection and power and network provisioning, then moves through design, general construction, MEP fit-out, and commissioning, before transitioning to operations and refresh cycles. Land sourcing and permitting often cluster around industrial parks and urban campuses with access to high-capacity fiber backbones, while international connectivity is reinforced by submarine-cable systems that concentrate demand in nodes such as Ho Chi Minh City and Hanoi. Power procurement has become more strategic since direct renewable PPAs became available in 2025, which affects where developers place larger campuses and how they shape energy and sustainability requirements early in project planning.
Delivery execution reflects both domestic operator-led programs and global technology stacks. State-backed telecom operators (Viettel IDC, VNPT, FPT Telecom, and CMC Telecom) sit at the center as owner-operators and anchor tenants, shaping demand for local civil contractors, MEP installers, and commissioning specialists. International entrants and partners such as NTT GDC, ST Telemedia Global Data Centres, and Keppel DC contribute data hall design practices, program management, and procurement leverage for imported critical equipment (UPS, switchgear, chillers, and high-density IT hardware), while also introducing lead-time and price volatility for specific components. This mix keeps local execution capacity central, but it also means many high-spec components and reference architectures are sourced and validated through global OEM and standards frameworks.
Competitive Landscape
Domestic telcos Viettel, VNPT, FPT, and CMC collectively held 97% market share in 2024, supported by legacy fiber backbones and preferential access to government workloads. Foreign-ownership liberalization in 2024 shifts the competitive field; NTT inaugurated Ho Chi Minh City 1 with 6 MW at Tier III and is scouting a second 20 MW. STT GDC partnered VNG to acquire land and start a 120 MW campus, introducing Singapore-grade design standards.
Strategy now pivots on AI readiness and sustainability. Schneider Electric-NVIDIA ecosystems embed liquid cooling and DCIM-with-GPU telemetry, giving early adopters a performance edge. Domestic incumbents retaliate by pre-leasing entire data halls to cloud players on long tenures, locking in revenue while funding efficiency retrofits. Edge-compute specialists emerge to service the 20,000-base-station 5G grid; micro-DC operators pursue <500 kW pods inside industrial parks, meeting ultra-low-latency use cases.
Barriers to entry remain non-trivial: land conversion approvals can stretch 12 months, and talent scarcity inflates commissioning overhead. Yet capital inflows persist as sovereign-cloud certainty offsets execution risk, setting Vietnam’s investment narrative apart from peers facing political volatility.
Vietnam Data Center Construction Industry Leaders
Viettel IDC
VNPT (VNPT NET + VNPT IDC)
FPT Telecom Data Center
CMC Telecom
NTT GDC Vietnam
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Compliance-led capacity buildout is one of the clearest opportunity areas, linked to Vietnam's tightening data governance and security obligations. With the Data Law in force from July 2025 and the Personal Data Protection Law effective January 2026, global platforms and regulated industries have stronger incentives to place sensitive workloads onshore. That creates whitespace for compliant colocation and build-to-suit facilities that align with MIC-linked technical requirements, including Circular 03/2013/TT-BTTTT as amended and TCVN 9250:2021 referencing ANSI/TIA-942-B or Uptime tiers. Decree No. 96/2026/ND-CP further improves the investable pathway by streamlining procedures and expanding incentives for AI/cloud and green-technology data centers, supporting a broader pipeline beyond incumbent telco campuses.
A second opportunity is scaling AI-ready, energy-optimized builds as operators shift from conventional enterprise halls toward high-density designs. Viettel's June 2026 milestone at Hoa Lac 2 (Tier III certified and integrating NVIDIA H200 systems) points to tangible demand for advanced electrical distribution, cooling innovations, and higher-grade commissioning services, not just shell construction. In parallel, plans that call for new large-scale data centers meeting international and green standards support renewable sourcing structures and efficiency-driven retrofits. For contractors and suppliers, the actionable whitespace includes Tier-aligned design and consulting, power distribution modernization, liquid and heat-exchanger cooling integration, and security-led facility hardening that aligns with evolving breach-notification and cross-border transfer controls.
Recent Industry Developments
- June 2026: Hoa Lac 2 Data Centre integration of NVIDIA H200 GPU supercomputing systems and Tier III Certification of Constructed Facility. The AI ready data center anchors Vietnam's position as an AI and tech hub, reinforcing national digital transformation goals.
- June 2026: Groundbreaking for Tan Phu Trung Industrial Park data center campus in Ho Chi Minh City (approx. 140MW, ~10,000 racks). The large scale campus expansion strengthens hyperscale capacity and expands the regional data-center footprint, signaling aggressive capacity buildout to meet demand.
- February 2026: Cooperation agreements with G42 and a Viet Thai investor consortium to develop hyperscale data center infrastructure for AI and cloud. The collaboration broadens Vietnam's AI and Cloud ecosystem and accelerates hyperscale deployment through foreign partnerships.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the value of building and fitting out data centers in Vietnam, including the civil build and the core infrastructure that makes the facility operational, such as power and cooling systems.
Scope exclusions: Pure IT hardware procurement (servers, storage, and networking), telecom services, and ongoing operations and maintenance spending are excluded from the construction market value.
Segmentation Overview
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service - Design and Consulting, Integration, Support and Maintenance
- By Electrical Infrastructure
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to map the construction demand pool and to ground the model in observable signals that can be checked over time. We relied on public sources such as Vietnam's General Statistics Office releases, customs and trade statistics, the Ministry of Information and Communications updates, and electricity sector publications from Vietnam Electricity, which helps explain site readiness and build timing.
To connect project pipelines with cost realities, we also reviewed materials from industry bodies and standards references such as Uptime Institute style tier definitions, along with company filings, investor presentations, and credible news coverage that confirm announced builds, expansions, and location choices. In parallel, we used paid subscriptions for company financials and intelligence, and for patent databases where relevant to cooling and power designs, so construction activity and technology direction could be cross-checked. These desk sources are illustrative only, and many additional public and paid references were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work was carried out through expert interviews and structured surveys with contractors, consultants, operators, and key buyers involved in Vietnam data center builds. We used these discussions to confirm what is being built (new build versus expansion), typical cost-per-MW ranges, timeline risks tied to power availability, and how tier targets change the design and spend profile across Hanoi and Ho Chi Minh City.
Coverage was balanced to reflect different company sizes and roles, so assumptions taken from public announcements could be tested and adjusted before the final model was locked.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 31% | CXOs: 17% |
| Mid tier: 51% | Functional/Unit leaders: 36% |
| Smaller Players: 18% | Managers: 47% |
Market-Sizing & Forecasting
Sizing starts from a top-down build pipeline view, where planned IT load additions and facility counts are translated into construction outlays using Vietnam-appropriate cost-per-MW benchmarks and infrastructure splits. Once the demand pool is reconstructed this way, we corroborate it with selective bottom-up checks, such as sampled project budgets by tier level, contractor revenue exposure to data centers, and sanity checks on mechanical and electrical package costs.
Key inputs used in the model include: announced and under-construction capacity in MW, typical construction cost per MW (including the local range), the mix of tier targets (Tier 3 and Tier 4 requirements usually lift redundancy and cost), and the split of spend across general construction, electrical systems, and mechanical systems. Where project data is incomplete, gaps are handled by applying conservative cost bands and phasing rules that were validated in interviews, then re-tested against public permitting and commissioning signals.
For forecasting, scenario analysis is used because timing is sensitive to power availability, land readiness, and the pace of new project announcements. The base case is built from the most repeated expectations from primary respondents, and then stress-tested with slower and faster build schedules so the final outlook is not driven by a single optimistic assumption.
Data Validation & Update Cycle
Validation is done by checking the model outputs against independent signals, and then investigating variances before final sign-off. We run anomaly checks at multiple levels, including year-over-year jumps, cost-per-MW drift, and whether implied construction spend aligns with observed capacity additions and known project milestones.
A second analyst review is completed before the report is finalized, and re-contact is triggered when a key input moves materially, such as a large project delay, a major change in power pricing signals, or a new regulation that changes build feasibility. Reports are refreshed annually, with interim updates when material events occur, and a final pre-delivery pass is done so clients receive the most current view available at release time.
麻豆视频's Vietnam Data Center Construction Market Sizing Compared With Other Published Estimates
Published market values for Vietnam data center construction can differ even when the topic name looks the same, since each publisher may count a different set of construction items and may use different timing rules for when spend is recognized.
By tracking project-level MW additions and refreshing cost-per-MW and infrastructure share assumptions with primary checks, 麻豆视频 keeps the Vietnam construction number tied to build-out activity rather than mixing in broader data center revenues or unrelated IT spend. A second driver is how tier and redundancy are treated, because including higher-tier electrical and mechanical scope can lift the total, while some estimates apply a single average cost that misses this mix shift.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 0.79 B (2025) | |
| Trade Journal A | USD 0.65 B (2024) | Often cited as a data center market value, which can blend colocation or hosting revenues with investment activity, and it may not isolate construction scope and timing of spend recognition. |
| Industry Advisory B | USD 0.76 B (2025) | Uses construction cost-per-MW benchmarks but can undercount general construction and fit-out items, and it may treat planned capacity as committed without applying realistic phasing and delay factors. |
The table shows that the spread mostly comes from scope boundaries and from how project timing is converted into annual spend. When the model is anchored to MW build-outs, local cost bands, and tier-driven infrastructure differences, the resulting market size is easier to trace and to re-check in the next update cycle.


Key Questions Answered in the Report
How big is the Vietnam Data Center Construction Market?
The Vietnam Data Center Construction Market size is expected to reach USD 0.86 billion in 2026 and grow at a CAGR of 9.03% to reach USD 1.33 billion by 2031.
What is the current Vietnam Data Center Construction Market size?
In 2026, the Vietnam Data Center Construction Market size is expected to reach USD 0.86 billion.
Who are the key players in Vietnam Data Center Construction Market?
Turner Construction Company, Artelia Group, AECOM, Coteccons Construction Joint Stock Company and Rider Levett Bucknall are the major companies operating in the Vietnam Data Center Construction Market.
What years does this Vietnam Data Center Construction Market cover, and what was the market size in 2025?
In 2025, the Vietnam Data Center Construction Market size was estimated at USD 0.86 billion. The report covers the Vietnam Data Center Construction Market historical market size for years: 2019, 2020, 2021, 2022, 2023 and 2024. The report also forecasts the Vietnam Data Center Construction Market size for years: 2026, 2027, 2028, 2029, 2030 and 2031.
Page last updated on:
- Data Center Power Market Power systems across all regions, split by component, tier and facility size.
- Artificial Intelligence (AI) Data Center Market AI facilities across all regions, split by facility type, component and tier.
- Vietnam Data Center Power Market Power systems demand across Vietnam, covering component, facility type and facility size.
- South Korea Data Center Power Market South Korea's power systems, split by facility size and tier.
- Thailand Data Center Power Market Power systems in Thailand, split by component, facility type and facility size.
- Vietnam Hyperscale Data Center Market Hyperscale sites in Vietnam, split by facility type, component and tier.
- South Korea Data Center Rack Market South Korea's racks, split by rack size, rack height and rack type.



