
Africa Mining Equipment Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 3.13 Billion |
| Market Size (2026) | USD 3.26 Billion |
| Market Size (2031) | USD 4.02 Billion |
| Growth Rate (2026 - 2031) | 4.24 % |
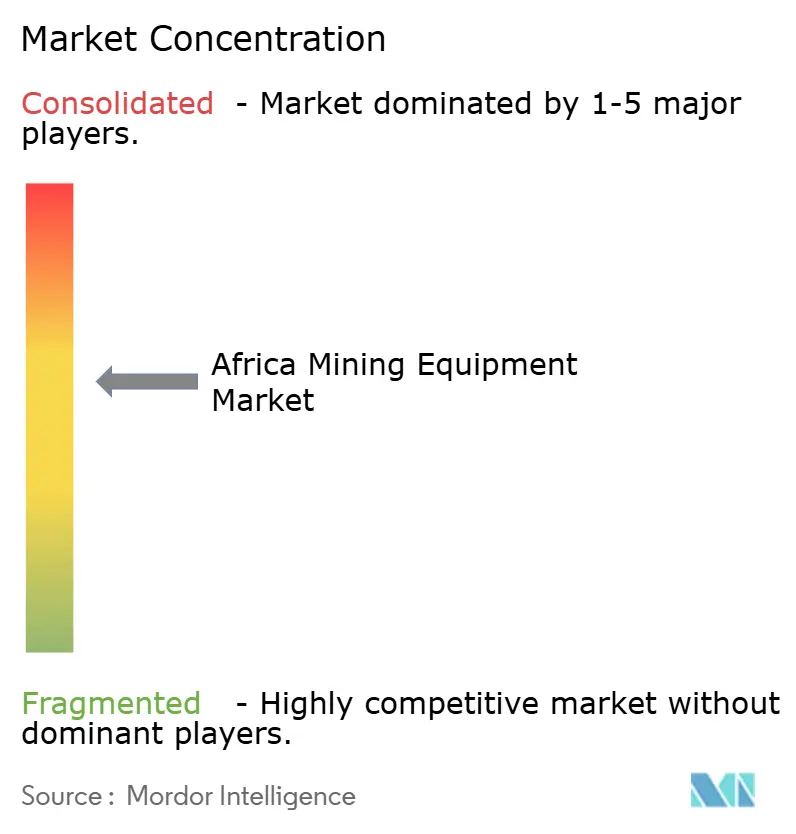
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Africa Mining Equipment Market Analysis by 麻豆视频
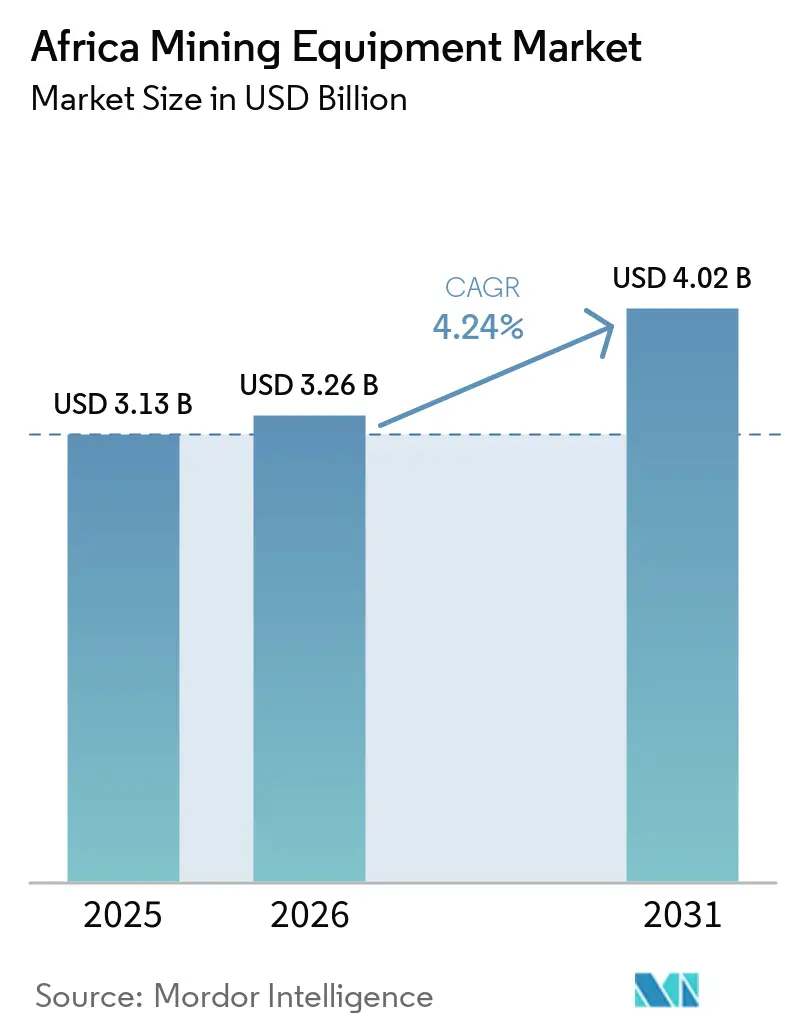
The Africa mining equipment market size was valued at USD 3.13 billion in 2025 and is projected to expand from USD 3.26 billion in 2026 to USD 4.02 billion by 2031, registering a CAGR of 4.24% between 2026 and 2031. Surface-mining machinery continues to dominate demand as operators pursue large, open-pit projects that shorten pay-back periods and simplify fleet logistics. Battery-electric haulage and drilling systems are gaining traction as carbon-pricing schemes, grid expansions, and total cost-of-ownership savings improve project economics. Government-backed rail corridors, such as the Lobito Railway, now unlock stranded deposits and compress haulage costs, while localized rebuild centers reduce downtime and foreign-exchange exposure. Meanwhile, Chinese original equipment manufacturers (OEMs) intensify price competition, prompting established Western brands to carve out defensible positions in automation, digital services, and component remanufacturing.
Key Report Takeaways
- By equipment type, surface-mining machinery led with a 46.65% share of the African mining equipment market in 2025, whereas loaders and haul trucks are forecast to expand at a 5.17% CAGR through 2031.
- By automation level, manual fleets held 66.73% share of the African mining equipment market in 2025, while fully autonomous systems are projected to record the fastest projected CAGR at 18.38% through 2031.
- By powertrain, internal-combustion units captured a 72.45% share of the African mining equipment market in 2025, while battery-electric units are advancing at an 8.55% CAGR through 2031.
- By power output, the 500–1,000 HP bracket accounted for 47.02% share of the African mining equipment market in 2025, while equipment below 500 HP is projected to grow at 6.12% over 2026–2031.
- By application, metal mining commanded 53.71% share of the African mining equipment market in 2025, yet mineral mining demand is estimated to rise at a 5.63% CAGR by 2031.
- By country, South Africa held a 39.66% share of the African mining equipment market in 2025, while the Democratic Republic of Congo (DRC) is poised for the fastest expansion, at 5.68%, through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Africa Mining Equipment Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Surface Mining in Africa | +1.5% | DRC, Guinea, South Africa | Medium term (2-4 years) |
| Infrastructure Projects Driving Iron-Ore & Aggregates | +1.2% | South Africa, Guinea, Algeria, Nigeria | Short term (≤ 2 years) |
| Investments in Electric Mining Trucks | +0.8% | South Africa, DRC, Ghana, Nigeria | Long term (≥ 4 years) |
| Rare-Earth Exploration Boosting Drilling Demand | +0.6% | South Africa, DRC, Niger, Algeria | Medium term (2-4 years) |
| Predictive Maintenance via Satellite Connectivity | +0.4% | South Africa and major operations continent-wide | Short term (≤ 2 years) |
| OEM Assembly & Rebuild Localization in Africa | +0.3% | South Africa, Botswana, Nigeria, Ghana | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Rapid Expansion of Surface Mining Projects in Africa
Open-pit mega-projects such as Guinea’s Simandou iron ore complex and the DRC’s USD 28.9 billion MIFOR development are fueling orders for ultra-class haul trucks, high-capacity rope shovels, and crushing circuits [1]"Zambia Pushes for Mineral Processing to Drive Industrial Growth," Copperbelt Katanga Mining, copperbeltkatangamining.com. Komatsu announced a major contract to deliver five PC5500-11 excavators to Simandou in February 2025[2]"Komatsu Announces Major Contract to Equip Simandou Iron Ore Mine," Komatsu Europe International N.V., komatsu-africa.com, illustrating how 400-tonne-class machinery lowers haulage costs and boosts productivity. Local rebuild hubs, for example, Tractafric Equipment’s facility in Morocco, now refurbish key components to shorten lead times and strengthen after-sales offerings. Surface fleets, therefore, anchor replacement demand and underpin nearly half of the African mining equipment market through 2031.
Government-Led Infrastructure Programs Boosting Iron-Ore and Aggregates Demand
Multilateral financing of the 1,300 km Lobito Corridor compresses transport costs for copper and iron ore, stimulating procurement of rail-loading hoppers and mobile crushers. Guinea’s commitment to complete a 670 km rail line by 2028 likewise requires track-laying and aggregate-processing machinery[3]David Uwakwe, "Trans-Guinean Railway unveils passenger plans," International Railway Journal, railjournal.com. South Africa’s National Development Plan allocates nearly one-fifth of its infrastructure budget to mining-linked logistics upgrades, sustaining demand for graders and pavers. Public-sector infrastructure agendas, therefore, reinforce steady equipment orders despite commodity-price cycles.
Rising Investments in Battery-Electric Mining Trucks
Epiroc secured a SEK 380 million (USD 39.69 million) purchase in 2024 for battery-electric loaders and trucks, while XCMG supplied seven XDE260 electric haul trucks to Exxaro’s Grootegeluk mine in February 2026. Trials show diesel-reduction benefits exceeding 20% and maintenance savings of nearly 18%, strengthening the business case even where grid stability is variable. Eskom’s 1,200 MW of renewable capacity added in 2025 now enables Northern Cape mines to charge fleets at off-peak tariffs of sub-ZAR 0.80/kWh (~USD 0.043/kWh), propelling uptake across the African mining equipment market.
Growth in Rare-Earth Exploration Driving Specialized Drilling Demand
Projects in Angola, such as Longonjo, and in South Africa, such as Phalaborwa, are significantly influencing demand for advanced reverse-circulation and diamond-core rigs. These rigs are particularly valued for their ability to handle complex geological formations at considerable depths. Additionally, operations at Longonjo are driving demand for specialized equipment, including flotation cells and magnetic separators, to support resource extraction. Meanwhile, the introduction of automated sampling systems, planned for use at Malawi's Songwe Hill, highlights the growing emphasis on integrating advanced technologies into early-stage exploration.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Commodity-Price Volatility | -0.7% | South Africa, DRC, Zambia, Ghana | Short term (≤ 2 years) |
| Cost of Autonomous and Electric Equipment | -0.5% | South Africa, Botswana, Namibia | Medium term (2-4 years) |
| Supply-Chain Disruptions | -0.3% | DRC, Zambia, South Africa | Short term (≤ 2 years) |
| Counterfeit Spare-Parts Proliferation | -0.2% | Nigeria, Tanzania, Ghana, DRC | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Commodity-Price Volatility Affecting CAPEX Cycles
In recent times, copper prices have declined sharply, prompting producers in regions such as the DRC and Zambia to delay planned expansions and scale back equipment orders. This trend reflects a broader downturn in the commodity market, with key materials such as iron ore, coal, and base metals also facing price pressures. These fluctuations force OEMs to remain agile, adjusting production schedules and maintaining inventories of critical spare parts to ensure uninterrupted service delivery and contract fulfillment.
High Upfront Cost of Autonomous and Electric Equipment
The adoption of autonomous and electric equipment faces challenges due to their high upfront costs compared to traditional diesel-powered alternatives. Retrofitting existing equipment to incorporate advanced technologies further adds to the financial burden. Additionally, limited access to affordable financing and a shortage of skilled technicians create barriers to widespread implementation, particularly for mid-sized operators in regions such as Southern Africa. These challenges highlight the need for strategic planning and investment to overcome the hurdles associated with transitioning to more advanced equipment.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Equipment Type: Surface Mining Commands Spend Amid Electrification
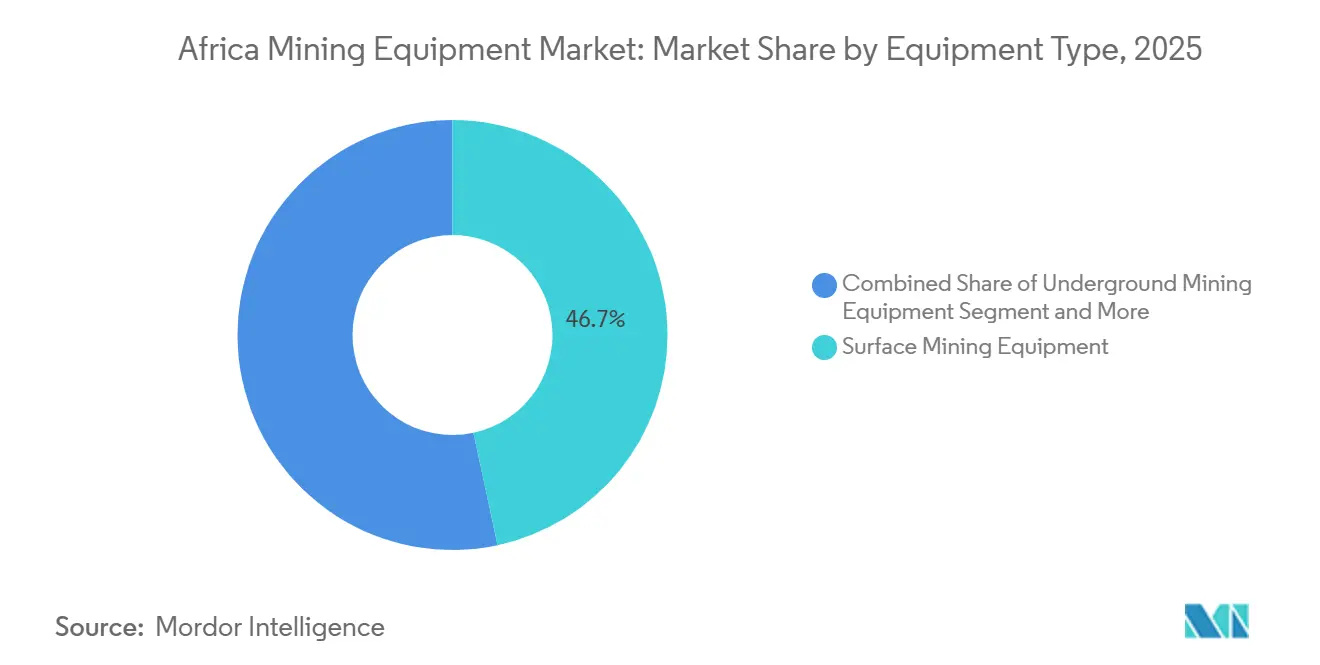
Surface machinery accounted for 46.65% of the African mining equipment market in 2025. The adoption of 400-tonne rope shovels and 220-tonne haul trucks enhances economies of scale in iron ore and copper operations. The segment benefits from tax incentives that favor zero-emission loaders, spurring pilot deployments of battery-electric units at platinum sites. At the same time, loaders and haul trucks are forecasted to expand at a 5.17% CAGR through 2031. Underground equipment trails as reserves in deep-level South African gold mines deplete, yet electrified loaders reduce heat load and improve ventilation efficiency, moderating the decline in demand.
Crushing, screening, and mineral-processing lines serve both open-pit and infrastructure pipelines, where quarry aggregates underpin rail and road corridors. Local beneficiation mandates in Nigeria and Algeria stimulate purchases of flotation cells and thickeners, reshaping procurement toward processing circuits. Drills and breakers benefit from rare-earth exploration. At the same time, loaders and haul trucks lead the substitution cycle toward higher-capacity, lower-emission fleets, driving the African mining equipment market forward.


By Automation Level: Autonomous Uptake Accelerates
Manual fleets accounted for 66.73% of the African mining equipment market in 2025, as labor costs remain comparatively low and connectivity gaps persist. Nevertheless, fully autonomous systems are projected to post a 18.38% CAGR to 2031 as mines prioritize safety in deep-level stopes. Retrofits are gaining popularity, allowing operators to amortize the cost of existing trucks while capturing collision-avoidance and productivity benefits. Chinese OEMs undercut Western rivals with lower-priced autonomy kits, widening access for mid-tier miners.
Semi-autonomous solutions, including tele-operated drills, bridge capability gaps in operations where connectivity is intermittent but improving through satellite services. Regulatory frameworks now require risk assessments, yet approvals are accelerating as authorities observe lower accident rates in pilot projects. This policy evolution supports the long-term transition toward autonomy across the African mining equipment market.
By Powertrain Type: Zero-Emission Fleets Gain Momentum
Internal-combustion units still dominate, accounting for 72.45% of the African mining equipment market in 2025, because diesel supply chains are entrenched and acquisition costs remain lower. However, battery-electric vehicles are climbing at an 8.55% CAGR amid tightening emissions standards and attractive total cost of ownership metrics when diesel prices top USD 1.20/liter. Eskom’s off-peak tariffs below ZAR 0.80/kWh (~USD 0.043/kWh) improve the economics of charging, encouraging fleet trials that can expand into larger orders.
Hybrid platforms remain niche, mainly on steep-gradient haul roads where regenerative braking yields fuel savings. Nevertheless, escalating carbon pricing across the European Union and certain African-bound trade routes could accelerate hybrid interest among exporters seeking to target low-carbon supply chains. As renewable generation capacity grows, electrified powertrains are gaining strategic importance for stakeholders in the African mining equipment market.
By Power Output: Mid-Range Machines Balance Productivity and Agility
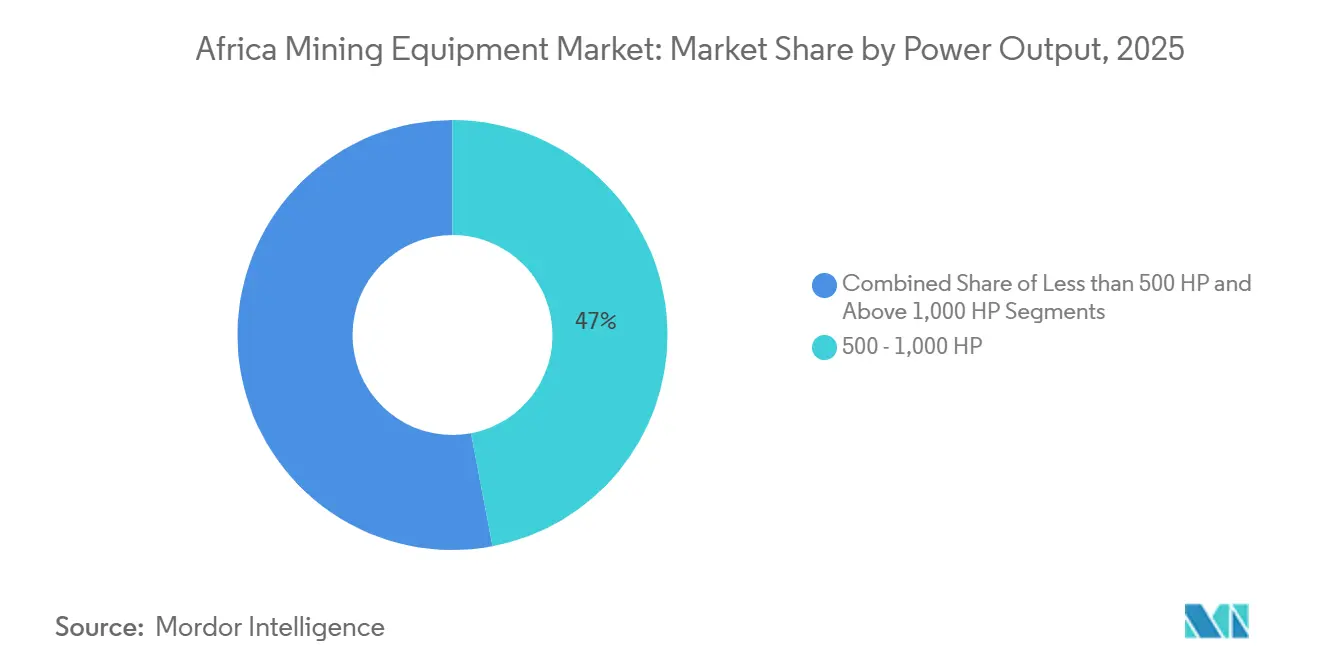
Equipment in the 500–1,000 HP bracket accounted for 47.02% of the African mining equipment market in 2025 because mid-range excavators and wheel loaders best match the pit sizes common to gold, copper, and iron ore operations. Sub-500 HP products rise at 6.12% as small-scale miners formalize and upgrade manual processes. Nigerian tax holidays for compact equipment accelerate purchases of 50-tonne excavators and 6-tonne loaders in new bauxite and gold districts.
Ultra-class units above 1,000 HP remain essential in mega-projects where economies of scale trump acquisition cost; Guinea’s Simandou imported four WA1200-6 loaders, each exceeding 4 MW of installed power, highlighting continued appetite for high-horsepower equipment. Battery-integration prospects are strongest in mid-range classes where pack sizes support an eight-hour shift without sacrificing payload, bolstering electrification momentum in the African mining equipment market.
By Application: Metals Mining Remains the Anchor
Metal mining accounted for 53.71% of the African mining equipment market in 2025, anchored by platinum in South Africa and copper-cobalt output in the DRC. Mineral-mining applications, including rare earths and phosphates, are projected to rise 5.63% through 2031 as governments court investment in energy-transition materials. Coal remains strategically important for South African power security, but emissions policies nudge operators toward zero-emission haulage and in-pit crushing solutions.
Mineral explorers demand modular processing kits that scale with evolving resource definitions. Pilot plants at Phalaborwa and Longonjo demonstrate small-footprint crushers and separators, while metal majors pursue autonomous truck fleets to raise productivity and cut labor exposure. These distinct technology pathways, together, broaden the opportunity set for OEMs active in the African mining equipment market.
Geography Analysis
South Africa’s 39.66% share reflects mature support infrastructure and a deep installed base. However, its growth rate remains below the regional average due to challenges such as the impending closure of older gold shafts and the impact of the global energy transition on coal assets. Despite these hurdles, tax incentives for adopting battery-electric loaders in platinum mining operations are encouraging replacement activities. Additionally, the increasing use of drone surveillance to address illegal mining activities is driving demand for compact screening equipment, reflecting a shift toward innovative solutions in the sector.
The DRC posts the fastest 5.68% CAGR to 2031, propelled by iron-ore and copper-belt expansions. Rail links funded by the U.S. Development Finance Corporation minimize logistics costs, spurring orders for rail-loading systems and conveyor packages. Challenges such as periodic component shortages and royalties on strategic minerals persist; these are being mitigated by the involvement of investors with a high tolerance for risk and access to integrated supply chains, thereby ensuring steady market progress.
Other countries in the region, including Nigeria, Algeria, Libya, and several others, are also contributing to the overall demand. In Nigeria, new policies aimed at promoting local processing are driving the establishment of large-scale industrial facilities, thereby generating significant demand for mining equipment, such as crushing and grinding systems. Algeria’s updated Mining Code, which now allows greater foreign ownership, has sparked interest in collaborative ventures, particularly in its iron ore fields. Libya, while facing security challenges, holds untapped potential for future growth. Meanwhile, countries like Botswana, Namibia, and Zambia are actively exploring the use of battery-electric loaders, showcasing a commitment to innovation and sustainability across a geographically diverse market.
Competitive Landscape
Competitive dynamics are characterized by moderate concentration, with the top OEMs commanding a significant share of market revenue. Caterpillar, Komatsu, Liebherr, Sandvik, and Epiroc strengthen their positions by offering advanced digital services, autonomous solutions, and component-exchange programs. Meanwhile, Chinese entrants like XCMG and Sany are gaining traction in Africa by adopting competitive pricing strategies and building extensive dealer networks. XCMG has recently formed a strategic alliance to enhance spare-parts availability in South Africa, while Sany is making a strong statement with its investment in infrastructure, signaling its long-term commitment to the region.
Localization has emerged as a key strategy for market players. Barloworld’s large-scale rebuild hub in Boksburg is reconditioning thousands of components annually, significantly reducing lead times and helping clients mitigate currency-related challenges. Similarly, Mantrac is making substantial investments to establish a new component-rebuild center, further strengthening Caterpillar’s aftermarket presence. Epiroc’s acquisition of a domestic parts supplier ensures a reliable channel for genuine parts, addressing the growing issue of counterfeit products that impact OEM revenues.
Technological collaborations are transforming the competitive landscape. Avanti’s connectivity solutions are enabling advanced, data-driven maintenance platforms, while Komatsu’s SmartCare system is integrating cutting-edge communication technologies to provide real-time equipment health monitoring. Bell Equipment is expanding its product offerings by introducing a new grader line to target quarry customers whom larger global players have underserved. Metso has also taken steps to expand its footprint in the region by opening a new hub to support mineral-processing plants across sub-Saharan Africa, reinforcing its commitment to growth and intensifying competition in the African mining equipment market.
Africa Mining Equipment Industry Leaders
-
Caterpillar Inc.
-
Komatsu Ltd.
-
Liebherr-International AG
-
Sandvik AB
-
Epiroc AB
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- April 2026: Cummins introduced its first battery energy storage system for hybrid microgrids at African mining sites, aiming to reduce diesel generator runtime and emissions.
- February 2026: Weir completed a 1,600-square-meter expansion of its Alrode plant in Gauteng. The expansion added two 57-ton gantry cranes to support the assembly of large comminution equipment.
- January 2026: FAM Minerals & Mining, a BEUMER Group company, opened an office in Johannesburg to serve bulk-material-handling clients across Southern Africa.


Africa Mining Equipment Market Report Scope
The Africa Mining Equipment market is segmented by equipment type, automation level, powertrain type, power output, application, and country. By Equipment Type, the market is segmented into Surface Mining Equipment, Underground Mining Equipment, Mineral Processing Equipment, Drills and Breakers, Crushing, Pulverizing, and Screening Equipment, and Loaders and Dozers. By Automation Level, the market is segmented into Manual, Semi-Autonomous, and Fully Autonomous Equipment. By Powertrain Type, the market is segmented into Internal-Combustion Engine (ICE), Battery-Electric Vehicle (BEV), and Hybrid Vehicle. By Power Output, the market is segmented into Less than 500 HP, 500 to 1,000 HP, and above 1,000 HP. By Application, the market is segmented into Metal Mining, Mineral Mining, and Coal Mining. By Country, the market is segmented into South Africa, Nigeria, Algeria, the Democratic Republic of Congo, Libya, and the rest of Africa. Market forecasts are provided in terms of Value (USD) and Volume (Units).
| Surface Mining Equipment |
| Underground Mining Equipment |
| Mineral Processing Equipment |
| Drills and Breakers |
| Crushing, Pulverizing and Screening |
| Loaders and Haul Trucks |
| Manual Equipment |
| Semi-Autonomous Equipment |
| Fully Autonomous Equipment |
| Internal-Combustion Engine Vehicles |
| Battery-Electric Vehicles |
| Hybrid Vehicles |
| Less than 500 HP |
| 500 – 1,000 HP |
| Above 1,000 HP |
| Metal Mining |
| Mineral Mining |
| Coal Mining |
| South Africa |
| Nigeria |
| Algeria |
| Democratic Republic of Congo (DRC) |
| Libya |
| Rest of Africa |
| By Equipment Type | Surface Mining Equipment |
| Underground Mining Equipment | |
| Mineral Processing Equipment | |
| Drills and Breakers | |
| Crushing, Pulverizing and Screening | |
| Loaders and Haul Trucks | |
| By Automation Level | Manual Equipment |
| Semi-Autonomous Equipment | |
| Fully Autonomous Equipment | |
| By Powertrain Type | Internal-Combustion Engine Vehicles |
| Battery-Electric Vehicles | |
| Hybrid Vehicles | |
| By Power Output | Less than 500 HP |
| 500 – 1,000 HP | |
| Above 1,000 HP | |
| By Application | Metal Mining |
| Mineral Mining | |
| Coal Mining | |
| By Country | South Africa |
| Nigeria | |
| Algeria | |
| Democratic Republic of Congo (DRC) | |
| Libya | |
| Rest of Africa |


Key Questions Answered in the Report
What is the current value of the Africa mining equipment market?
The Africa mining equipment market size was valued at USD 3.13 billion in 2025 and is projected to expand from USD 3.26 billion in 2026 to USD 4.02 billion by 2031, registering a CAGR of 4.24% between 2026 and 2031.
Which segment leads spending in the Africa mining equipment market?
Surface-mining machinery holds the top position with 46.65% of 2025 revenue.
Where is demand for fully autonomous mining equipment growing fastest?
South Africa’s deep-level gold and platinum operations drive the highest adoption, supporting an 18.38% CAGR for fully autonomous systems through 2031.
Which country offers the strongest growth outlook?
The DRC is projected to expand at 5.68% through 2031, driven by large iron-ore and copper-belt projects supported by new rail corridors.
Page last updated on:



