
South Africa Mineral Processing Equipment Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
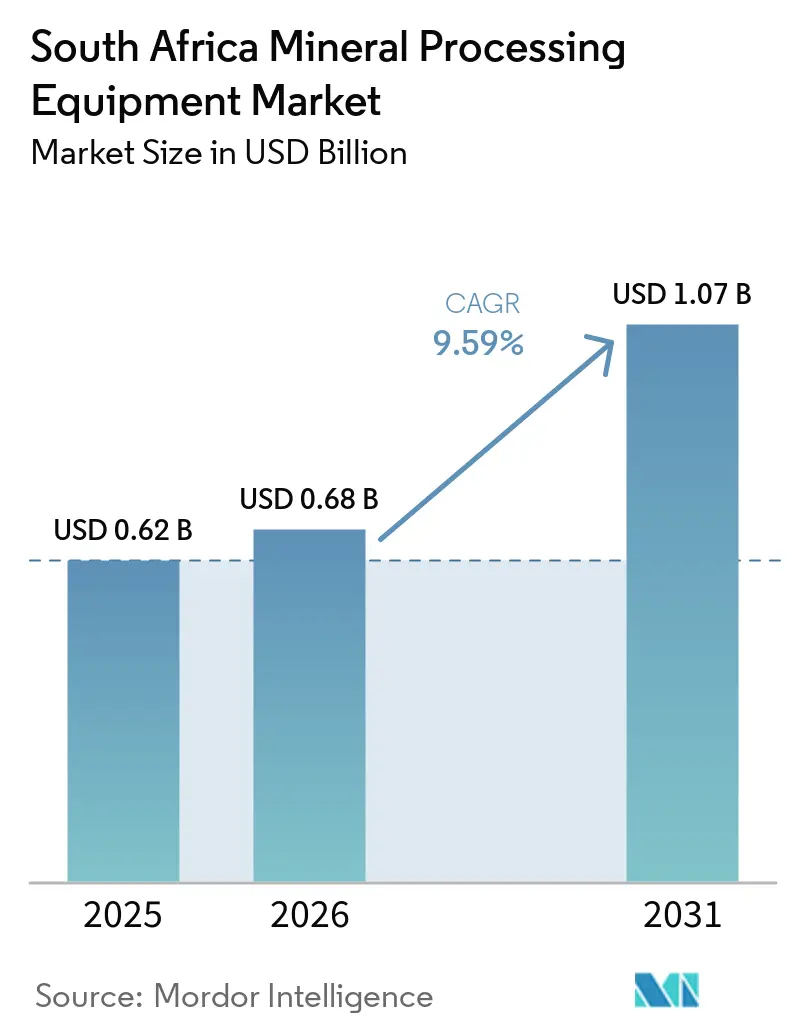
| Base Year Market Size (2025) | USD 0.62 Billion |
| Market Size (2026) | USD 0.68 Billion |
| Market Size (2031) | USD 1.07 Billion |
| Growth Rate (2026 - 2031) | 9.59 % |
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
South Africa Mineral Processing Equipment Market Analysis by 麻豆视频
The South Africa mineral processing equipment market size was valued at USD 0.62 billion in 2025 and is expected to increase from USD 0.68 billion in 2026 to reach USD 1.07 billion by 2031, growing at a CAGR of 9.59% over 2026-2031. The country’s long-term push to beneficiate battery metals, the pickup in rail-port fluidity, and stricter energy-efficiency rules are reshaping procurement priorities. Equipment suppliers are responding with modular plants that slash installation lead times, automation packages that mitigate a widening maintenance skills gap, and hybrid-power platforms that soften exposure to Eskom tariff swings. Digital-twin diagnostics, lifecycle service contracts, and local-content fabrication commitments have become the main competitive levers as miners weigh total cost of ownership against escalating compliance requirements. The market remains moderately fragmented, giving local fabricators room to win niche orders while large multinationals protect installed bases through aftermarket support and upgrade programs.
Key Report Takeaways
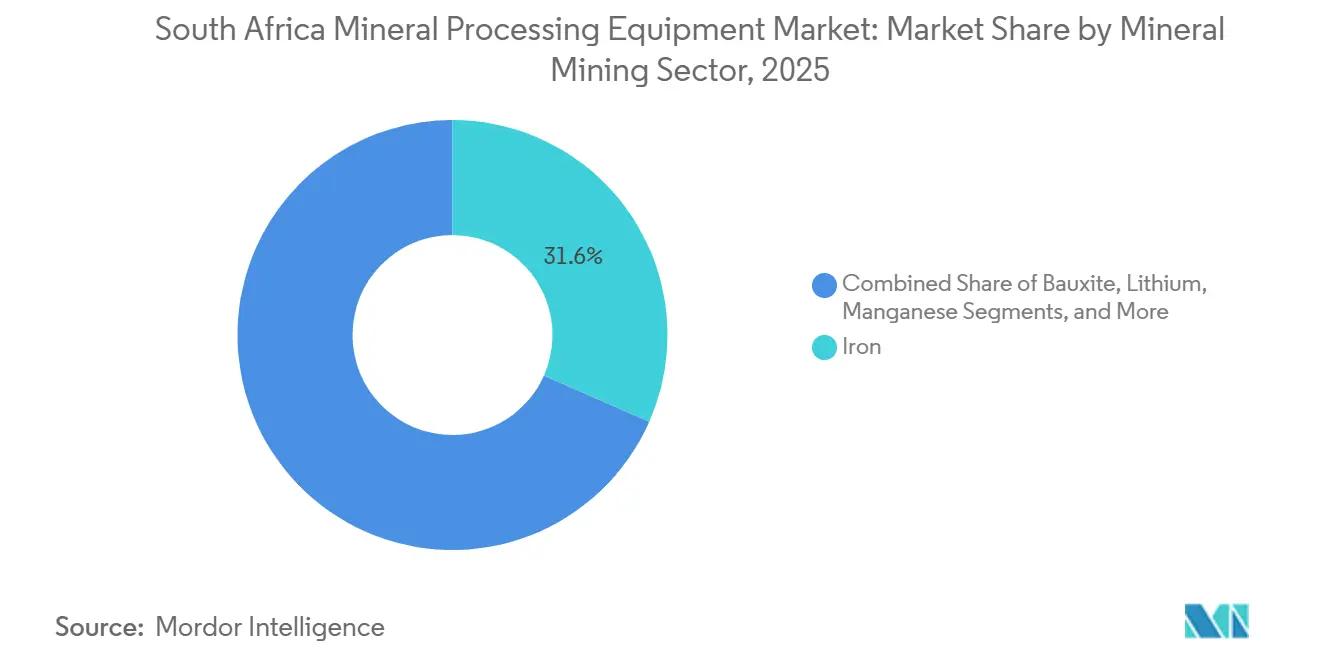
- By mineral mining sector, iron led with 31.62% of the South African mineral processing equipment market in 2025, whereas lithium processing equipment is projected to expand at an 11.15% CAGR through 2031.
- By equipment type, crushers commanded 30.34% of the South African mineral processing equipment market in 2025, while flotation cells are forecast to grow at the highest rate, with a 10.79% CAGR to 2031.
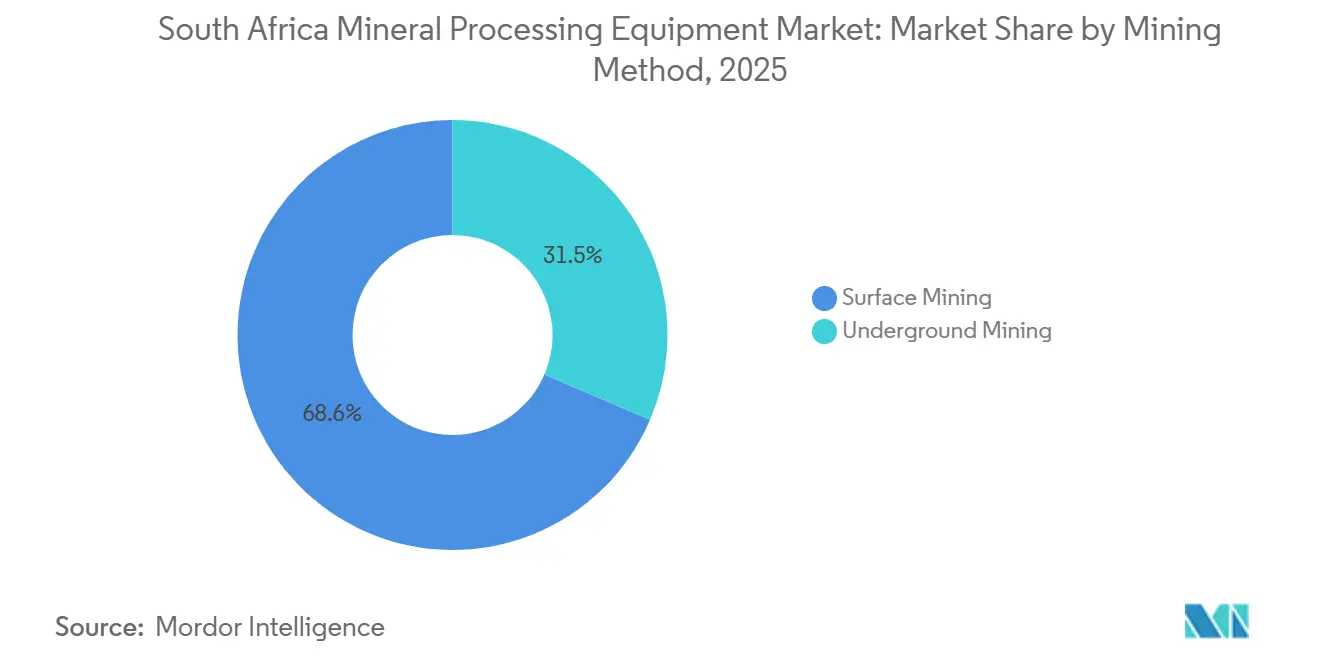
- By mining method, surface operations accounted for 68.55% of the South African mineral processing equipment market in 2025, while underground units are set to grow at an 11.59% CAGR through 2031.
- By automation level, manual systems still accounted for 55.35% of the South African mineral processing equipment market in 2025, but fully automated equipment is growing at a 16.73% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Future direction is shaped by developments occurring across multiple countries and regions, with South africa contributing to the overall trajectory. The outlook on worldwide mineral processing equipment market reflects how these are expected to evolve collectively.
South Africa Mineral Processing Equipment Market Trends and Insights
Drivers Impact Analysis*
| Driver | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increasing Mineral Output of Critical Metals | +2.1% | Northern Cape, Limpopo | Medium term (2-4 years) |
| Government Incentives and Beneficiation Mandates | +1.8% | National | Long term (≥ 4 years) |
| Digitization and Plant Automation Adoption | +1.4% | National | Medium term (2-4 years) |
| ESG-Driven Demand for Energy-Efficient Equipment | +1.2% | National | Long term (≥ 4 years) |
| Rail-Port De-Bottlenecking Projects | +0.9% | Coastal provinces, Northern Cape corridors | Short term (≤ 2 years) |
| Modular Plants for Junior Miners | +0.7% | Regional | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Increasing Mineral Output of Critical Metals
Rising demand for battery-grade inputs is pulling new concentrator capital toward lithium, manganese, and platinum group metals. Fresh offtake contracts with cathode and anode manufacturers translate into firm orders for spiral concentrators, fine-grinding mills, and high-selectivity flotation cells. Government beneficiation clauses further lock in local purchase commitments, lifting visibility for domestic OEMs. Junior explorers moving from drill-core to pilot-plant scale are opting for containerized circuits to preserve cash and meet tight construction windows. As feasibility studies mature, a multi-year ordering cycle for modular crushing, dense-media, and calcination lines is building.
Government Incentives and Beneficiation Mandates
The Critical Minerals Strategy ties mining-right approvals to in-country processing, shifting capital away from run-of-mine exports toward staged upgrades and specialty chemical plants[1]Tina Tong, Holly Chant, Jessica Long, Fastmarkets, "South Africa’s new critical minerals policy draws critical eye of buyers, miners," Fastmarkets, www.fastmarkets.com. New license applications must detail local fabrication percentages, workforce skilling plans, and energy-efficiency metrics. These thresholds favor suppliers capable of welding, machining, and certifying pressure vessels in South Africa. Parallel tax credits on plant automation investments further narrow the cost gap between conventional and smart equipment, nudging buyers toward digitally integrated flowsheets.
Digitization and Plant Automation Adoption
Unplanned downtime linked to lubrication errors and manual process control is pushing mines toward sensor-laden equipment that self-calibrates and feeds real-time data into central command rooms. Autonomous raise-borers, driverless trucks, and hybrid mobile crushers are rolling out alongside virtual-reality operator training that cuts onboarding time. Multinationals bundle these offerings in outcome-based service contracts, guaranteeing throughput or recovery against monthly fees. Uptake is strongest where mines face acute labor shortages and where union negotiations encourage relocation of workers to control-room roles.
ESG-Driven Demand for Energy-Efficient Equipment
Mandatory carbon budgets require operators to show annual improvements in energy intensity. Hybrid-drive crushers and high-pressure grinding rolls lower both kilowatt-hours per tonne and Scope 1 diesel emissions. Plant designers integrate variable-speed motors and advanced ore-tracking software to synchronize comminution power draw with ore hardness. Boards now include energy-saving guarantees in tender specs, placing a premium on proven low-energy gear backed by life-cycle audits. Financial institutions increasingly price debt on adherence to these metrics, reinforcing demand.
Restraints Impact Analysis*
| Restraint | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Unreliable Power Supply and High Tariffs | -2.2% | National | Short term (≤ 2 years) |
| Stringent Environmental Regulations | -1.5% | National | Long term (≥ 4 years) |
| Low-Priced Chinese OEM Competition | -1.1% | National | Medium term (2-4 years) |
| Scarce Automation and Controls Talent | -0.8% | National | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Unreliable Power Supply and High Tariffs
Industrial tariffs above historical averages strain cash flow for energy-intensive comminution. Although recent quarters saw fewer rolling blackouts, grid reserve margins remain razor-thin. Mine hedges by installing solar arrays, but variable generation complicates mill torque stability, prompting the procurement of hybrid diesel-electric mobiles and variable-speed drives. Higher upfront capital requirements slow investment decisions and lengthen payback periods, thereby dampening near-term equipment demand [2]“Industrial Tariff Schedule 2025-2026,” Eskom, eskom.co.za .
Stringent Environmental Regulations
Extended environmental-impact reviews and larger rehabilitation bonds inflate carrying costs. Tougher tailings and water-reuse standards add thickener, clarifier, and membrane-plant line items to capex budgets. Community consultations delay approvals, creating scheduling risks that disfavor large, immobile mills. Modular, redeployable equipment is therefore preferred, yet the extra mobility features raise sticker prices, affecting affordability for smaller operators.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Mineral Mining Sector: Battery Metals Realign Procurement
Iron ore processing equipment accounted for the largest share, 31.62%, of the South African mineral processing equipment market in 2025, as bulk operations around Sishen and Kolomela continued to expand. Lithium installations are forecast to grow at an 11.15% CAGR in battery-supply-chain investments. This differential growth profile encourages OEMs to diversify from mature ferrous circuits into high-purity lithium flowsheets. Local fabricators scale spiral concentrators and dense-media separators to meet new brine-conversion specs, while international brands position fine-grinding mills that preserve lithium recoveries. Regional training centers now include modules on handling reactive lithium ores, reflecting the segment’s gravitational pull on skills development.
Platinum group metals, gold, manganese, and coal round out the remaining demand but exhibit more stable trajectories. Project financiers favor sectors with offtake certainty, elevating battery metals in credit committees. Iron-ore players, meanwhile, guard processing budgets until rail fluidity fully improves, moderating near-term appetite for expansion. For niche minerals such as vanadium and rare earths, the pilot-scale kit dominates orders, offering fabricators entry points into bespoke process routes. Suppliers that cross-pollinate lessons learned in lithium with those in PGM concentrate upgrading stand to enhance win probabilities as policy steers miners toward beneficiation compliance.


By Equipment Type: Sensors and Cells Move to Center Stage
Crushers accounted for the largest share, 30.34%, of the South African mineral processing equipment market in 2025, reflecting the enduring requirement for primary fragmentation in open-pit circuits. Flotation cells, however, are expanding at a 10.79% CAGR as concentrators chase incremental recovery gains from finely disseminated orebodies. As pneumatic cell designs mature, buyers evaluate air-dispersion efficiencies and maintenance overheads rather than nameplate volumes alone. Sensor integration within cells unlocks reagent optimization, further justifying investment in upgrades. High-frequency screens paired with advanced cells reduce circulating loads, shrinking mill footprints.
Feeders, conveyors, and pumps piggy-back on crusher and cell orders, but the fastest innovations surface in control systems that harmonize these subsystems. Variable-speed conveyors stabilize downstream flow, allowing mills to run closer to grind-limit thresholds without spillage. Digital-ready gear aligns with miners’ ESG narratives by capturing real-time energy-use data. Suppliers bundle such features with subscription-based performance analytics, replacing transactional parts sales with recurring revenue. Lower-cost entrants mimic hardware specs, yet limited software depth reduces competitive threat, preserving margins for incumbents at the premium end.
By Mining Method: Deep-Level Automation Gains Ground
Surface mines retained a dominant 68.55% of the South African mineral processing equipment market in 2025, supported by shallow iron and manganese pits. Underground procurement, growing at 11.59% CAGR, benefits from shaft-deepening projects in the Bushveld Complex. Heat, humidity, and confined haulage layouts prompt the adoption of in-shaft crushers and energy-efficient hoisting solutions. Raise-boring automation shortens development cycles, freeing capital for early plant spend. Suppliers integrate real-time rock-mechanics monitoring, elevating safety credentials and unlocking insurance premium reductions for operators.
Open-pit operators gravitate toward modular mobiles that shift with advancing faces, alleviating trucking distances. Hybrid power plants extend working hours when grid cuts strike, stabilizing throughput. In underground settings, autonomous loaders and tele-operated drills mitigate labor availability risks while boosting productivity in high-stress zones. The contrasting priorities of ventilation energy, surface dust abatement, and slope-stability monitoring shape divergent spec sheets, forcing OEMs to segment product roadmaps by mining method. Training regimes follow suit, with simulation pods mirroring either pit control cabins or underground chambers.
By Automation Level: Software Value Surpasses Steel Weight
Manual equipment still formed 55.35% of the South African mineral processing equipment market in 2025, a legacy of abundant artisan labor. Fully automated units, advancing at a 16.73% CAGR, increasingly embed condition-monitoring sensors that trigger predictive maintenance. Millisecond-level data feeds into cloud dashboards where optimization algorithms tweak load, speed, and reagent dosage. Miners value these platforms for reducing downtime and supporting carbon footprint reporting. As license fees displace hardware mark-ups, vendors rethink revenue models toward software-as-a-service pricing.
Semi-automated systems act as a bridge for sites lacking fiber connectivity or executive buy-in for full autonomy. Yet once operators experience improvements in uptime, the migration curve steepens toward fully autonomous fleets. Virtual-reality simulators accelerate operator acceptability, closing behavioral gaps. Chinese entrants undercut on metal costs yet lag in analytics, limiting uptake among established producers that prioritize process-guarantee clauses. In parallel, universities roll out coding-heavy curricula to address a scarce pool of control-systems talent, but graduation pipelines lag procurement cycles, thereby sustaining demand for turnkey autonomy.
Geography Analysis
Limpopo and North West dominate the South African mineral processing equipment market via platinum group metal production. High-grade orebodies and deepening shafts amplify orders for high-pressure grinding rolls and in-line paste-backfill systems to manage rock stresses. Lithium discoveries in Limpopo enrich the province’s equipment mix, blending hard-rock crushing with hydrometallurgical reactors. Local fabrication hubs benefit from mandated domestic-content ratios, tightening regional linkages between mine sites and industrial parks. Ongoing community consultations influence equipment designs that minimize dust and noise footprints.
The Northern Cape anchors iron-ore and manganese processing. As rail access improves, modular crushing trains follow pit expansions along the Kalahari belt. Ports in the Western and Eastern Cape plan berth upgrades to accommodate higher tonnage, spurring conveyor and ship-loader orders that ripple back through inland mines. Mpumalanga remains the coal heartland, yet carbon-reduction scrutiny nudges processors toward dry beneficiation and low-energy screening. Gauteng evolves as the service epicenter--housing spare-parts depots, test-cells, and automation labs--shortening turnaround times for field failures.
KwaZulu-Natal’s Richards Bay corridor provides strategic export optionality for multiple commodities, creating latent demand for bulk-material-handling components compatible with varying moisture contents. The Free State hosts aging gold shafts where refurbishment of carbon-in-leach circuits and fine-grind mills maintains baseline demand. The Western Cape, despite minimal mining, attracts technology conferences and pilot-scale demo plants owing to proximity to universities and port logistics. Provincial governments coordinate training incentives, aligning vocational programs with OEM apprenticeship needs, and thereby anchoring human-capital pipelines that support equipment uptake.
Analysis of the mineral processing equipment market by 麻豆视频 is supported by country-level insights for Egypt, Morocco, Australia, China, Canada, Germany, France, Spain, and South Korea, wherein local market conditions keep varying from one country to another.
Competitive Landscape
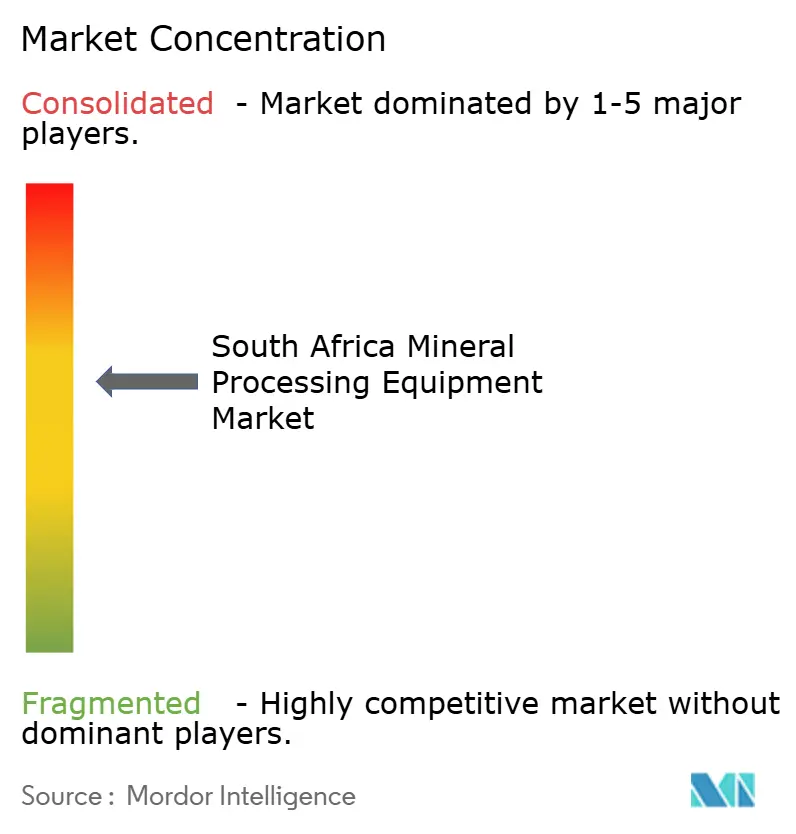
The supply side of the South African mineral processing equipment market features a mix of global original equipment manufacturers and specialized local fabricators, none of which holds a controlling stake, resulting in moderate concentration. Multinationals leverage installed bases to lock in long-term service agreements that assure parts revenue. Pricing differentials emerge around software functionality rather than steel tonnage, re-shaping how buyers evaluate bids. Lifecycle contracts bundle uptime guarantees, creating barriers to entry for latecomers lacking extensive support networks.
Local firms carve space in modular plant fabrication for junior miners, winning on agility and site-specific customization. Their ability to pre-assemble units in Gauteng workshops and commission on remote pads within days counters the lead-time advantage of containerized imports. Collaboration with universities on metallurgy and 3-D-printed wear components enhances innovation capacity. Meanwhile, Chinese brands are expanding their warehouse footprints near Richards Bay, pursuing greenfield projects at sharp pricing, but still face skepticism over warranty length and metallurgical tolerances.
Strategic moves center on acquisitions that plug digital gaps. A notable deal integrated virtual-reality simulators into autonomous fleet-management suites, shrinking operator training windows. Another OEM doubled Gauteng production floor area, adding high-capacity cranes to handle fully assembled roller-bearing crushers. Suppliers also forge partnerships with telecom providers to deploy private LTE networks underground, ensuring autonomous drills maintain latency-free links. Collectively, these initiatives reflect a pivot from selling individual machines toward offering data-rich productivity ecosystems.
South Africa Mineral Processing Equipment Industry Leaders
-
Multotec
-
FLSmidth A/S
-
Metso Outotec
-
Sandvik AB
-
The Weir Group PLC
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- June 2026: Sandvik debuted its CH662 cone crushers at a platinum mining operation in South Africa’s Limpopo province. The company deployed the first CH662 cone crushers for a platinum mining project in the region.
- February 2026: Weir expanded its Alrode facility in Gauteng, South Africa, adding 1,600 m? of production space, two 57-ton gantry cranes, and two assembly stations for ENDURON? Elite banana screens.
- January 2026: FAM Minerals & Mining, part of a global conveyor group, opened an office in Johannesburg to support bulk-material-handling installations across Southern Africa.


South Africa Mineral Processing Equipment Market Report Scope
The South African Mineral Processing Equipment market is segmented by mineral mining sector, equipment type, mining method, and automation level. By Mineral Mining Sector, the market is segmented into Bauxite, Iron, Lithium, Platinum Group Metals, Manganese, Coal, Gold, Copper, and Other Minerals. By Equipment Type, the market is segmented into Crushers, Feeders, Conveyors, Drills and Breakers, Grinding Mills, Screening Equipment, Cyclones and Separators, Flotation Cells, Pumps and Valves, Automation and Control, and Others. By Mining Method, the market is segmented into Surface Mining and Underground Mining. By Automation Level, the market is segmented into Manual, Semi-Autonomous, and Fully-Autonomous. Market forecasts are provided in terms of Value (USD) and Volume (Units).
| Bauxite |
| Iron |
| Lithium |
| Platinum Group Metals |
| Manganese |
| Coal |
| Gold |
| Copper |
| Other Minerals |
| Crushers |
| Feeders |
| Conveyors |
| Drills and Breakers |
| Grinding Mills |
| Screening Equipment |
| Cyclones and Separators |
| Flotation Cells |
| Pumps and Valves |
| Automation and Control Systems |
| Others |
| Surface Mining |
| Underground Mining |
| Manual |
| Semi-Automated |
| Fully Automated |
| By Mineral Mining Sector | Bauxite |
| Iron | |
| Lithium | |
| Platinum Group Metals | |
| Manganese | |
| Coal | |
| Gold | |
| Copper | |
| Other Minerals | |
| By Equipment Type | Crushers |
| Feeders | |
| Conveyors | |
| Drills and Breakers | |
| Grinding Mills | |
| Screening Equipment | |
| Cyclones and Separators | |
| Flotation Cells | |
| Pumps and Valves | |
| Automation and Control Systems | |
| Others | |
| By Mining Method | Surface Mining |
| Underground Mining | |
| By Automation Level | Manual |
| Semi-Automated | |
| Fully Automated |


Key Questions Answered in the Report
What is the current market size and growth rate of the South African mineral processing equipment market?
The South Africa mineral processing equipment market size was valued at USD 0.62 billion in 2025 and is expected to increase from USD 0.68 billion in 2026 to reach USD 1.07 billion by 2031, growing at a CAGR of 9.59% over 2026-2031.
Which mineral segment currently drives most equipment orders?
Iron-ore processing gear leads with 31.62% of 2025 demand.
Which equipment type is expected to grow the quickest?
Flotation cells show the highest forecast growth at a 10.79% CAGR through 2031.
Why is full automation adoption accelerating?
Acute maintenance-skills shortages and carbon-reporting pressures push mines toward sensor-rich, self-optimizing machines that expand at a 16.73% CAGR through 2031.
Page last updated on:



