
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 187.78 Billion |
| Market Size (2026) | USD 204.18 Billion |
| Market Size (2031) | USD 310.56 Billion |
| Growth Rate (2026 - 2031) | 8.74 % |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
Asia-Pacific Wellness Tourism Market Analysis by 麻豆视频
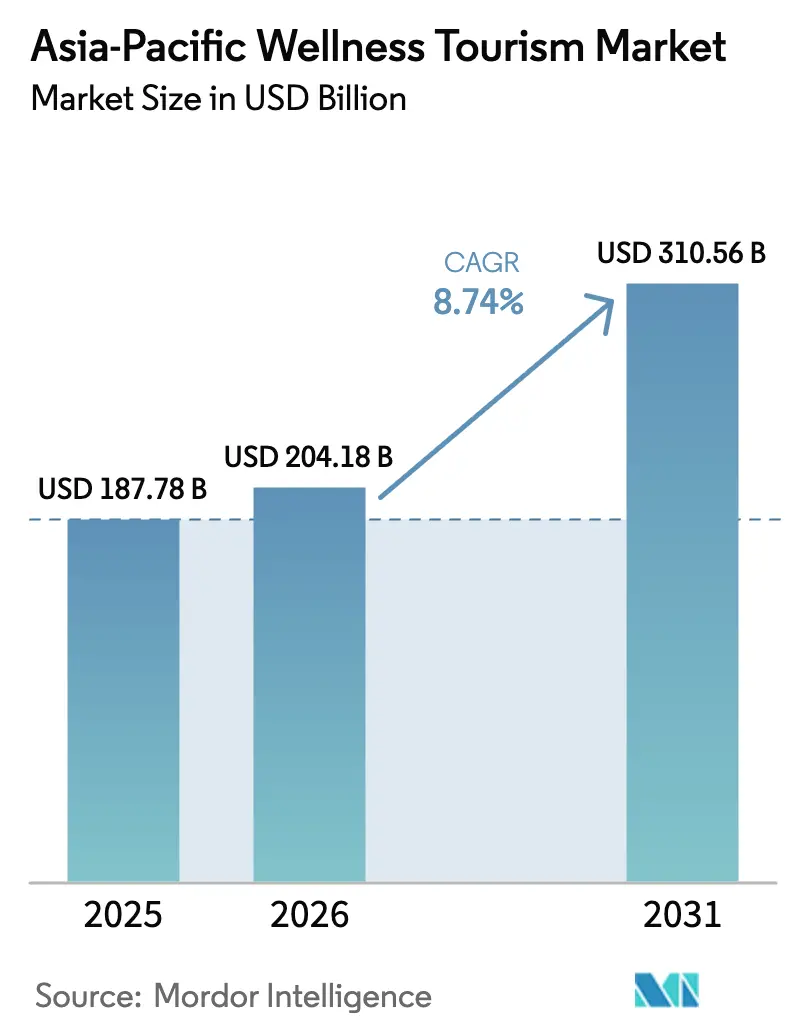
The Asia-Pacific wellness tourism market size was valued at USD 187.78 billion in 2025 and estimated to grow from USD 204.18 billion in 2026 to reach USD 310.56 billion by 2031, at a CAGR of 8.74% during the forecast period (2026-2031). Government-backed integration of traditional medicine, surging disposable incomes among the region’s expanding middle class, and sustained post-pandemic prioritization of preventive health continue to energize demand for authentic wellness experiences that combine cultural heritage with measurable outcomes[1]Global Wellness Institute, “Global Wellness Economy Monitor 2024,” globalwellnessinstitute.org. . China currently underpins regional performance through a 37.28% Asia-Pacific wellness tourism market share in 2024, yet India’s 11.82% forecast CAGR points to a more geographically balanced growth trajectory during the outlook period. Secondary wellness travel, where wellness activities augment a broader holiday, remains the dominant user behavior, but primary wellness travel is registering stronger expansion as travelers allocate entire trips to transformative health retreats, thereby lifting yields for operators focused on curated long-stay programs. Supply-side fragmentation keeps competitive intensity low; the top five brands command just 25.9% of regional revenue, leaving substantial white-space for specialized retreat developers, eco-lodge owners, and purpose-built medi-wellness facilities that can scale quality capacity faster than incumbents encumbered by standardized hotel operating models.
Key Report Takeaways
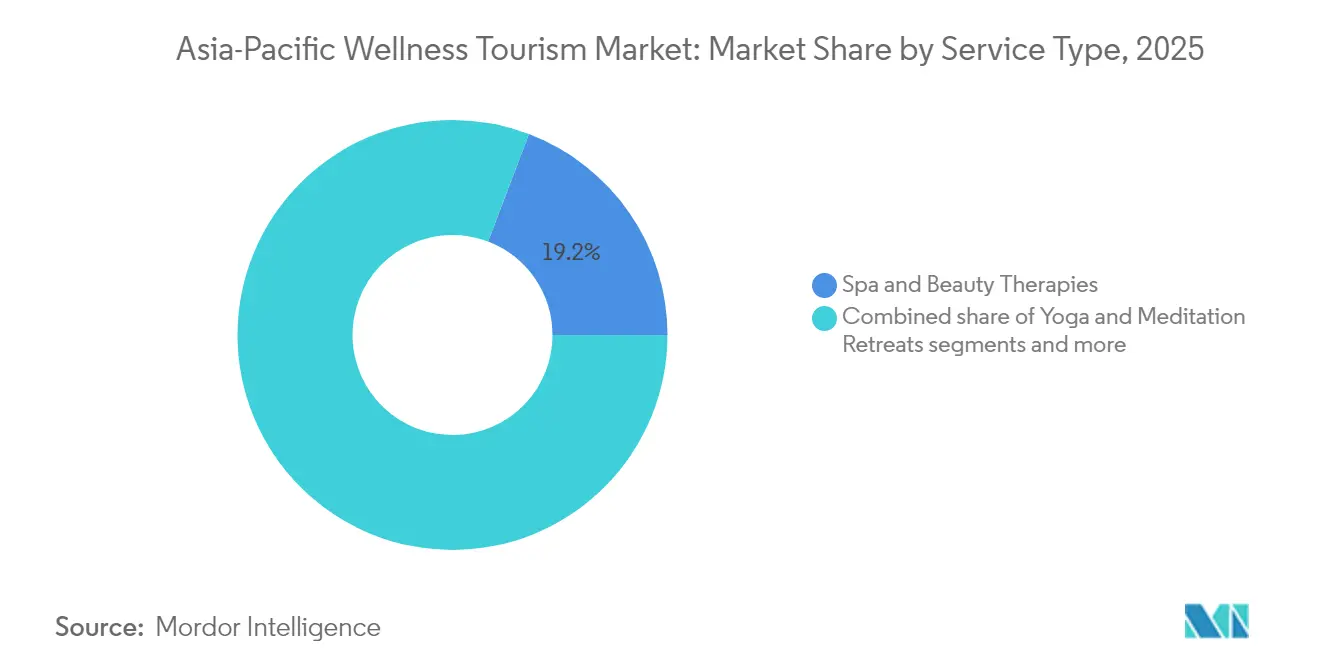
- By service type, spa and beauty therapies led with 19.21% of the Asia-Pacific wellness tourism market share in 2025, while digital-detox escapes are projected to grow at a 11.64% CAGR through 2031.
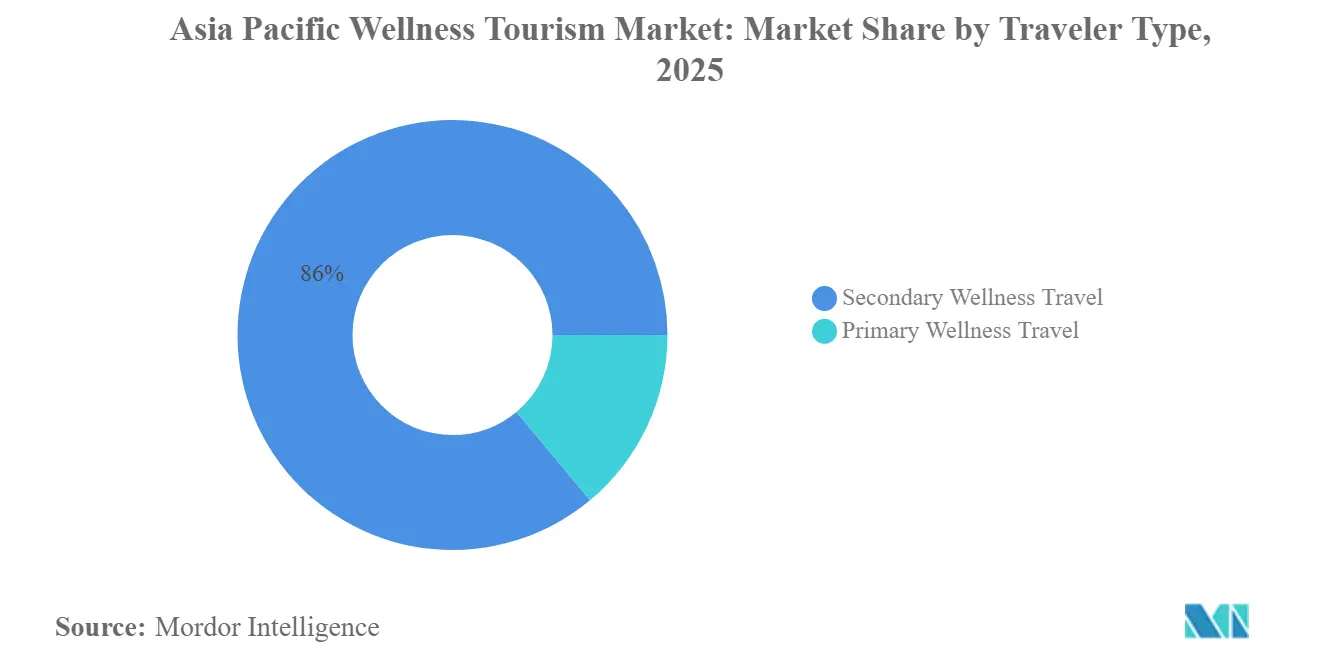
- By traveler type, secondary wellness travel accounted for 86.04% of the Asia-Pacific wellness tourism market size in 2025; primary wellness travel holds the highest projected CAGR at 9.83% for 2026-2031.
- By accommodation type, wellness hotels captured 31.17% of the Asia-Pacific wellness tourism market size in 2025, whereas eco-wellness lodges are forecast to advance at a 12.58% CAGR to 2031.
- By geography, China dominated with a 36.78% Asia-Pacific wellness tourism market share in 2025, while India is positioned as the fastest-growing market at 11.14% CAGR over the forecast horizon.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Asia-Pacific Wellness Tourism Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising middle-class disposable income & intra-regional air-connectivity boom | +2.1% | China, India, Southeast Asia core markets | Medium term (2-4 years) |
| Post-pandemic health consciousness accelerating preventive-care travel | +1.8% | Global, with highest impact in APAC urban centers | Short term (≤ 2 years) |
| Government promotion of AYUSH, TCM & J-Wellness creating demand pull | +1.5% | India, China, Japan with spillover to regional markets | Long term (≥ 4 years) |
| Digital nomad & "work-from-anywhere" visas extending length-of-stay | +0.9% | Thailand, Philippines, Singapore, Malaysia | Medium term (2-4 years) |
| Corporate off-site mental-wellness retreats tackling employee burnout | +0.7% | Urban APAC centers, particularly Japan, South Korea, Singapore | Short term (≤ 2 years) |
| Buy-Now-Pay-Later travel financing unlocking premium retreat affordability | +0.4% | Millennial-heavy markets across APAC | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Rising Middle-Class Disposable Income & Improved Air Links
Surging real wages and favorable demographic profiles have expanded the pool of travelers able to afford dedicated wellness breaks, especially throughout China, India, Indonesia, and Vietnam, where domestic air connectivity has multiplied over the past five years. Low-cost carriers have launched new point-to-point routes that reduce door-to-door travel time and lower fares, enabling weekend wellness escapes that were formerly limited to higher-income groups. Accelerated infrastructure development at secondary airports in Malaysia, Thailand, and the Philippines also lifts access for rural wellness assets, amplifying regional dispersion of visitor flows. Short-haul affordability widens the funnel for first-time wellness travelers, seeding long-term market expansion as repeat visitation boosts average spending on advanced treatments. Destinations able to combine quick flight access with authentic healing modalities consequently achieve stickier demand and favorable RevPAR trends across wellness-centric accommodation. Government incentives that subsidize regional route launches further reinforce the virtuous cycle, suggesting the growth dividend will extend through the medium term.
Post-Pandemic Health Consciousness
The COVID-19 crisis recast health preservation as a lifestyle imperative, vaulting immunity-building, stress reduction, and disease prevention to the heart of travel decision-making. Corporate wellness budgets have swelled as employers seek stress-relief programming to mitigate burnout among remote and hybrid workforces, catalyzing demand for evidence-based retreats that combine diagnostics with coaching. Parallel consumer surveys indicate that affluent Asian millennials value wellness as an “essential” rather than a discretionary purchase, shifting spend from retail to experiential services. Hotels and resorts that swiftly integrated on-site testing, pharmacist consultations, and immunity-focused menus during the reopening phase remain top-of-mind for repeat guests who now expect clinical rigor baked into every itinerary. Marketing narratives grounded in health outcomes rather than pampering experiences resonate widely, creating premium pricing headroom that sustains revenue growth even as traveler cost sensitivity rises elsewhere. The shift appears durable given persistent anxiety over future health shocks, entrenching wellness as a structural, not cyclical, travel driver.
Government Promotion of AYUSH, TCM & J-Wellness
India’s AYUSH visa, launched in 2024, streamlines six- and twelve-month stays for seekers of Ayurveda, yoga, Unani, Siddha, and homeopathy, signaling formal state endorsement of alternative therapies within the inbound tourism strategy. China’s Belt and Road-linked “Health Silk Road” exports Traditional Chinese Medicine clinics across 196 partner countries, elevating global familiarity with TCM and driving inbound flows from patients keen to experience origin-based treatments. Japan positions “J-Wellness” as a core pillar of its Tourism Nation Promotion Basic Plan, integrating forest bathing, onsen therapy, and longevity cuisine into regional destination marketing[2]Ministry of Land, Infrastructure, Transport and Tourism, “Tourism Nation Promotion Basic Plan,” mlit.go.jp.. These policies confer legitimacy on indigenous healing systems, unlock public funding for practitioner training, and subsidize infrastructure that meets modern accreditation standards. Visa facilitation reduces friction for international patients, while bilateral agreements on practitioner licensing spur cross-border referral networks, converting government soft power into measurable visitor arrivals. Over the long term, the alignment between public-sector endorsement and private-sector innovation is expected to elevate service quality, supporting price optimization and margin expansion for certified operators.
Digital-Nomad and Work-From-Anywhere Visas
Thailand, Malaysia, the Philippines, and Indonesia now extend one- to five-year digital-nomad visas that encourage location-independent professionals to combine daily work routines with ongoing wellness regimens. Extended stay permits lengthen the average length of stay well beyond the historical seven-night wellness package, inflating per-visitor revenue across accommodation, treatments, and ancillary spending. Wellness facilities respond by adding co-working zones, high-speed broadband, and flexible scheduling that accommodates mid-day virtual meetings followed by evening detox rituals. Destinations with competitive cost of living and robust digital infrastructure emerge as hubs for “slow wellness,” where guests pursue incremental lifestyle change over multi-month residencies. This paradigm unlocks stable occupancy for low-season months, smoothing revenue volatility and supporting local labor retention. As more APAC governments chase affluent mobile talent, a race to refine nomad-friendly wellness ecosystems may ensue, benefiting early movers with ecosystem depth and brand recognition.
Restraints Impact Analysis of Asia-Pacific Wellness Tourism Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High price sensitivity among Gen-Z & budget travelers | -1.2% | Indonesia, Vietnam, Philippines | Short term (≤ 2 years) |
| Shortage of licensed therapists & wellness practitioners | -0.8% | Thailand, Indonesia, Malaysia | Medium term (2-4 years) |
| Fragmented accreditation & quality-control frameworks | -0.9% | India, Vietnam, Philippines, and emerging wellness destinations | Medium term (2–4 years) |
| Rising insurance exclusions for non-prescribed wellness services | -0.7% | Developed APAC markets such as Japan, South Korea, and Australia | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
High Price Sensitivity Among Gen-Z & Budget Travelers
Younger travelers across emerging Southeast Asian economies crave authentic wellness immersion yet remain constrained by modest discretionary income levels and rising inflation. Social media amplifies aspirational demand, but the luxury positioning of many destination spas places packages out of reach, prompting a proliferation of budget operators that often compromise on therapist quality, safety protocols, and hygiene. Price-focused competition can erode brand equity for incumbents if discounting leads to service dilution, while aggressive cost control measures may limit artisan sourcing, thereby diminishing authenticity. Operators that calibrate tiered product lines offering accessibly priced day passes alongside premium multi-day transformations better capture Gen-Z volumes without cannibalizing upscale segments. Innovative financing models such as buy-now-pay-later partnerships can further democratize access, though margin impacts must be weighed against acquisition gains. Over the short term, price friction is likely to restrain growth in lower-income source markets until rising wages or more efficient operating models narrow the affordability gap.
Shortage of Licensed Therapists & Wellness Practitioners
Thailand projects a deficit of 70,000 professional masseurs and therapists over the next four years, with similar gaps emerging in Indonesia and Malaysia as demand accelerates faster than accredited training programs can expand[3]Nation Thailand, “More Massage Therapists to be Trained,” nationthailand.com. . Bottlenecks in practitioner availability constrain capacity, forcing operators to limit occupancy, extend booking windows, or hire under-qualified staff, risking inconsistent service outcomes that deter repeat visitation. Governments have responded with scholarship programs and accelerated certification pathways, yet quality assurance remains a hurdle where training durations shrink. Specialized modalities such as Panchakarma or TCM acupuncture require multi-year apprenticeships, creating lag times before new supply materializes. Wage inflation intensifies as operators bid for scarce talent, squeezing margins for mid-scale resorts and slimming the viability of community-owned wellness start-ups. Over the medium term, partnerships between public vocational institutes and private retreat chains may ease the crunch, but progress will hinge on harmonizing cross-border licensing to enable mobile practitioner pools.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Asia-Pacific Wellness Tourism Market Segment Analysis
By Service Type:
Digital-Detox Escapes Reshape Premium DemandDigital-detox escapes post a 11.64% CAGR through 2031, eclipsing growth across traditional spa categories even as spa and beauty therapies account for the largest 19.21% revenue slice of the Asia-Pacific wellness tourism market size in 2025. Retreat designers capitalize on employer anxiety over smartphone addiction by mandating tech-free zones, curating nature immersion itineraries, and offering cognitive coaching that restores focus and sleep patterns. Bundling mindfulness workshops with structured silence periods elevates perceived transformation value, helping properties command rates 20%-30% above conventional spa packages while reducing variable cost exposure to imported beauty products. For established resorts, layering digital-detox programs onto existing infrastructure generates incremental yield without extensive capex, encouraging chain-wide rollout despite heterogenous property footprints. Meanwhile, outcome-based modalities such as naturopathy cleanses and longevity monitoring attract health-optimized millennials who value measurable biomarkers over indulgent pampering. Authentic traditional medicine centers in Kerala, Bali, and Chiang Mai integrate centuries-old herbal therapies with clinical diagnostics, drawing repeat guests who track health progression across sequential visits and advocate through social networks, reinforcing organic demand flywheels.


By Traveler Type:
Primary Wellness Travel Gains MomentumSecondary wellness trips and vacations, where wellness services act as add-ons, delivered 86.04% of Asia-Pacific wellness tourism revenue in 2025, yet dedicated primary wellness journeys are accelerating at a 9.83% CAGR to 2031, gradually altering the revenue mix toward higher-spend visitor cohorts. The pivot correlates with rising investor interest in purpose-built medical-wellness facilities that blend diagnostics, IV therapy, and evidence-based nutrition into multi-day protocols tailored to chronic stress, weight management, and hormone balance. Demand elasticity appears favorable; guests enrolling in 7- to 21-day transformative programs spend up to 4.5 times the average secondary wellness ticket, offsetting lower visitor counts during shoulder seasons and reducing marketing cost per booked night. Market education via social media testimonials and third-party physician endorsements accelerates conversion, alleviating initial skepticism among first-time participants wary of medicalized hospitality.
As primary wellness matures, successful operators will differentiate through outcome transparency, publishing aggregated anonymized data on blood markers, sleep quality, and mental health to validate efficacy. Integration with telehealth platforms broadens post-departure support, nurturing brand loyalty that manifests in recurring on-property visits and remote subscription revenue. The shift elevates the strategic importance of therapist-to-guest ratios, cross-disciplinary practitioner teams, and R&D budgets for protocol innovation, reallocating capital away from non-differentiated spa refurbishments toward clinical-grade infrastructure capable of supporting precision wellness.
By Accommodation Type:
Eco-Wellness Lodges Lead Sustainability PivotWellness hotels captured 31.17% of the Asia-Pacific wellness tourism market size in 2025, yet eco-wellness lodges command the fastest 12.58% CAGR through 2031 as travelers equate ecological stewardship with holistic well-being. Biophilic architecture that maximizes daylight, airflow, and natural material palettes enhances circadian alignment, elevating sleep scores and guest satisfaction. Operators adopt regenerative agriculture to supply hyper-local cuisine, linking gut-health programming to terroir narratives that enrich cultural authenticity. Off-grid power systems and closed-loop water cycles reduce operating costs over time, counterbalancing upfront capex and resonating with guests willing to pay premiums for carbon-neutral stays. Boutique retreats leverage small footprints to embed within sensitive ecosystems, mangrove forests, tea plantations, and highland rainforests, where immersive nature exposure amplifies therapeutic outcomes.
The surge in eco-wellness uptake also spawns hybrid models combining medical diagnostics with wilderness immersion; for example, luxury tents outfitted with portable cryotherapy chambers or ECG-enabled sleep pods. Certification frameworks such as EarthCheck or WELL Building Standard differentiate early adopters, granting marketing leverage and facilitating inclusion in curated wellness platforms favored by high-net-worth travelers. Over time, mass adoption of eco-centric design may render conventional urban spa hotels less competitive unless they retrofit rooftop gardens, vertical forests, and improved air-filtration technologies that replicate nature’s benefits in dense settings.
Geography Analysis
China Wellness Tourism Market
China retains primacy within the Asia-Pacific wellness tourism market through a 36.78% revenue share in 2025, buoyed by robust domestic demand and state patronage of Traditional Chinese Medicine integration across public healthcare. Rapid expansion of high-speed rail and diversified tourism zones broadens inland access, yet linguistic and regulatory complexities temper inbound penetration among non-Mandarin speakers. Bilateral treatment pathways that bundle medical checkups in Tier-1 cities with recuperative stays in Hainan’s duty-free enclave aim to rectify dispersion challenges and elongate visitor spend cycles. Outbound Chinese travelers, still rebounding from pandemic-related mobility constraints, are progressively opting for short-haul wellness sojourns to Thailand and Indonesia, transferring service expectations back to domestic providers and catalyzing upgrades in facility aesthetics and program rigor.
India Wellness Tourism Market
India’s 11.14% CAGR outperformance stems from synchronized policy actions, including the AYUSH visa and the National Medical and Wellness Tourism Board, that streamline governance across ministries, standardize accreditation, and amplify brand visibility on global stages. Kerala leverages a 5,000-year Ayurvedic heritage, tropical climate, and English-speaking therapist pool to position itself as the “Eastern Riviera of Rejuvenation,” attracting European retirees and Middle Eastern expatriates seeking long-stay preventive care. Investment in dedicated wellness corridors adjoining international airports accelerates private capital inflows, while public-sector incentives for eco-certifications facilitate market entry for boutique clinics without compromising environmental integrity.
APAC and Oceania Wellness Tourism Market
Southeast Asia benefits from multilayered destination diversity, with Thailand’s wellness economy reaching THB 1,200 billion and registering 5.58% composite annual growth, supported by public funding to train 7,000 additional massage therapists and medical-wellness clusters in Phuket and Chiang Mai. Vietnam’s Decision 2951/QD-BYT charts a blueprint to transform traditional Vietnamese medicine into a tourism export, targeting double-digit visitor expansion by 2030. Indonesia courts wellness nomads through “second-home” visas and curated eco-retreat investment packages that elevate Bali’s peripheral regencies. Japan’s inbound tourism receipts crossed USD 35.05 billion in 2023, and regional governments channel funds into luxury ryokan renovations and forest-bathing networks to decentralize flows beyond Tokyo and Kyoto . Australia’s positioning leans on pristine nature and high clinical standards, yet currency strength and distance temper price competitiveness, prompting cross-promotion with South Pacific wellness cruises to amplify experiential uniqueness.
Regulatory Landscape
Regulation in Asia-Pacific wellness tourism remains multi-layered, covering tourism licensing, health-service oversight, and voluntary awards or accreditation that function as quality signals for inbound travelers. In South Korea, the Ministry of Culture, Sports and Tourism advanced a dedicated policy push via the Healing Tourism Industry Act (June 2026), including selection of 20 premier wellness sites for global promotion and per-venue support up to KRW 50 million, strengthening compliance, training, and destination designation practices for K-wellness positioning.
India continues to use the National Medical and Wellness Tourism Promotion Board as a coordination mechanism across ministries and states, while adding skills and quality levers. The Ministry of Tourism proposed a Union Budget 2026-27 pilot to upskill 10,000 guides at 20 iconic sites through a 12-week course tailored to medical and wellness tourism. State-level frameworks add to the patchwork, such as the Goa Wellness, Ayurveda and Yoga Policy, 2026, which formalizes accreditation and governance for wellness centers, and Bhutan updated standards for gSobaRigpa wellness services (January 2025) under the Department of Traditional Medicine Services and tourism authorities. Together, these steps point to a broader move toward codifying traditional-medicine wellness offerings alongside facility registration and site approval.
Value Chain Analysis
The wellness tourism value chain in Asia-Pacific starts with destination enablers such as tourism ministries, visa facilitation, and public marketing. It then moves through product creation, including wellness hotels, retreats, eco-lodges, and wellness clinics with stay, before ending in distribution via OTAs, wellness travel specialists, corporate retreat planners, and loyalty ecosystems run by large hotel groups. An upstream layer includes licensed practitioners and training bodies, alongside inputs such as nutraceuticals, spa consumables, and medical devices for diagnostics-oriented programs. Operator differentiation is increasingly shaped by integrating traditional medicine (AYUSH/TCM/onsen) with measurable health services.
Bottlenecks are still tied to practitioner availability and uneven standards across countries, which can limit scalable cross-border packaging and consistent outcomes. Recent ecosystem moves show more vertical and partner integration: BDMS Wellness Clinic announced a public-private alliance in Thailand (March 2026) involving the Global Wellness Institute and health-technology players, including Illumina and Abbott, reflecting a shift toward room-plus-medical-wellness operating models and higher reliance on diagnostics and data. On the supply and destination-development side, South Korea selected 20 wellness destinations under the Healing Tourism framework (June 2026). State-led pipelines such as the Telangana partnership for a large wellness resort development (200 crore investment, September 2025) also show how governments and developers are expanding capacity and anchoring local vendor networks around wellness corridors.
Competitive Landscape
The Asia-Pacific wellness tourism market remains structurally fragmented, with the five leading operators, Accor’s Spa & Vitality portfolio, Marriott’s EDITION and Ritz-Carlton Reserve, Banyan Tree’s Wellbeing Sanctuaries, Minor Hotels’ Anantara Wellness, and IHG’s Six Senses, collectively holding a relatively small share of the region’s overall revenue. Brand share diffusion reflects the heavy presence of independent boutique retreats, physician-owned medi-wellness clinics, and community-run eco-lodges that cater to localized heritage therapies. Major chains exploit distribution scale and loyalty ecosystems to maintain visibility across multiple feeder markets, yet homegrown players frequently outperform on guest satisfaction due to deeper cultural immersion and higher therapist-to-guest ratios.
Technology integration has emerged as a decisive differentiator; Anantara’s Layan Life invests in AI-driven body-composition scanners and predictive analytics that personalize detox protocols in real time, delivering quantifiable outcome reports at checkout. Banyan Tree’s Stay for Good initiative layers ESG reporting and guest carbon calculators onto wellness packages, attracting environmentally motivated philanthropists who view travel as an impact investment. Marriott, pursuing asset-light growth, signed 109 new APAC-excluding-China deals in 2024, with 19% of the pipeline dedicated to wellness-oriented luxury formats across Jakarta, Mumbai, and Fukuoka. Chinese conglomerates such as OCT Group expand OCT Yangle hot-spring clusters, leveraging domestic DTC channels to capture pent-up local demand and feeding cross-promotional flows to overseas acquisitions in Guam and Saipan.
Investment banks highlight rising M&A momentum as private-equity firms consolidate fragmented spa chains and aging resort stock ripe for wellness repositioning. Valuation multiples favor operators with proprietary practitioner academies and data-rich patient outcomes, underlining the strategic value of human capital and clinical intellectual property. Looking ahead, convergence of insurance reimbursements, fintech-enabled installment plans, and employer-sponsored retreats could accelerate brand consolidation as capital-intensive diagnostics become table stakes, raising entry barriers for smaller players lacking medical partnerships.
Asia-Pacific Wellness Tourism Industry Leaders
Accor
Marriott International
Banyan Tree Holdings
Hilton Worldwide
Minor International
- *Disclaimer: Major Players sorted in no particular order

Asia-Pacific Wellness Tourism Market Companies Covered in this Report
- Accor
- Marriott International
- Hilton Worldwide
- Hyatt Hotels Corporation
- InterContinental Hotels Group (IHG)
- Banyan Tree Holdings
- Minor International (Anantara / Avani)
- Six Senses Hotels Resorts Spas
- Aman Group
- Mandarin Oriental Hotel Group
- Shangri-La Group
- The Indian Hotels Company (IHCL – Taj / Vivanta)
- Chiva-Som International Health Resort
- COMO Hotels and Resorts
- Rosewood Hotel Group
- Centara Hotels & Resorts
- Dusit International
- Gwinganna Lifestyle Retreat
- Ananda in the Himalayas
- Kamalaya Koh Samui

Market Opportunities and Future Outlook
A major whitespace is standardization and cross-border packaging of health-and-wellness products across Southeast Asia, where ASEAN documented mismatches between current offerings and evolving demand for integrated services (ASEAN gap assessment, July 2026). This creates room for operators and destination bodies to align service definitions, quality benchmarks, and referral pathways, so multi-country itineraries can be sold with clearer outcome and safety assurances. The need is particularly visible for programs that blend preventive diagnostics with traditional modalities.
Premiumization is also being pulled by initiatives that connect hospitality, healthcare providers, and technology partners. Thailand has promoted a connected health and wellness positioning through national campaigns and partnerships, while BDMS has signaled deeper integration of diagnostics and longevity-led experiences through broader ecosystem moves. This support aligns with higher-yield primary wellness travel formats and longer-stay protocols. On the demand-shaping side, the Global Wellness Summit set its November 2026 program to spotlight Asia as a foundational wellness region and referenced 31% growth in 2024, reinforcing operator interest in outcome-based, regenerative, and tech-enabled wellness formats that can be scaled beyond single flagship retreats.
Recent Industry Developments in Asia-Pacific Wellness Tourism Market
- June 2026: Marriott International and the Leali family announced a milestone deal to bring Lefay into Marriott’s portfolio, introducing a luxury wellness brand positioned around dedicated wellbeing resorts. The announcement formalizes luxury wellness as a distinct branded platform within a major hotel group, helping standardize guest expectations and accelerate deal flow for purpose-built wellness assets in Asia-Pacific.
- March 2025: Marriott International announced 109 additional management deals across Asia-Pacific (excluding China), adding 21,439 rooms to a pipeline that includes wellness-oriented luxury formats such as EDITION debuts planned for Jakarta and Mumbai. The signings expand the addressable inventory where wellness programming can be embedded at scale through brand standards, loyalty distribution, and owner investment cycles.
- January 2024: India launched the AYUSH visa to facilitate longer stays for Ayurveda, yoga, and other recognized traditional systems under the AYUSH umbrella. The visa mechanism reduces friction for inbound wellness seekers who require multi-week or multi-month protocols, strengthening India’s positioning for primary wellness travel and clinic-with-stay formats.


Asia-Pacific Wellness Tourism Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the Asia-Pacific wellness tourism market is defined as the total visitor spending linked to wellness-led trips and wellness add-ons taken during leisure or business travel across APAC destinations, counted in USD value.
Scope exclusions: We exclude routine local wellness spend with no overnight travel element and non-tourism healthcare spending that is not attached to a trip.
Segments Covered in This Report
- By Service Type
- Yoga & Meditation Retreats
- Spa & Beauty Therapies
- Naturopathy & Detox Packages
- Mental-Wellness Retreats
- Digital-Detox Escapes
- Spiritual Healing Journeys
- By Traveler Type
- Primary Wellness Travel
- Secondary Wellness Travel
- By Accommodation Type
- Yoga Retreats
- Wellness Hotels (Chain)
- Boutique Retreats
- Eco-Wellness Lodges
- Wellness Clinics with Stay
- By Geography
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to anchor the travel and visitor-spend context in Asia Pacific and to keep the definition of counted wellness travel spend consistent across destinations. The work relied on public tourism statistics and macro indicators from sources such as UN Tourism, national tourism ministries and statistics offices in key APAC countries, the World Bank, the IMF, and central bank releases to time exchange-rate effects.
We also checked airport and border arrival dashboards where available, hotel and accommodation performance summaries published by tourism boards, and public sustainability or wellness policy documents that show how destinations are positioning wellness offers. For company context, we reviewed annual reports, investor presentations, and credible press coverage to understand how wellness resorts, wellness hotels, and retreat operators describe pricing, occupancy, and demand patterns. Where needed, we supplemented with paid databases for company financials and news screening, plus a patent database to scan for wellness service innovation signals. This list is illustrative only, and other sources were used during the work for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary interviews and structured surveys were conducted with destination stakeholders and travel supply-side participants, including wellness resort managers, tour and retreat organizers, hospitality executives, and travel distribution professionals. The respondent input was used to confirm what is actually bundled into wellness trips, how average spend shifts by seasonality and traveler mix, and which country markets in APAC are showing the fastest recovery in wellness-led bookings.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 30% | CXOs: 15% |
| Mid tier: 53% | Functional/Unit leaders: 42% |
| Smaller Players: 17% | Managers: 43% |
Market-Sizing & Forecasting
Market sizing was built using a top-down and bottom-up approach, where travel and tourism spend is reconstructed at the country level and then filtered to the wellness tourism portion using validated participation and spend-share assumptions. Since wellness tourism includes both primary wellness travelers and secondary wellness travelers, the model separates these two purpose groups and then sums them back after their spend profiles are applied.
Key inputs in the model include inbound and domestic trip volumes, average length of stay for wellness-focused trips, lodging and in-country transport spend per trip, and the share of travelers purchasing wellness activities or excursions. We also track destination mix across countries such as China, India, Japan, Australia, and Thailand, since price points and wellness-package intensity vary, and final totals are sensitive to where demand concentrates. When public series were missing or lagged, we used nearby proxy indicators such as hotel occupancy and air capacity trends, then made adjustments based on what respondents agreed with during primary discussions.
For forecasting, we used scenario analysis supported by multivariate regression checks, linking demand to disposable income trends, airfare and hotel price levels, exchange rate movements, and the pace of international arrivals normalization. These variables were stress-tested with interview feedback, and the forward curve was smoothed to avoid abrupt jumps that do not align with observed booking and capacity realities in wellness destinations.
Data Validation & Update Cycle
Validation is done through repeated cross-checks across independent signals so that no single noisy series drives the final number. We compare country totals against tourism receipts direction, arrival trends, and realistic per-trip spend bands, then review outliers that do not match known seasonality or destination price patterns.
Before sign-off, assumptions are reviewed in more than one analyst pass, and respondents are re-contacted when a price, traveler mix, or purpose split appears inconsistent with recent market behavior. The report is refreshed annually, and interim updates are made when material events occur that can shift travel flows or wellness spending. Right before delivery, we run a final update sweep so clients receive the most current view possible.
麻豆视频's Asia Pacific Wellness Tourism Market Size Measured Against Other Published Estimates
Published estimates for wellness tourism in Asia Pacific often differ because not every publisher counts the same spend pool, and timing choices can also change USD totals. The gaps are usually visible in whether the value captures only wellness activities or also includes the full trip basket, and in how domestic trips are treated relative to international arrivals.
The spread is mostly explained by scope decisions, such as including lodging, in-country transport, food and beverage, shopping, and excursions inside a wellness trip versus counting only retreat or spa service revenue, and by how primary versus secondary wellness travelers are split. Currency conversion timing also matters in APAC, since exchange rates can move materially across a year. Some publishers apply a single-year average without re-checking country mixes or seasonality. Keeping the service-basket definition explicit, then re-testing spend shares through operator interviews, is what makes the modeled 2025 value traceable, which is applied this way by 麻豆视频.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 187.78 B (2025) | |
| Industry Association A | USD 170.00 B (2025) | This estimate appears to restrict the counted value closer to wellness activities and program fees, which can undercount the trip-level spend items like lodging and in-country transport that typically scale with wellness travel. |
| Global Consultancy B | USD 205.00 B (2025) | This figure likely uses a broader inclusion of adjacent travel categories or applies higher per-trip spend assumptions, and it can also run higher when currency conversion and country mix are not refreshed using current arrival and occupancy signals. |
Overall, the table shows that most differences come from what is included in the wellness travel spend basket and how purpose-driven travel is split between primary and secondary travelers. By keeping those items explicit in the model and checking them against real operator feedback, the final number stays easier to reproduce and explain when planning country priorities and product strategies.


Key Questions Answered in the Report
What is the current value of the Asia-Pacific wellness tourism market?
The Asia-Pacific wellness tourism market size is estimated at USD 204.18 billion for 2026.
How fast is the sector expected to grow through 2031?
Market revenue is projected to expand at a 8.74% CAGR, reaching USD 310.56 billion by 2031.
Which service category leads regional revenue?
Spa and beauty therapies currently command the largest 19.21% revenue share in 2025.
Which traveler type offers the highest growth potential?
Primary wellness travel is forecast to grow at a 9.83% CAGR because more visitors dedicate entire trips to transformative health programs.
Which country will witness the fastest growth?
India is projected to record the highest CAGR of 11.14% through 2031, driven by supportive AYUSH visa policies.
Why are eco-wellness lodges gaining popularity?
Travelers increasingly associate environmental stewardship with personal well-being, propelling eco-wellness lodges to a 12.58% forecast CAGR.
Page last updated on:



