
Australia Mineral Processing Equipment Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.97 Billion |
| Market Size (2026) | USD 1.03 Billion |
| Market Size (2031) | USD 1.37 Billion |
| Growth Rate (2026 - 2031) | 5.87 % |
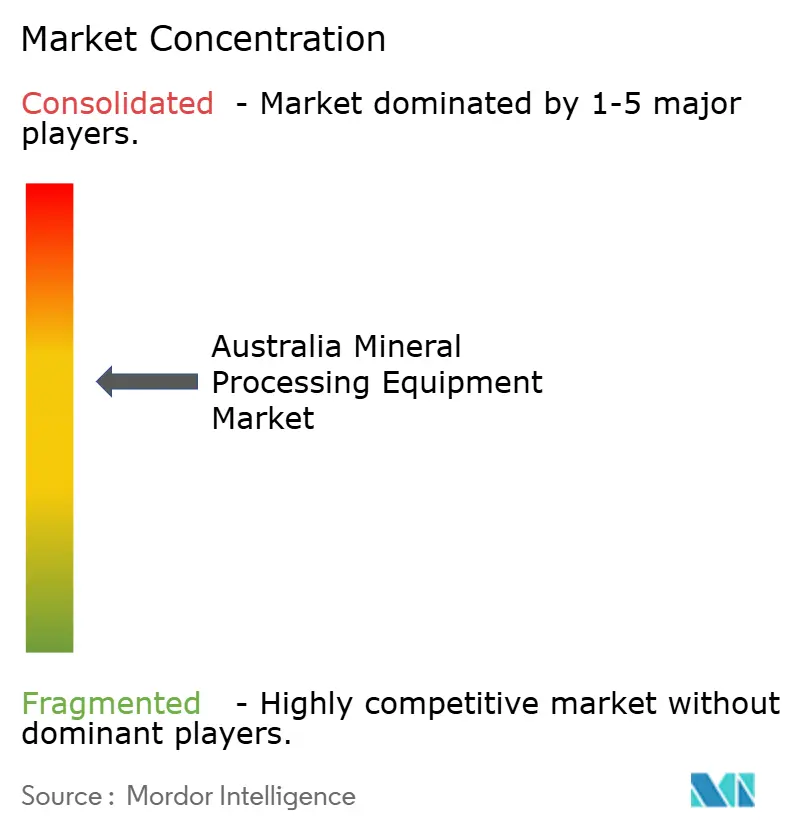
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Australia Mineral Processing Equipment Market Analysis by 麻豆视频
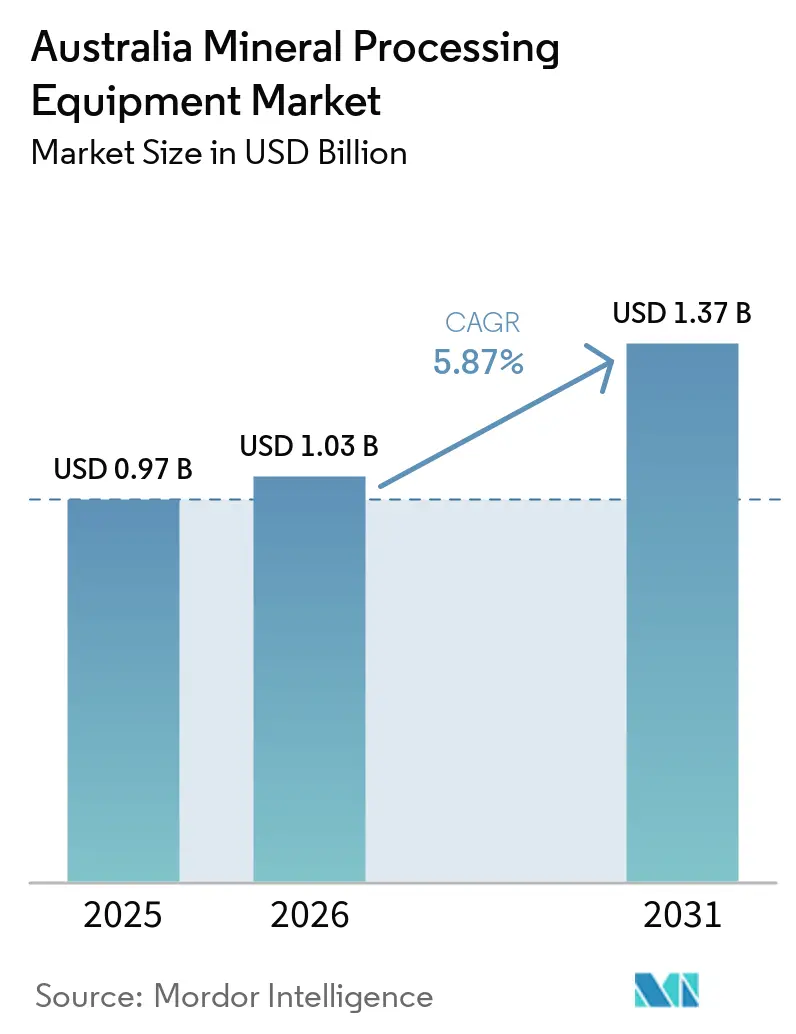
The Australia mineral processing equipment market was valued at USD 0.97 billion in 2025 and is projected to reach USD 1.03 billion in 2026 and USD 1.37 billion by 2031, registering a CAGR of 5.87% during the forecast period (2026–2031). Pilbara replacement programs for high-tonnage crushers, tighter tailings rules that favor dry-stacking, and federal incentives that reward on-shore critical-mineral refining are shaping capital-spending priorities. Miners are shifting from conventional thickener ponds to paste thickeners and ceramic filters to cut water loss in arid regions. Indigenous procurement targets are steering new contracts toward modular plants that local joint ventures can assemble, giving smaller Australian fabricators a competitive opening. Automation is rising fastest in remote Western Australia, where fully automated lines mitigate labor shortages and lower unit costs.
Key Report Takeaways
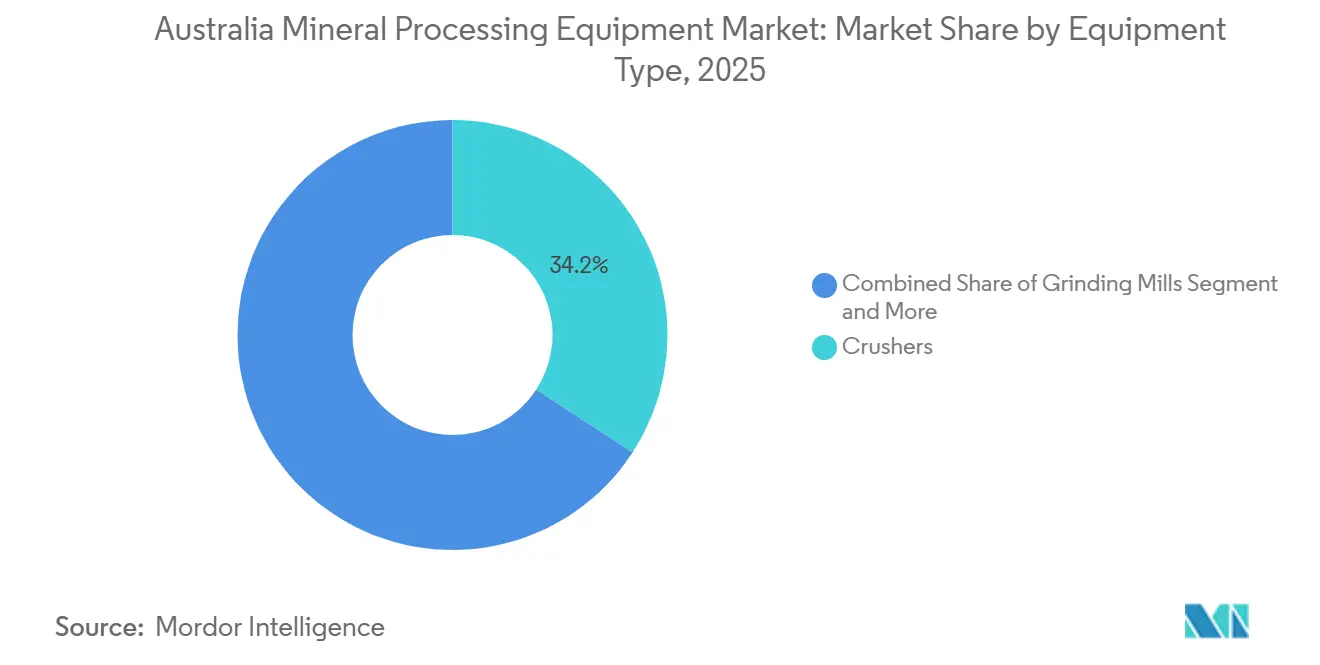
- By equipment type, crushers led with 34.17% of the Australian mineral processing equipment market share in 2025, while dewatering and tailings systems are advancing at a 5.98% CAGR through 2031.
- By mineral commodity, iron ore accounted for 45.13% of the Australian mineral processing equipment market share in 2025; lithium equipment is expanding at a 6.02% CAGR through 2031.
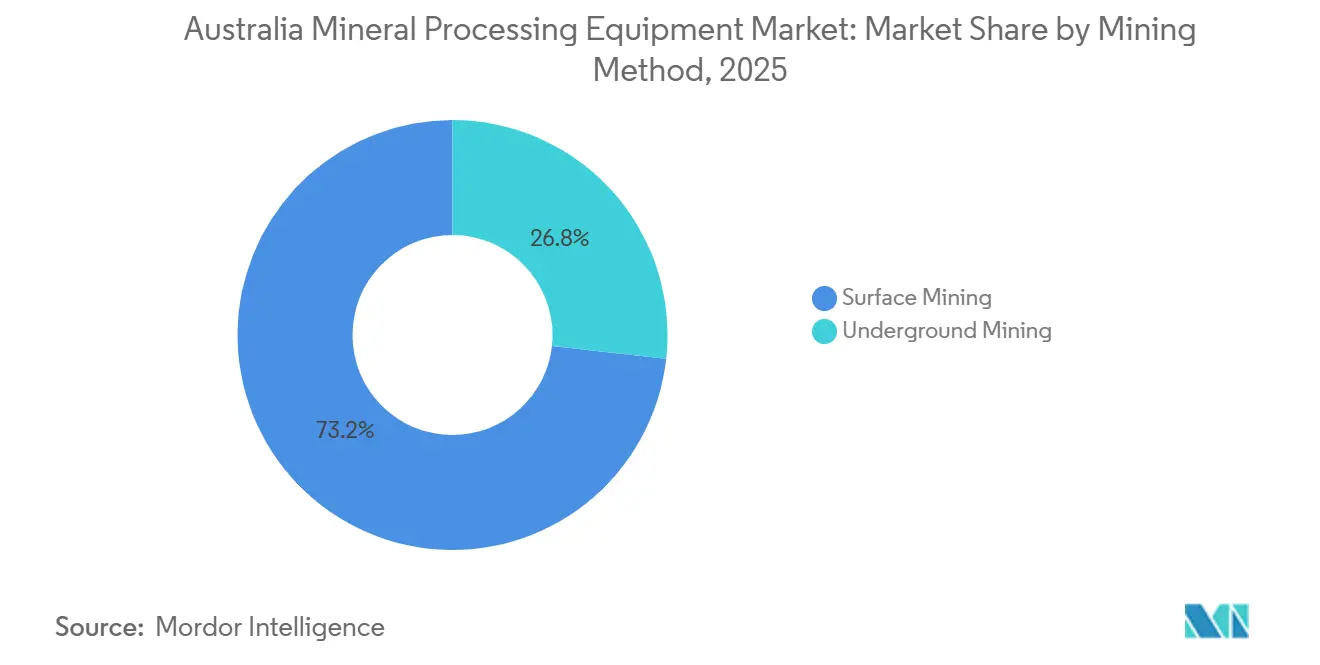
- By mining method, surface operations accounted for 73.24% of the Australian mineral processing equipment market share in 2025, yet underground projects are growing at a 5.96% CAGR through 2031.
- By automation level, semi-automated systems captured 47.81% of the Australian mineral processing equipment market share in 2025, while fully automated lines are projected to have the fastest CAGR at 6.18% through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Australia holds a defined position within a broader international distribution. The mineral processing equipment market share data by 麻豆视频 maps that allocation across all contributing countries and regions, globally.
Australia Mineral Processing Equipment Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Record Pilbara Iron-Ore Output | +1.5% | Western Australia (Pilbara) | Long term (≥4 years) |
| Battery-Mineral Boom | +1.4% | Western Australia, Queensland, South Australia | Medium term (2-4 years) |
| Stricter Tailings-Dam Rules | +1.1% | Western Australia, New South Wales, Queensland | Long term (≥4 years) |
| FMIA Incentives | +0.9% | National (all states) | Medium term (2-4 years) |
| Sensor-Based Ore-Sorting | +0.7% | Western Australia, Queensland | Medium term (2-4 years) |
| Indigenous Procurement Targets | +0.5% | Western Australia, Northern Territory, Queensland | Long term (≥4 years) |
| Source: 麻豆视频 | |||
Record Pilbara Iron-Ore Output Driving Replacement Capex
Pilbara mines are sustaining near-capacity throughput, forcing accelerated replacement of primary crushers and screening decks. Rio Tinto and BHP expansion projects are channeling capital into high-tonnage comminution circuits[1]"Rio Tinto and BHP explore collaboration to mine up to 200 million tonnes of Pilbara iron ore", Rio Tinto, riotinto.com. Magnetite processing at Iron Bridge requires finer grinding, which lifts equipment intensity per tonne. Lower-grade blends increase mass pull, compressing replacement intervals. Because crushers already hold the largest share, any increase in tonnage magnifies demand for this equipment class.
Battery-Mineral Boom Spurring New Concentrators
Lithium, rare-earth, and nickel projects are installing greenfield concentrators at a pace not seen since the 1970s. The National Reconstruction Fund’s concessional finance and the FMIA 10% tax credit are tipping feasibility studies toward domestic refining[2]"Australia NRFC investment commitment in rare earths project", International Energy Agency, iea.org. Specialty vendors supply dense-media, flotation, and solvent-extraction circuits that incumbents seldom manufacture, opening white space for new entrants. Lithium’s fast CAGR reflects both rising electric-vehicle demand and supportive fiscal policy. These plants often specify modular layouts, shrinking delivery schedules, and onsite labor needs.
Stricter Tailings-Dam Rules Boosting Filtration Demand
Updated mine-closure guidelines in Western Australia mandate higher water recovery and lower residual moisture. Operators are switching from conventional thickeners to paste thickeners and ceramic filters. Paste backfill eliminates surface storage at underground mines and recycles process water, a priority in arid regions. Vendors that can integrate pumps, filtration, and remote monitoring secure multi-year service contracts. The result is the fastest growth rate inside the equipment-type mix.
FMIA Incentives for On-Shore Processing
The Future Made in Australia Act offers a 10% production tax incentive on refined lithium hydroxide, rare-earth oxides, and nickel products[3]"Critical Minerals and Hydrogen Production Tax Incentives", ATO, ato.gov.au. Projects such as Alpha HPA’s Gladstone alumina plant cite the credit as decisive in the final investment decision. Because concentrator builds take up to two years, orders placed now will keep workshops busy into 2028. Suppliers able to bundle equipment with digital optimization services gain an edge when miners calculate lifecycle costs.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Environmental Approval Delays | -0.8% | Western Australia, Queensland, South Australia | Long term (≥4 years) |
| Skilled-Trades Shortage | -0.6% | Western Australia (Pilbara, Goldfields) | Long term (≥4 years) |
| Rising Grid-Power Tariffs | -0.5% | Western Australia, South Australia | Medium term (2-4 years) |
| Price Pressure from Chinese OEMs | -0.4% | National (all states) | Long term (≥4 years) |
| Source: 麻豆视频 | |||
Environmental Approval Delays
Major projects in Australia often face a lengthy and complex process of federal and state assessments, with approval timelines frequently extending beyond a decade. This prolonged timeline creates challenges for the industry. When approvals are finally granted, the extended lead times have already compressed fabrication windows, resulting in significant bottlenecks that hinder project execution. Suppliers, cautious about building inventory without confirmed orders, are often unprepared to meet the sudden demand created by clusters of project sanctions. This situation places immense strain on their capacity and disrupts the supply chain.
Skilled-Trades Shortage in Regional WA
By 2029, Western Australia will need thousands more tradespeople, but apprentice completion rates are falling short of this demand. Due to the labor shortage, miners are increasingly adopting fully automated equipment. However, even automation requires skilled technicians. The reliance on fly-in, fly-out crews continues to push up operating costs and limits maintenance flexibility. As a result, these skill gaps are slowing down the progress of both greenfield and brownfield expansions.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Equipment Type: Crushers Anchor, Dewatering Accelerates
Crushers captured 34.17% of 2025 revenue in the Australian mineral processing equipment market, reflecting their central role in Pilbara iron-ore operations. Dewatering and tailings systems post the fastest 5.98% CAGR, propelled by stricter water-management rules. Miners favor modular filtration packages that shorten installation time and enable staged capacity increases. Vendors that bundle sensors with mechanical equipment gain service revenue as operators seek real-time performance data. Emerging ore-sorting units upstream of grinding circuits further shape demand for tailored crusher configurations.
Sensor integration is redefining how equipment interacts inside plants. Real-time ore-sensing directs material between parallel crushing lines, maximizing uptime. Paste-backfill plants require positive-displacement pumps compatible with high-solids slurries, an opportunity for suppliers specializing in wear-resistant materials. Screen panels with embedded condition-monitoring chips alert staff before failures, reducing unplanned downtime. These technology shifts reinforce the long-term relevance of crushers while amplifying growth for dewatering systems.


By Mineral Commodity: Iron Ore Leads, Lithium Surges
Iron ore held 45.13% of 2025 revenue, underscoring the Australian mineral processing equipment market’s dependence on Pilbara throughput. Lithium equipment posts the quickest 6.02% CAGR as new spodumene concentrators come online. Copper projects in South Australia are adding capacity, while gold continues to see steady replacement demand. Rare-earth developers specify solvent-extraction circuits that few mainstream vendors stock, opening a niche for mid-tier fabricators. Diversification across commodities protects suppliers from single-metal demand swings.
Project finance increasingly hinges on environmental credentials. Lithium plants tout lower carbon intensity, giving a premium to energy-efficient mills and conveyors. Copper smelter upgrades align with corporate decarbonization targets, favoring electric material-handling systems. Iron ore producers adopt ore sorting to reject waste early, thereby trimming energy use. Suppliers that demonstrate lifecycle emissions reductions can differentiate even in price-sensitive tenders, supporting broader commodity exposure.
By Mining Method: Surface Dominates, Underground Gains Pace
Surface operations accounted for 73.24% of the Australian mineral processing equipment market share in 2025. Still, underground projects are set to accelerate at a 5.96% CAGR, supported by deeper copper and gold orebodies—Paste-backfill and electric rail lower diesel usage, reshaping underground material-handling specifications. Automation helps mitigate ventilation constraints by reducing the need for diesel equipment underground. Vendors that can integrate communication networks with mobile machines gain an advantage in these projects.
Long lead times for shaft sinking favor suppliers offering modular, pre-assembled crusher stations. Underground ore sorting allows for smaller hoisting capacities, thereby trimming capital costs. Remote-operated loaders reduce on-site personnel, addressing safety and labor shortages. As underground mines transition from trial automation to fleet-wide deployment, demand for interoperable control systems rises. These trends sustain robust growth against a high surface-mining baseline.
By Automation Level: Semi-Automated Prevails, Fully Automated Climbs
Semi-automated systems accounted for 47.81% of the Australian mineral processing equipment market share in 2025, underscoring miners’ preference for phased technology adoption. Fully automated lines expand at the fastest 6.18% CAGR as remote operations centers prove effective in harsh environments. Autonomous haul trucks integrate seamlessly with dispatch software, setting a precedent for lights-out crushing and grinding. Digital twins of entire plants allow off-site troubleshooting, cutting downtime.
Cybersecurity has become integral to automation procurement. Suppliers must demonstrate secure data pathways from field devices to cloud analytics. Over-the-air updates reduce onsite visits but demand robust validation processes. Standardized communication protocols enable multi-vendor environments, giving miners bargaining power. The shift from manual to fully automated systems unfolds in stages, providing recurring upgrade opportunities for equipment makers.
Geography Analysis
Western Australia remains the primary demand center for the Australian mineral processing equipment market. Multiple Pilbara iron-ore expansion projects sustain crusher and mill orders, while emerging lithium and rare-earth plants diversify flowsheet requirements. Labor shortages accelerate the uptake of autonomous processing lines that limit on-site headcount. Indigenous procurement mandates drive interest in modular plants that local partnerships can assemble, supporting smaller domestic fabricators. Environmental rules on tailings push mines toward paste filtration, reinforcing growth for dewatering systems.
South Australia follows with copper-centric investment led by Olympic Dam’s multi-phase expansion. Planned paste-backfill and smelter upgrades call for thickeners, pumps, and oxygen plants compatible with higher throughput. Block-cave developments at Carrapateena and Prominent Hill require additional crushing and flotation capacity. The state’s early adoption of autonomous haulage positions it as a testbed for next-generation underground equipment. Suppliers offering integrated digital and mechanical packages find receptive customers preparing for higher tonnage and stricter emissions targets.
Queensland’s equipment demand spans coal, copper, and nascent rare-earth projects. Automation trials at Goonyella demonstrate the large-scale deployment of autonomous trucks, providing a proof of concept for other open-pit sites. Eva Copper’s greenfield concentrator introduces premium grinding and flotation technologies to a mid-tier developer profile. Government support for critical-mineral processing encourages investment in rotary kilns and solvent-extraction units, diversifying a region long associated with coal. Vendors that can configure low-emission circuits and provide hybrid power options gain traction as energy costs climb.
麻豆视频 delivers a comprehensive view of the mineral processing equipment market with country-level analysis for South Korea, Japan, Germany, France, Spain, Argentina, Turkey, Mexico, and Oman, each offering a view of the local market realities.
Competitive Landscape
Metso, FLSmidth, Sandvik, Weir, and Komatsu held the top-tier positions in 2025, supplying integrated crushing, grinding, and hauling solutions backed by nationwide service centers. Australian specialists such as Gekko, Multotec, and NextOre capture niche opportunities through modular gold concentrators, advanced cyclones, and real-time ore-sensing systems. TOMRA’s sensor-based sorters compress comminution flowsheets, allowing miners to reject waste before grinding and saving energy.
Vendors differentiate on digital integration. FLSmidth’s LoadIQ platform optimizes crusher performance remotely, while Komatsu’s software-defined vehicles receive over-the-air updates that refine autonomous-haul algorithms. Compliance with ISO 14001 and AS/NZS 4801 remains mandatory, but miners increasingly weigh lifecycle emissions and data security.
Rare-earth refineries source solvent-extraction and calcination equipment from mid-tier fabricators rather than iron-ore incumbents, revealing white space for agile suppliers. Indigenous procurement policies further open doors for local workshops capable of assembling modular plants. Price pressure from low-cost Chinese OEMs remains limited but could increase if local-content requirements ease. In response, incumbent players are emphasizing after-sales support and digital services.
Australia Mineral Processing Equipment Industry Leaders
-
FLSmidth A/S
-
Sandvik AB
-
Weir Group plc
-
Komatsu Ltd.
-
Metso Corporation
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- August 2026: Finnish engineering company Metso Corporation secured a major minerals processing technology contract from GR Engineering Services. Under the contract, Metso is supplying a complete range of core crushing and separation technologies for Develop Global’s Yitirrti project in Western Australia.
- July 2026: FLSmidth (FLS) secured a multi-year contract to provide comprehensive mill-lining solutions for an established gold mining operation in Australia and the Southeast Asia (ASEA) region.
- June 2026: Sandvik finalized its acquisition of Italy-based Diemme Filtration, a global specialist in high-performance filter presses. This acquisition enabled Sandvik to establish a new Filtration Division within its Rock Processing business.


Australia Mineral Processing Equipment Market Report Scope
The Australian Mineral Processing Equipment market is analyzed across equipment type, mineral commodity, mining method, and automation level. By Equipment Type, the market is segmented into Crushers, Grinding Mills, Screening Equipment, Flotation & Separation Equipment, Conveyors, Dewatering Equipment, and Other Specialized Equipment. By Mineral Commodity, the market is segmented into Iron Ore, Bauxite, Copper, Gold, Lithium, Nickel, Rare Earths, and Other Minerals. By Mining Method, the market is segmented into Surface Mining and Underground Mining. By Automation Level, the market is segmented into Manual, Semi-Autonomous, and Fully Autonomous.
Market forecasts are provided in terms of Value (USD) and Volume (Units).
| Crushers |
| Grinding Mills |
| Screening Equipment |
| Flotation & Separation |
| Conveyors & Feeders |
| Dewatering & Tailings |
| Other Specialised Equipment |
| Iron Ore |
| Bauxite |
| Copper |
| Gold |
| Lithium |
| Nickel |
| Rare Earths |
| Other Minerals |
| Surface Mining |
| Underground Mining |
| Manual |
| Semi-Automated |
| Fully Automated |
| By Equipment Type | Crushers |
| Grinding Mills | |
| Screening Equipment | |
| Flotation & Separation | |
| Conveyors & Feeders | |
| Dewatering & Tailings | |
| Other Specialised Equipment | |
| By Mineral Commodity | Iron Ore |
| Bauxite | |
| Copper | |
| Gold | |
| Lithium | |
| Nickel | |
| Rare Earths | |
| Other Minerals | |
| By Mining Method | Surface Mining |
| Underground Mining | |
| By Automation Level | Manual |
| Semi-Automated | |
| Fully Automated |


Key Questions Answered in the Report
How fast is the Australia mineral processing equipment market expected to grow between 2026 and 2031?
The Australian mineral processing equipment market was valued at USD 0.97 billion in 2025 and is projected to register a CAGR of 5.87% during the forecast period (2026–2031).
Which equipment category currently holds the largest revenue share?
Crushers accounted for 34.17% of revenue in 2025.
What federal incentive is driving on-shore critical-mineral processing investment?
The Future Made in Australia Act provides a 10% production tax credit for domestically processed critical minerals.
Why is dewatering equipment growing faster than other categories?
Stricter tailings-dam regulations require paste thickeners and ceramic filters that improve water recovery.
Page last updated on:



