
Germany Mineral Processing Equipment Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 267.09 Million |
| Market Size (2026) | USD 282.29 Million |
| Market Size (2031) | USD 372.27 Million |
| Growth Rate (2026 - 2031) | 5.69 % |
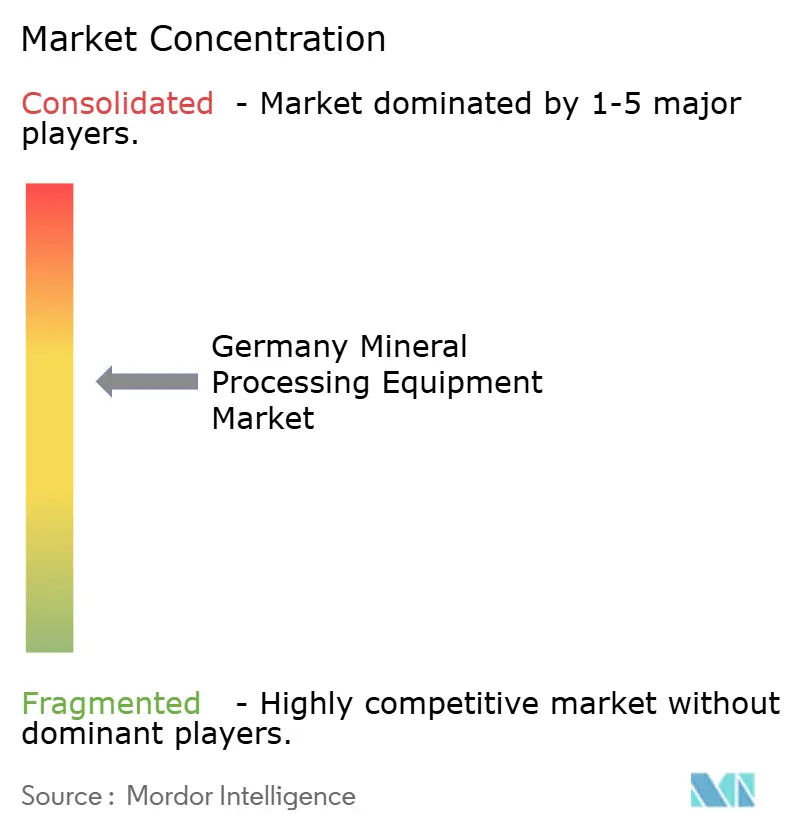
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Germany Mineral Processing Equipment Market Analysis by 麻豆视频
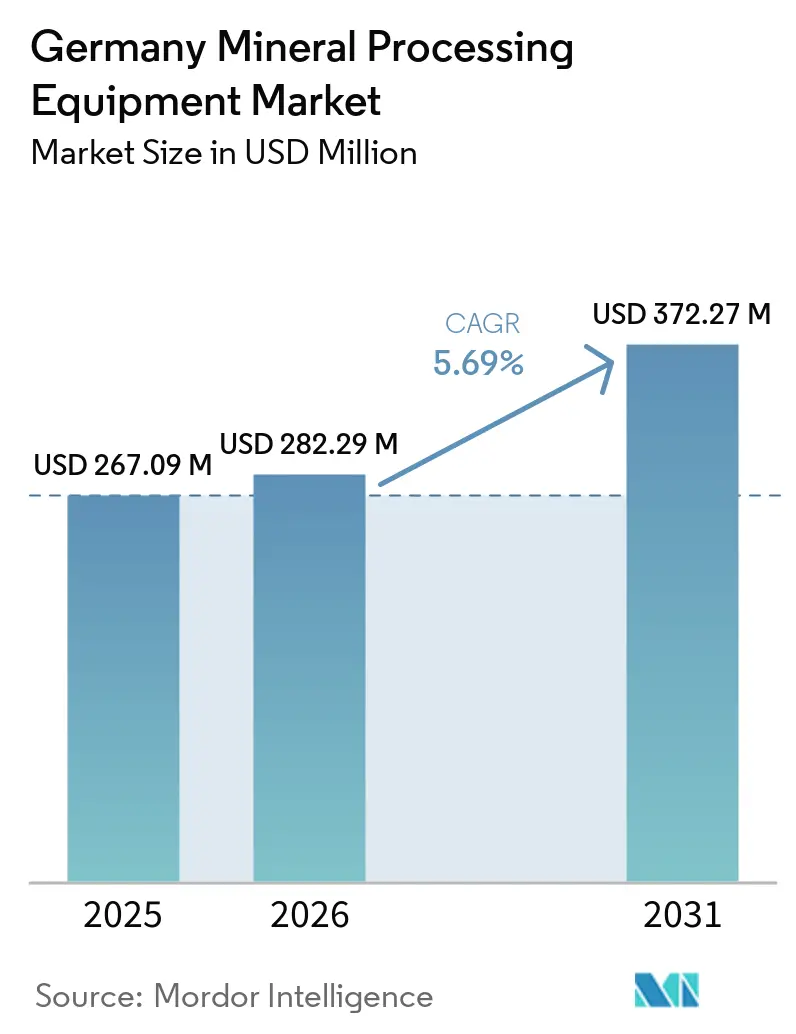
The Germany mineral processing equipment market is expected to grow from USD 267.09 million in 2025 to USD 282.29 million in 2026 and reach USD 372.27 million by 2031, registering a CAGR of 5.69% during the forecast period (2026-2031). Firm growth is linked to fast-track permitting granted under the European Critical Raw Materials Act[1]"Critical raw materials for the energy transition", European Court of Auditors, eca.europa.eu, which is directing capital to domestic lithium and graphite projects. Policy momentum is complemented by a national circular-economy mandate that channels equipment demand toward plants capable of processing secondary raw materials. Technology upgrades remain a second-order vector, with digital twins, edge analytics, and predictive maintenance shortening downtime and trimming power needs. At the same time, elevated energy prices are prompting operators to retrofit conveyors and screens with regenerative drives, while labor scarcity is nudging mines toward greater automation.
Key Report Takeaways
- By mineral mining sector, potash and salt commanded 29.15% of the Germany mineral processing equipment market share in 2025, whereas lithium recorded the fastest-growth trajectory at a 5.97% CAGR through 2031.
- By equipment type, crushers led with 25.47% of the Germany mineral processing equipment market share in 2025, while conveyors are advancing at a 6.28% CAGR to 2031.
- By mining method, surface operations held a 76.13% Germany mineral processing equipment market share in 2025; underground installations are projected to expand at a 6.38% CAGR to 2031.
- By automation level, semi-automated lines captured 48.17% of the Germany mineral processing equipment market share in 2025, but fully automated systems are growing at a 6.42% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Dynamics observed within Germany present a country level view when set against the broader international context. The mineral processing equipment market analysis by 麻豆视频 provides that expanded global perspective.
Germany Mineral Processing Equipment Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Critical Raw Materials Act | +1.2% | Saxony, Thuringia, Brandenburg, Hesse | Medium term (2-4 years) |
| German Raw Materials Strategy | +1.0% | Lower Saxony, North Rhine-Westphalia, Saxony, Thuringia | Medium term (2-4 years) |
| Industrie 4.0 Adoption | +0.9% | Bavaria, Baden-Württemberg, Saxony, North Rhine-Westphalia | Short term (≤ 2 years) |
| Circular-Economy Push | +0.7% | North Rhine-Westphalia, Bavaria, Saxony, Hesse | Long term (≥ 4 years) |
| Increasing Mineral Production | +0.6% | Saxony, Thuringia, Lower Saxony, Brandenburg | Medium term (2-4 years) |
| Accelerated Brownfield Mine Expansions | +0.4% | Saxony, Thuringia | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
European Critical Raw Materials Act (2024) Fast-Tracks Funding
The Act has shortened environmental-impact reviews to roughly one year and unlocked access to European Investment Bank guarantees, accelerating equipment orders for lithium hydroxide, converter, and graphite-substitution facilities. German suppliers are pre-engineering modular crushing and hydrometallurgical circuits so that projects can be erected within the compressed approval window. The policy spill-over now extends to rare-earth separation and battery-recycling ventures. This creates a reliable backlog for vendors with experience in critical-mineral flowsheets and pressures, while late movers remain tied to legacy bulk-commodity plants. As more projects secure the Act’s “strategic” label, buyers are stipulating shorter delivery schedules and placing a premium on domestic production footprints.
Government Support via German Raw Materials Strategy 2024
Berlin’s strategy elevates domestic extraction to a security priority, channeling public-bank capital toward exploration and pilot-scale plants. Funding for geophysical surveys is reviving historical copper-silver and tin belts, prompting interest in relocatable crushers and screens. Procurement rules that require a portion of aggregates to come from recycled sources further stimulate demand for secondary-crushing circuits. In parallel, the strategy mandates that any state-funded project must embed lifecycle climate metrics, steering mines to specify equipment with lower embedded emissions. Collectively, these provisions anchor a multi-year replacement cycle skewed toward efficient, modular systems.
Digitally Integrated Plants Enabled by Industrie 4.0 Adoption
Real-time data exchange is now standard across new German plants. Demonstration sites are running digital twins that predict liner wear, simulate froth behavior, and balance load across conveyors. The result is tighter process control and measurable energy savings, even in retrofitted brownfields. Original-equipment manufacturers have begun bundling edge computing units with crushers and screens, enabling autonomous gap adjustments and remote diagnostics. This diffusion of analytics is also reducing the need for on-site specialists, partially offsetting the country’s skilled-labor deficit.
Circular-Economy Push Driving Secondary-Raw-Material Processing
The National Circular Economy Strategy targets a 25% recycling rate for critical minerals by 2030[2]"The National Circular Economy Strategy", Federal Ministry for the Environment, Nature Conservation, Nuclear Safety and Consumer Protection (BMUV), circulareconomy.europa.eu. Compliance is catalyzing the procurement of shredders, optical sorters, and hydrometallurgical reactors optimized for feedstocks such as battery black mass and e-waste concentrates. Because purity thresholds must match virgin-material grades, buyers favor precision-engineered German equipment. Line-side, plants are installing advanced dust-collection and water-recovery modules to meet tightening environmental norms, which further differentiates high-spec units from low-cost imports.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Energy Costs | -0.8% | North Rhine-Westphalia, Lower Saxony, Saxony, Brandenburg | Short term (≤ 2 years) |
| Skilled Labor Shortages | -0.6% | Bavaria, Baden-Württemberg, Saxony, Thuringia, North Rhine-Westphalia | Long term (≥ 4 years) |
| Stringent Environmental & Permitting Regulations | -0.4% | Saxony, Thuringia, Lower Saxony, Brandenburg | Medium term (2-4 years) |
| Raw-Material Price Volatility | -0.3% | Saxony, Brandenburg, Hesse, Thuringia | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
High Energy Costs Following Coal-Power Phase-Out
Industrial power averaged 10.04 cents per kWh in 2025[3]Dr. Jacob von Andreae, Dr. Lars Kindler, Dr. Sandra Pl?tz, "Germany cuts costs for electricity-intensive companies from 1 January 2026: the new industrial electricity price", Gleiss Lutz, gleisslutz.com, well above earlier levels, squeezing margins even with a temporary subsidy cap. Operators are therefore favoring equipment fitted with variable-frequency drives and regenerative braking that can ride negative-price periods on the power exchange. Vendors highlighting kilowatt-hour savings in total-cost-of-ownership models are gaining bidding advantages. Nonetheless, higher network charges expected toward 2030 may defer greenfield mill installations, lengthening replacement cycles in bulk-tonnage mines.
Skilled Labor Shortages in Mechanical & Mechatronic Trades
Germany faces an estimated shortfall of mechanical and automation technicians through the next decade. Underground projects in Saxony and Thuringia are already reporting delays in commissioning crushing stations due to a shortage of electricians and millwrights. OEMs are responding with plug-and-play modules that enable remote software updates and self-diagnostics, reducing on-site headcount requirements. Without such design changes, staff scarcity could push operating costs higher and elongate ramp-up timelines, dampening near-term equipment orders.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Mineral Mining Sector: Lithium Drives Growth, Potash Anchors Volume
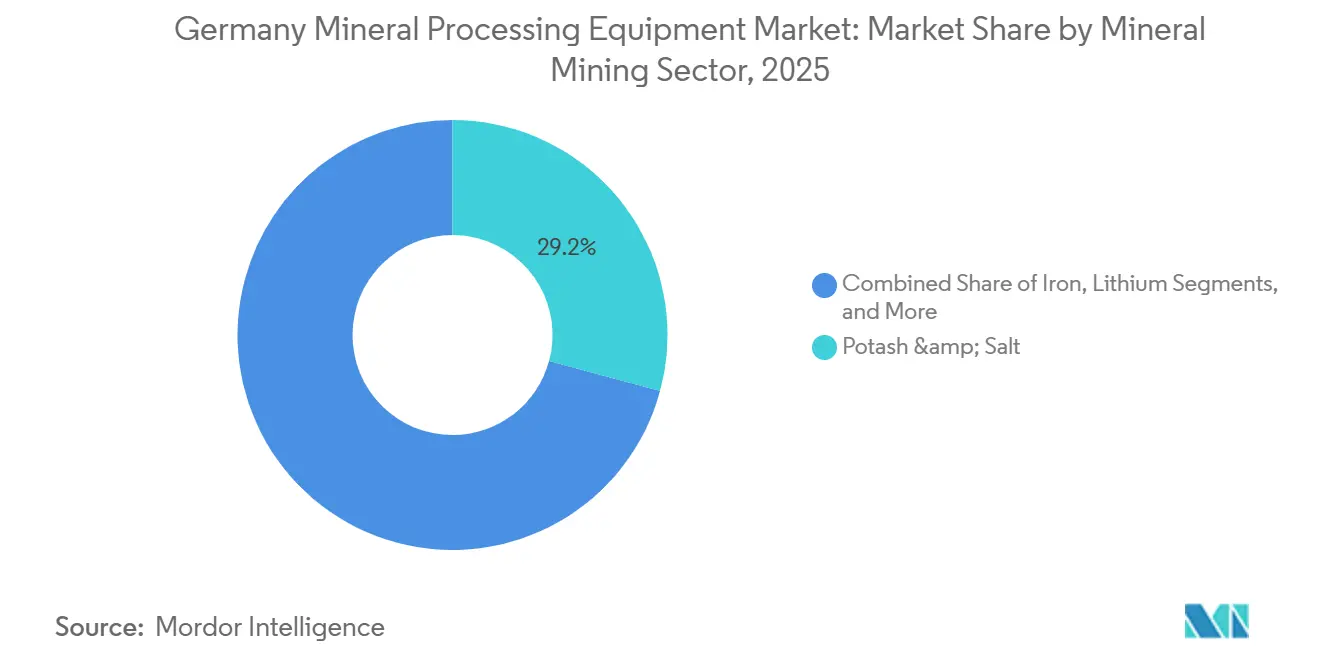
Potash and salt mining held 29.15% of the Germany mineral processing equipment market share in 2025, a position underpinned by long-running fertilizer operations that sustain stable replacement demand. Equipment suppliers servicing this segment focus on incremental efficiency gains—such as dry-stack tailings and lower-profile conveyors—rather than wholesale plant overhauls. Lithium is the fastest-growing sub-segment at a 5.97% CAGR to 2031, fueled by multiple hard-rock and geothermal brine projects slated to supply Europe’s battery corridor. Developers are specifying rotary calciners, leach reactors, and crystallizers purpose-built for battery-grade purity, giving premium German vendors a first-mover edge.
Exploration for rare earths and specialty metals in Saxony’s Erzgebirge is also beginning to shape order books, with feasibility studies calling for solvent-extraction cells and fine-grinding mills tailored to smaller, high-grade ore bodies. These emerging flowsheets reward modular packages that can be expanded as resource confidence increases. Over the outlook period, the German mineral processing equipment market is expected to balance a steady potash backbone with surging lithium demand, a combination that encourages suppliers to diversify portfolios across bulk and critical minerals.


By Equipment Type: Conveyors Gain on Energy Efficiency
Crushers held the largest Germany mineral processing equipment market share at 25.47% in 2025, reaffirming their indispensable role in first-stage size reduction. Yet conveyors are growing at a 6.28% CAGR through 2031 as operators retrofit belts with regenerative drives and load-monitoring sensors to cut electricity spend. Buyers are also upgrading feeders and screens in tandem with these belt systems to maintain synchronized throughput, favoring manufacturers that can bundle control software with mechanical hardware.
Grinding-mill replacement remains muted because predictive wear algorithms now let mines stretch liner life, deferring capital spend. Meanwhile, drills, breakers, and smart surface miners grouped under “others” are benefiting from autonomy packages that lower manpower per operating hour. Across the category, value migrates toward digitally enabled ancillaries rather than monolithic mills, highlighting how the German mineral processing equipment market prizes incremental, high-return retrofits over greenfield megaprojects.
By Mining Method: Underground Automation Narrows the Gap
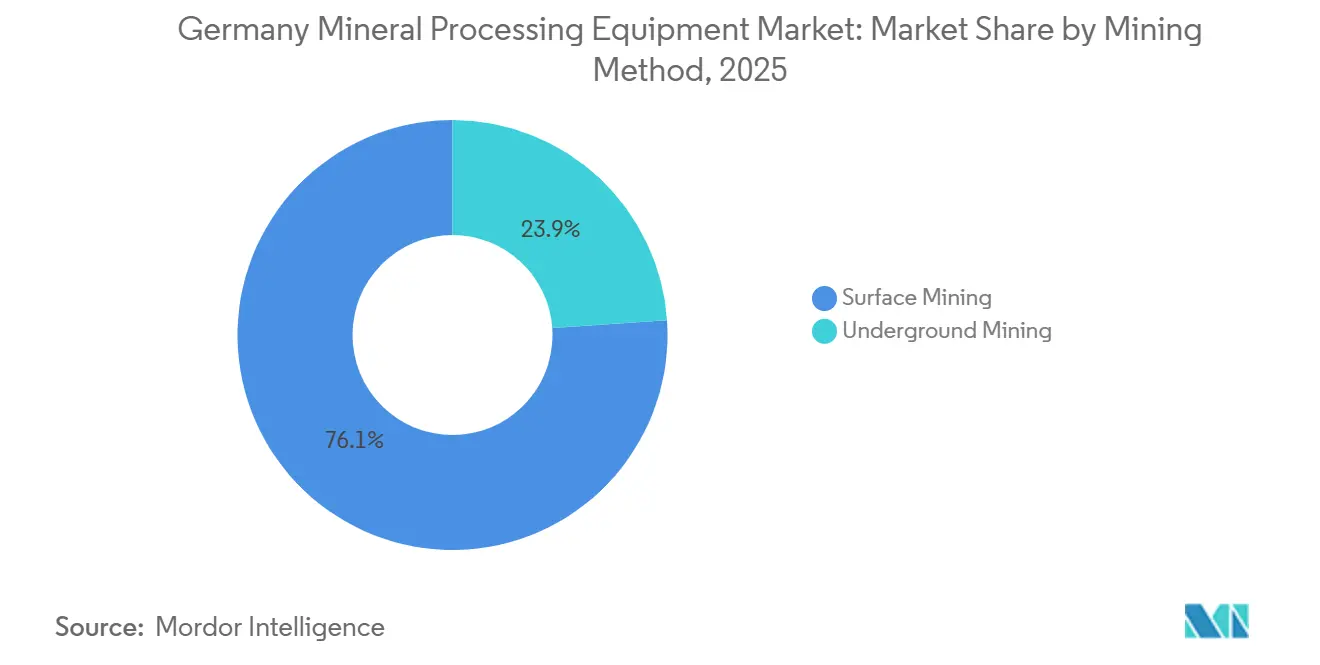
Surface mining accounted for 76.13% of Germany's mineral processing equipment market share in 2025, reflecting the dominance of potash and salt operations situated at shallow depths. Underground installations, however, are projected to expand at a 6.38% CAGR to 2031 as lithium, tungsten, and polymetallic projects advance in Saxony and Thuringia. These subterranean ventures require low-profile crushers, heavy-duty hoists, and real-time ventilation controls that can operate within narrower headings, creating demand for purpose-built German engineering.
Digital twins and autonomous drilling rigs are further improving underground economics by optimizing blast patterns and reducing unplanned downtime. Over time, this technology stack is expected to converge with fully automated load-haul-dump fleets, steadily closing the cost gap with surface extraction. As a result, suppliers capable of integrating software, sensing, and mechanical subsystems are set to win a larger slice of underground contracts in the German mineral processing equipment market.
By Automation Level: Fully Automated Lines Gain Traction
Semi-automated systems retained a 48.17% of Germany's mineral processing equipment market share in 2025, reflecting the prevalence of hybrid plants where operators fine-tune process variables in response to sensor inputs. Fully automated lines are growing at a 6.42% CAGR through 2031 as mines confront a deepening technician shortage and tighter dust-emission rules that restrict manual interventions. Modern flowsheets now specify autonomous gap adjustments in crushers, reagent dosing in flotation, and predictive condition monitoring across conveyors and screens.
Manual setups survive mainly in small pilot plants and legacy quarries, but regulatory tightening and corporate decarbonization pledges are reducing their relevance each budget cycle. Over the forecast window, the German mineral processing equipment market is expected to cross an inflection point where fully automated solutions make up the majority of new installations, aided by falling sensor costs and the availability of cloud-based analytics platforms offered as subscription services.
Geography Analysis
Germany’s mineral-equipment spending is clustering in Saxony, Thuringia, Lower Saxony, and North Rhine-Westphalia. Saxony and Thuringia are the fastest movers due to lithium, tungsten, and rare-earth projects in the Erzgebirge region, which demand underground crushers, hoists, and high-precision flotation cells. Lower Saxony and North Rhine-Westphalia remain the heartland for potash and salt, sustaining a large installed base of crushers, crystallizers, and bulk-handling systems that undergo steady incremental upgrades. Brandenburg is emerging as a lithium-processing hub, hosting converter capacity that will rely on rotary kilns and hydrometallurgical reactors once mechanical erection begins in the near term.
Hesse stands out for its geothermal lithium extraction, which bypasses conventional crushing and grinding and instead relies on ion-exchange columns and crystallization modules that require tight process control. Bavaria and Baden-Württemberg, though lacking active mines, are pivotal engineering centers where mid-tier suppliers prototype screening, conveying, and digital-control technologies later exported worldwide. This east-west divide is steering buyers toward transportable, modular equipment packages that can be commissioned quickly and relocated as new deposits are proven out.
Labor availability is shaping procurement choices across all regions. The Federal Employment Agency lists mechatronics and precision engineering among the top bottleneck occupations, a constraint especially acute in Saxony’s rapidly scaling lithium corridor. As a mitigation, owners prefer hardware that offers remote commissioning and software updates, giving German OEMs with local service hubs a defensible advantage. Over the medium term, equipment demand will track the rollout of critical-mineral projects east of the former Iron Curtain while legacy potash basins provide a stable renewal floor.
Coverage of the mineral processing equipment market by 麻豆视频 spans a wide geographic footprint, with detailed country-level intelligence for Spain, Turkey, South Korea, Argentina, Japan, Mexico, Oman, Egypt, and Morocco, each shaped by local operating conditions.
Competitive Landscape
The German mineral processing equipment market is moderately fragmented, with global majors such as Metso Outotec, Sandvik, FLSmidth, Weir Group, and Komatsu competing alongside German mid-tier specialists, including Thyssenkrupp Industrial Solutions, TAKRAF, Schenck Process, Hazemag, and RHEWUM. Competitive intensity is rising as leading firms narrow their focus to mining: FLSmidth spun off its cement division in 2025, and others are bundling digital services with mechanical hardware to create stickier, data-driven revenue streams.
Domestic mid-sizers leverage deep knowledge of Germany’s ore-body complexity and environmental regulations, enabling them to customize crushing, screening, and handling systems for brownfield retrofits where global platforms may struggle to meet airflow, noise, or dust benchmarks. Technology has become the primary battleground; Sandvik’s AI wear-scanning deck and Hazemag’s real-time torque-monitoring suite illustrate how incremental digital layers differentiate otherwise mature mechanical offerings.
Urban-mining and recycling lines represent a white-space segment where established potash-centric vendors face new challengers specializing in e-waste and battery black-mass processing. Success in this arena depends on the ability to handle heterogeneous feed without cross contamination, favoring suppliers with flexible, high-precision screening and sensor-based ore-sorting equipment. Across all product lines, the pathway to profit now runs through service contracts built on predictive analytics rather than one-off capital sales.
Germany Mineral Processing Equipment Industry Leaders
-
Metso Outotec
-
Sandvik AB
-
FLSmidth A/S
-
Weir Group PLC
-
Komatsu Ltd.
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- January 2026: Metso extended its German service network through Fischer-Jung, facilitating the localized supply of wear parts for construction-recycling customers.
- November 2025: Sandvik named Lutze Process Germany as nationwide distributor for tracked crushers and wheeled processing units.
- March 2025: The European Commission confirmed 47 Critical Raw Material Strategic Projects, allocating EUR 22.5 billion and granting several German lithium, rare-earth, and recycling ventures accelerated permitting.


Germany Mineral Processing Equipment Market Report Scope
The German Mineral Processing Equipment market is analyzed across the mineral mining sector, equipment type, mining method, and automation level.
By Mineral Mining Sector, the market is segmented into Bauxite, Iron, Lithium, Potash & Salt, Rare Earths, and Others. By Equipment Type, the market is segmented into Crushers, Feeders, Conveyors, Drills & Breakers, Screens & Sizers, Grinding Mills, and Others. By Mining Method, the market is segmented into Surface Mining and Underground Mining. By Automation Level, the market is segmented into Manual, Semi-Autonomous, and Fully Autonomous.
Market forecasts are provided in terms of Value (USD) and Volume (Units).
| Bauxite |
| Iron |
| Lithium |
| Potash & Salt |
| Rare Earths |
| Crushers |
| Feeders |
| Conveyors |
| Drills & Breakers |
| Screens & Separators |
| Grinding Mills |
| Others |
| Surface Mining |
| Underground Mining |
| Manual |
| Semi-Automated |
| Fully Automated |
| By Mineral Mining Sector | Bauxite |
| Iron | |
| Lithium | |
| Potash & Salt | |
| Rare Earths | |
| By Equipment Type | Crushers |
| Feeders | |
| Conveyors | |
| Drills & Breakers | |
| Screens & Separators | |
| Grinding Mills | |
| Others | |
| By Mining Method | Surface Mining |
| Underground Mining | |
| By Automation Level | Manual |
| Semi-Automated | |
| Fully Automated |


Key Questions Answered in the Report
How large is the Germany mineral processing equipment market?
The Germany mineral processing equipment market is expected to grow at USD 282.29 million in 2026 and is projected to reach USD 372.27 million by 2031.
Which mineral segment drives growth?
Lithium equipment is growing the fastest, registering a 5.97% CAGR through 2031.
What equipment category holds the biggest share?
Crushers lead with 25.47% of revenue, reflecting their role in first-stage size reduction.
Where are new projects concentrated?
Saxony and Thuringia host most greenfield activity because of critical-mineral deposits and policy incentives.
How are high energy costs influencing purchases?
Operators retrofit conveyors and screens with energy-regenerative drives to cut power bills that remain above 10 cents per kWh.
Page last updated on:



