
Canada Mineral Processing Equipment Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 495.76 Million |
| Market Size (2026) | USD 524.81 Million |
| Market Size (2031) | USD 697.69 Million |
| Growth Rate (2026 - 2031) | 5.86 % |
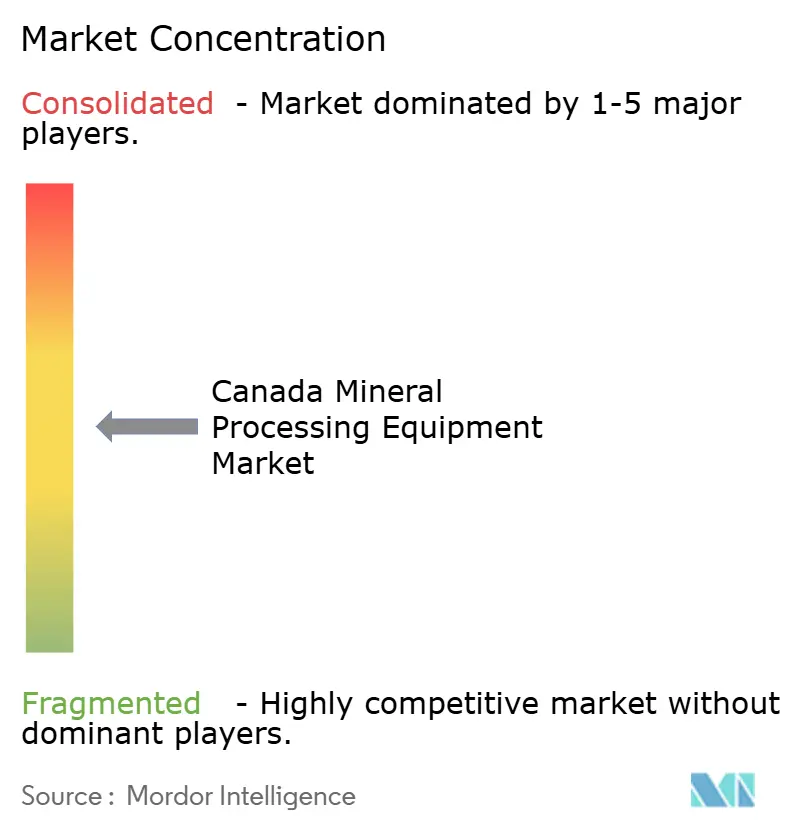
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Canada Mineral Processing Equipment Market Analysis by 麻豆视频
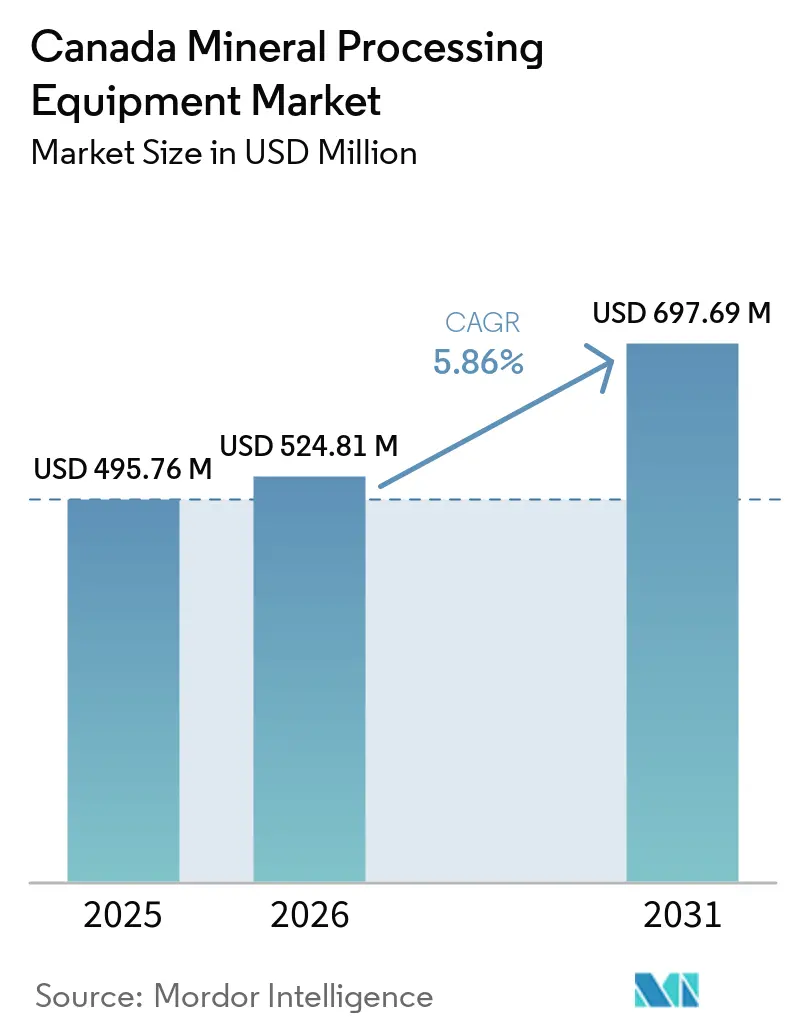
The Canada mineral processing equipment market is projected to grow from USD 495.76 million in 2025 to USD 524.81 million in 2026, reaching USD 697.69 million by 2031. The market is expected to register a CAGR of 5.86% during the forecast period (2026–2031). Federal incentives that favor critical-mineral projects, a wave of automation aimed at offsetting labor shortages, and the electrification push from battery manufacturers collectively keep the Canadian mineral processing equipment market on a steady path of expansion. Demand is tilting toward sensor-rich crushers, mills, and flotation cells that talk to cloud platforms, a shift made easier by vendor financing programs tied to government tax credits. Equipment makers are also tailoring ruggedized cybersecurity layers after publicly reported breaches exposed vulnerabilities in connected plant systems. At the same time, Indigenous equity frameworks shorten permitting cycles for greenfield mines, steering incremental capital toward processing lines for lithium, nickel, and copper.
Key Report Takeaways
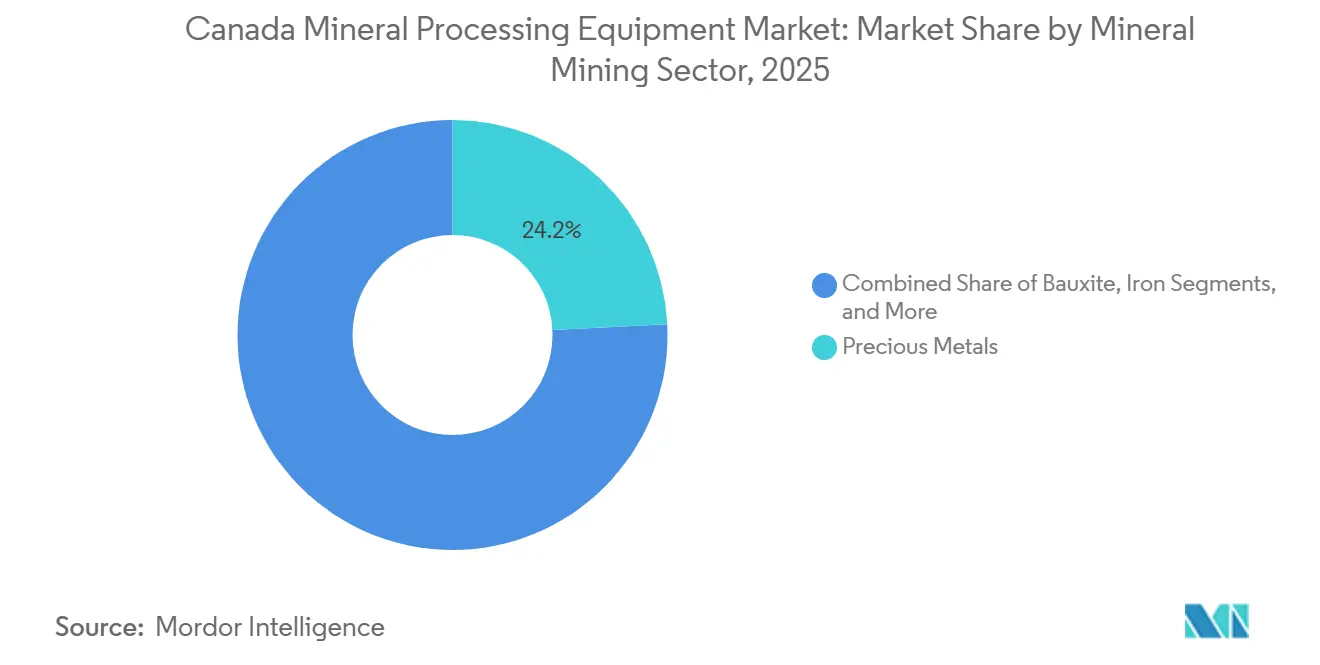
- In the mineral mining sector, precious metals led with 24.16% of Canada's mineral processing equipment market share in 2025, while lithium processing is forecast to grow at a 6.97% CAGR through 2031.
- By equipment type, crushers accounted for 21.83% of the market size in 2025; process control and automation systems represent the fastest-growing bracket at a 6.88% CAGR to 2031.
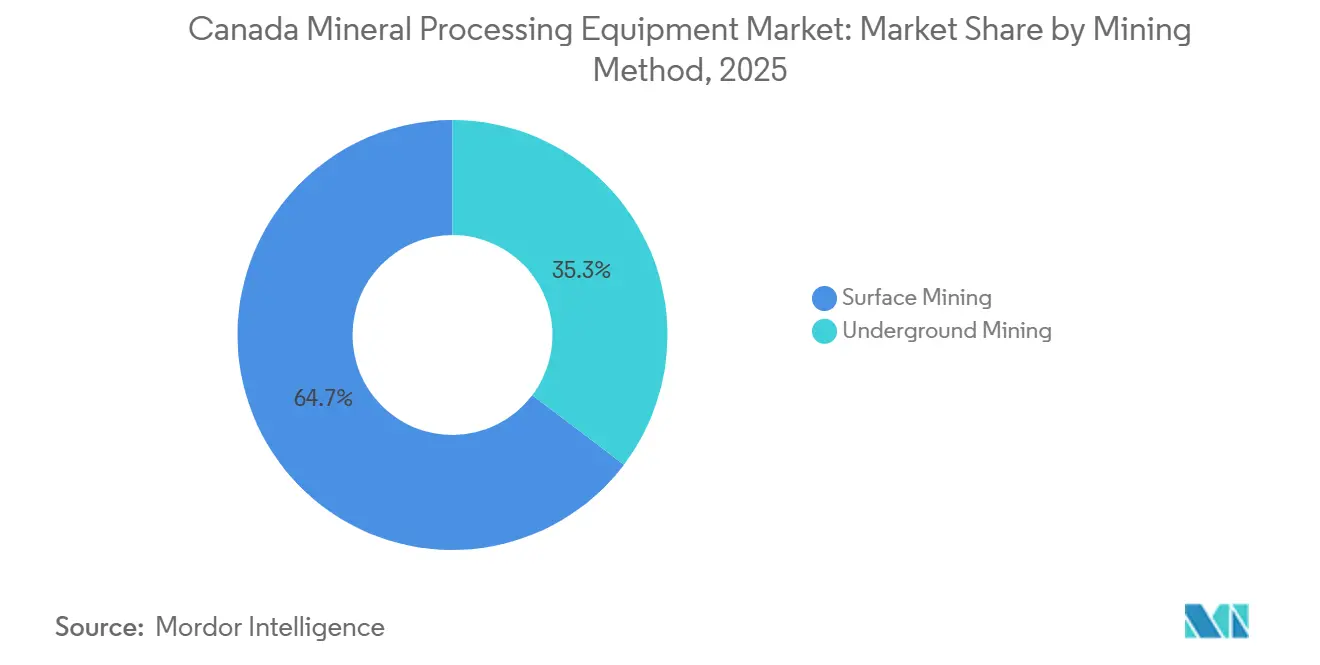
- By mining method, surface operations commanded 64.72% of Canada's mineral processing equipment market share in 2025, yet underground projects are projected to rise at a 6.02% CAGR on the same horizon.
- By automation level, semi-automated rigs accounted for 46.28% of shipments in 2025, while fully automated systems showed the highest momentum, with a 6.04% CAGR toward 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Projections can easily extend beyond country and regional trends as they are defined by movement across the full international system. 麻豆视频's worldwide mineral processing equipment market outlook captures this forward trajectory.
Canada Mineral Processing Equipment Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Federal Critical Minerals Strategy Incentives | +1.4% | Ontario, Quebec, British Columbia, Saskatchewan | Medium term (2-4 years) |
| EV-Battery Gigafactories | +1.3% | Ontario, Quebec | Medium term (2-4 years) |
| Critical-Mineral Demand Surge | +1.1% | Ontario, Quebec, British Columbia | Long term (≥ 4 years) |
| Automation & Digitalization | +0.9% | Ontario, Quebec, British Columbia, Saskatchewan | Short term (≤ 2 years) |
| Indigenous Equity Frameworks | +0.6% | Ontario, Quebec, British Columbia, Saskatchewan, Manitoba | Medium term (2-4 years) |
| Western Canada Hydromet Pilot-Plant Build-Outs | +0.5% | British Columbia, Saskatchewan | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
CAD 3.8 Bn Federal Critical Minerals Strategy Incentives
Grants from the Critical Minerals Infrastructure Fund lower the capital outlay threshold that once deterred junior explorers from ordering large equipment packages[1]"Critical Minerals Infrastructure Fund – Contribution funding", Government of Canada, canada.ca. Sovereign co-investment increases the debt-carrying capacity of greenfield assets, allowing procurement to proceed before full feasibility. Stacked tax credits covering exploration through clean-tech manufacturing further sweeten internal rates of return. Suppliers, in response, structure outcome-based service contracts that align payment to throughput, enabling mines with thin balance sheets to convert capital cost into operating cost. The net effect keeps the Canadian mineral processing equipment market on a multi-year contracting up-cycle even when commodity prices briefly soften.
EV-Battery Gigafactories Ignite Mid-Stream Processing CAPEX
Battery-grade feedstock requires narrow impurity windows, forcing legacy concentrators to retrofit finer grinding circuits and precise flotation controls. Build schedules for gigafactories to compress mine development windows, driving early orders for crushers, mills, and reactors that traditionally waited for bankable feasibility. Equipment backlogs, therefore, stretch into the late-decade, a visibility cushion that encourages vendors to localize parts warehouses and extend credit terms. Processing lines tied to black-mass recycling further diversify demand as circular-economy clauses become standard in provincial funding agreements. Gigafactory footprints also force host regions to bulk up power, rail, and port infrastructure, a spill-over benefit for mining projects entering construction during the same period.
Critical-Mineral Demand Surge from EV Batteries
Automotive producers have locked in long-term offtake agreements, assuring miners of predictable cash flow and nudging them to commit to concentrator expansions earlier in the project cycle. Lithium hydroxide, nickel sulfate, and cobalt intermediates now command premium pricing structures that value reliable chemistry over spot discounts. Developers increasingly specify low-water, sulfate-free flowsheets to pass environmental reviews on the first attempt, a trend that hands process-control suppliers valuable customization revenue. Major battery complexes in Ontario and Quebec have also pledged life-cycle transparency[2]"Canada invests in battery innovation projects in Quebec", Government of Canada, canada.ca, pressing mines to prove material provenance through traceability sensors embedded across crushing, grinding, and flotation lines. Altogether, these factors weave a dependable demand floor that shields the Canadian mineral processing equipment market from the usual boom-and-bust swings.
Automation & Digitalization to Ease Skilled-Labor Crunch
A demographic cliff looms as veteran operators retire faster than the training pipeline refills positions. Mine managers have therefore pivoted from incremental automation pilots to whole-fleet strategies that marry autonomous drilling, haulage, and ore-tracking software in an integrated control room. Real-time data enables predictive maintenance, delaying major rebuilds and reducing the risk of catastrophic mill failures. Equipment suppliers now bundle training modules that upskill local communities, fulfilling social-license obligations while avoiding fly-in labor. As the productivity delta between automated and manual fleets widens, capital allocators view digital platforms as essential plant infrastructure rather than optional bolt-ons.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Commodity-Price Volatility | -0.8% | Ontario, Quebec, British Columbia, Saskatchewan | Short term (≤ 2 years) |
| Carbon-Pricing & Emissions Caps | -0.6% | Ontario, Quebec, British Columbia, Alberta | Medium term (2-4 years) |
| Lengthy Impact-Assessment Timelines | -0.4% | Ontario, Quebec, British Columbia, Saskatchewan | Medium term (2-4 years) |
| Cyber-Security Gaps | -0.2% | Ontario, Quebec, British Columbia | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Commodity-Price Volatility & High Cap-Intensity
Swinging lithium and copper quotes regularly force CFOs to pause or resize expansion plans, drying up the aftermarket for mill liners and spare pumps. When metals fall below incentive prices, junior explorers struggle to close project finance, extending lead times for new concentrator builds. High upfront costs for crushers, grinders, and flotation cells, coupled with long payback periods, magnify exposure to price dips. Suppliers with flexible, outcome-based leasing models partially cushion this restraint, but credit underwriters still demand robust hedge books before releasing funds. Until pricing curves stabilize, procurement departments focus on modular equipment that scales output incrementally rather than megatonne single-line plants.
Federal Carbon-Pricing & Emissions Caps
Escalating carbon levies make diesel-powered drilling or hauling uneconomical in several basins, pushing operators toward electrified or trolley-assist fleets that carry higher sticker prices. Mines located far from high-voltage grids must budget for transmission corridors, a non-core expense that competes with plant upgrades. Regulatory uncertainty around emission ceilings keeps engineering studies in draft form as owners await final benchmarks. Suppliers counter by introducing dual-fuel or battery-swap systems that offer transition flexibility. Nevertheless, carbon pricing adds operating-cost pressure that can defer spending on optional enhancements, limiting the upside of the Canadian mineral processing equipment market until low-carbon technologies mature.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Mineral Mining Sector: Lithium Races Ahead While Precious Metals Provide Stability
Precious-metal operations held 24.16% of Canada's mineral processing equipment market share in 2025, providing a dependable revenue floor for suppliers. Gold and silver miners, concentrated in Ontario and Quebec, favor equipment upgrades that unlock incremental recovery rather than whole-plant replacements, a pattern that produces annuity-style service contracts. Their relatively low throughput allows early adoption of sensor-based ore-sorting and real-time slurry monitoring, technologies that carry premium pricing but quick payback. These mines also pioneer Indigenous procurement models that embed local maintenance crews, a feature that increases equipment uptime by aligning economic interests.
Lithium is expanding at a 6.97% CAGR through 2031, the fastest clip in the Canadian mineral processing equipment market, driven by gigafactory commitments that create a captive domestic offtake. New brine and hard-rock projects bypass evaporation ponds in favor of direct-extraction hydromet reactors, shortening cash-generation timelines. This flowsheet revolution favors modular reactors, enclosed thickeners, and crystallizers sized for phased capacity ramps. Vendors chase aftermarket ties by embedding proprietary chem-control algorithms that adjust reagent dosing in real time, locking clients into long-term platform licenses. As the lithium value chain localizes, procurement managers assign higher weight to delivery assurance, rewarding OEMs that stock parts in Ontario and Quebec.


By Equipment Type: Crushers Dominate Installed Base While Process-Control Suites Lead Growth
Crushers accounted for 21.83% of the Canadian mineral processing equipment market size in 2025, reflecting the country’s historical reliance on open-pit mining, where run-of-mine ore requires rapid size reduction at high tonnage. Fixed-plant primary gyratories stand alongside mobile jaw units that follow satellite pits, ensuring continuous feed to downstream mills. Wear-part suppliers, therefore, secure recurring revenue streams anchored to predictable liner-change schedules. Upgrades now revolve around hydraulic tramp-relief and variable-speed drives that balance throughput with energy draw, an attribute valued under tightening carbon rules.
Process-control and automation systems post the fastest growth at a 6.88% CAGR to 2031, nudging the Canadian mineral processing equipment market toward software-defined productivity. Cloud-connected platforms gather vibration, temperature, and chemical signals, converting them into dispatchable work orders for maintenance teams. Mines pair these systems with digital twins that simulate ore variability, optimizing circuit settings hours before a shovel drops the next bucket of material. OEMs bundle cybersecurity hardening as a standard module, given the uptick in operational-technology breaches. The result is an ecosystem where analytics, rather than steel, underwrites new value creation.
By Mining Method: Surface Projects Still Rule as Underground Builds Momentum
Surface operations retained 64.72% of Canada's mineral processing equipment market share in 2025, reflecting the vast open-pit copper, gold, and iron mines carved across British Columbia, Ontario, and Quebec. Their sheer scale demands high-capacity conveyors, stockpile reclaimers, and primary crushers capable of absorbing variable feed sizes. Environmental scrutiny, however, presses operators to shrink disturbance footprints through in-pit crushing and conveying, shifting haulage from diesel trucks to electric belts. This evolution elevates the role of high-angle systems that slash haul-road dust and energy use.
Underground projects, registering a 6.02% CAGR through 2031, capture incremental share as deeper orebodies push shafts below fossil reef cover. Autonomous loaders operate in confined headings where manual operations face both safety and labor-availability constraints. Mines equipped with wireless mesh networks continuously monitor air quality and repeater health, enabling ventilation-on-demand that reduces power bills. Because underground capital intensity is higher per tonne of ore, owners favor rugged, rebuild-ready machines over disposable fleets, lengthening total aftermarket spend. EPC contractors package refuge, dewatering, and ground-support systems alongside core processing lines, smoothing procurement workflows.
By Automation Level: Semi-Automated Fleets Bridge Toward Full Autonomy
Semi-automated machinery held 46.28% of Canada's mineral processing equipment market share in 2025, offering mines an accessible on-ramp to digital operations without the culture shock of crewless plants. Tele-remote drilling improves utilization in marginal weather, while operator-assist loading platforms shave cycle times yet keep drivers in supervisory cabs. This middle ground allows unions and regulators to assess safety data before approving fully autonomous haulage that removes personnel from active pits.
Fully autonomous systems, forecasted to grow at a 6.04% CAGR to 2031, rely on sensor fusion and AI algorithms that validate obstacle-detection in real time. Mine's adopting such a fleet restructuring work roster to focus on data analysts and software technicians rather than heavy-equipment operators. This shift widens the talent pipeline to include graduates from computer-science departments, mitigating the chronic labor shortfall. Vendors establish long-term service relationships by offering remote operations centers that manage multiple sites from a single dashboard, further redefining the boundaries of the Canada mineral processing equipment industry.
Geography Analysis
Ontario and Quebec form the industrial heartland of the Canadian mineral processing equipment market, thanks to their dense network of nickel, gold, and emerging lithium deposits. Established smelting and refining corridors streamline concentrate logistics, lowering project risk for new entrants. Provincial road grants that connect isolated claims to railheads improve the economic case for modular crushing plants. Indigenous equity partnerships also find fertile ground here, creating community-based maintenance hubs that raise equipment uptime. The region’s existing high-voltage grid supports electrified crushers and trolley-assist haulage, aligning plant designs with forthcoming carbon caps.
British Columbia and Saskatchewan together anchor Western Canada’s share of the Canadian mineral processing equipment market. In the mountainous terrain of British Columbia, steep-incline conveying and high-pressure grinding rolls handle complex copper-gold porphyries while minimizing blast vibrations near sensitive ecosystems. Saskatchewan adds a layer of uranium and potash expertise, attracting automation pilots that test battery-electric loaders in radiation-controlled headings. Hydromet pilot campaigns in both provinces supply valuable data that short-lists vendors for future commercial builds. Equipment firms respond by situating service warehouses closer to these provinces, slashing response time for parts dispatch.
Alberta and Manitoba, though smaller contributors, wield strategic importance because they fast-track underground automation case studies. Limestone and base-metal producers in Alberta pioneer semi-autonomous jumbos that one supervisor can manage from a safe bunker, cutting shift counts without sacrificing output. Manitoba’s deep polymetallic shafts serve as training grounds for battery-electric loaders that halve ventilation demand, a win under federal carbon pricing. Suppliers gain incremental aftermarket revenue from refurbishing diesel fleets into hybrid carriers destined for secondary headings. Collectively, these provinces add depth and resilience to the Canada mineral processing equipment market by diversifying regional demand drivers.
The mineral processing equipment market is analyzed by 麻豆视频 across multiple other geographies. This is complemented by country-specific insights for Mexico, Brazil, South Korea, Argentina, Turkey, Japan, Oman, Egypt, and Morocco, reflecting various localized market behavior and policy environments' coverage.
Competitive Landscape
First-tier suppliers, Metso Outotec, Sandvik, FLSmidth, Caterpillar, and Sepro Mineral Systems, shape a moderately concentrated Canadian mineral processing equipment market, yet no single player dominates every equipment class. Each frontrunner hedges concentration risk by forging alliances with software specialists that deliver cloud monitoring and digital twins. This partnership web transforms discrete machinery sales into data-subscription models that bundle analytics, parts, and remote troubleshooting. As contracts shift from lump-sum to outcome-based frameworks, revenue predictability improves even while initial capital shrinks.
Mid-tier challengers exploit open niches in sensor-based ore sorting and lithium hydromet reactors. Their R&D cycles spin faster than those of diversified OEMs, allowing rapid adaptation to client feedback on trace-element control or reagent consumption. Indigenous-owned distributors further fragment the aftermarket by leveraging procurement allowances in federal funding rules. These distributors often co-brand with global suppliers, supplying localized training that meets community-employment covenants and safeguarding social licenses.
Digital-security integrators enter the playing field as mines extend Wi-Fi, LTE, and private 5G into faces and chambers. Recent breaches that shut mills for days have primed owners to allocate cybersecurity budgets previously absent from plant OPEX. Equipment vendors that embed secure-by-design controllers win preference over retrofitted solutions. Market incumbents therefore accelerate acquisitions of niche security firms to seal this gap, consolidating yet another value layer inside the Canada mineral processing equipment industry.
Canada Mineral Processing Equipment Industry Leaders
-
Metso Outotec
-
Sandvik AB
-
FLSmidth A/S
-
Caterpillar Inc.
-
Sepro Mineral Systems
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- January 2025: Metso introduced its RockSense particle-size analyzer at the Blackwater mine, enabling real-time mill optimization that feeds adaptive grinding controls.
- October 2025: Metso launched an outcome-based Life Cycle Services tier for Canadian concentrators, promising fixed-price uptime commitments tied to sensor analytics.
- May 2025: Canada Growth Fund committed USD 111 million to Foran Mining’s McIlvenna Bay project, accelerating plant-equipment procurement.
- March 2025: Metso introduced a copper-sulfide concentrate leach process that delivers high copper recoveries with reduced environmental impact.


Canada Mineral Processing Equipment Market Report Scope
The Canadian Mineral Processing Equipment market is analyzed across the mineral mining sector, equipment type, mining method, and automation level.
By Mineral Mining Sector, the market is segmented into Bauxite, Iron, Lithium, Copper, Nickel, Precious Metals, and Others. By Equipment Type, the market is segmented into Crushers, Grinding Mills, Feeders & Conveyors, Drills & Breakers, Screens & Sizers, Flotation Cells, Hydrocyclones, Thickening & Dewatering, Process Control, and Others. By Mining Method, the market is segmented into Surface Mining and Underground Mining. By Automation Level, the market is segmented into Manual, Semi-Autonomous, and Fully-Autonomous.
Market forecasts are provided in terms of Value (USD) and Volume (Units).
| Bauxite |
| Iron |
| Lithium |
| Copper |
| Nickel |
| Precious Metals (Gold, Silver, PGMs) |
| Others |
| Crushers |
| Grinding Mills |
| Feeders & Conveyors |
| Drills & Breakers |
| Screens & Classifiers |
| Flotation Cells |
| Hydrocyclones & Pumps |
| Thickening & Dewatering |
| Process Control & Automation Systems |
| Others |
| Surface Mining |
| Underground Mining |
| Manual |
| Semi-Automated |
| Fully-Automated |
| By Mineral Mining Sector | Bauxite |
| Iron | |
| Lithium | |
| Copper | |
| Nickel | |
| Precious Metals (Gold, Silver, PGMs) | |
| Others | |
| By Equipment Type | Crushers |
| Grinding Mills | |
| Feeders & Conveyors | |
| Drills & Breakers | |
| Screens & Classifiers | |
| Flotation Cells | |
| Hydrocyclones & Pumps | |
| Thickening & Dewatering | |
| Process Control & Automation Systems | |
| Others | |
| By Mining Method | Surface Mining |
| Underground Mining | |
| By Automation Level | Manual |
| Semi-Automated | |
| Fully-Automated |


Key Questions Answered in the Report
How large is the Canada mineral processing equipment market in 2026?
The Canada mineral processing equipment market is projected to grow from USD 495.76 million in 2025 to USD 524.81 million in 2026, reaching USD 697.69 million by 2031. The market is expected to register a CAGR of 5.86% during the forecast period (2026–2031).
Which equipment category shows the fastest growth momentum?
Process-control and automation suites lead growth, expanding at a 6.88% CAGR as operators prioritize productivity software over new steel.
Why are operators rolling out autonomous and semi-autonomous fleets?
Automation helps offset a looming skilled-labor shortfall and improves safety, while data analytics trim unplanned downtime and lengthen component life.
Where are most of the lithium processing projects being developed?
Ontario and Quebec host the bulk of emerging lithium hubs, driven by direct-extraction flowsheets that feed nearby battery cell plants.
Page last updated on:



