
Brazil Mineral Processing Equipment Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 480.32 Million |
| Market Size (2026) | USD 515.29 Million |
| Market Size (2031) | USD 732.22 Million |
| Growth Rate (2026 - 2031) | 7.28 % |
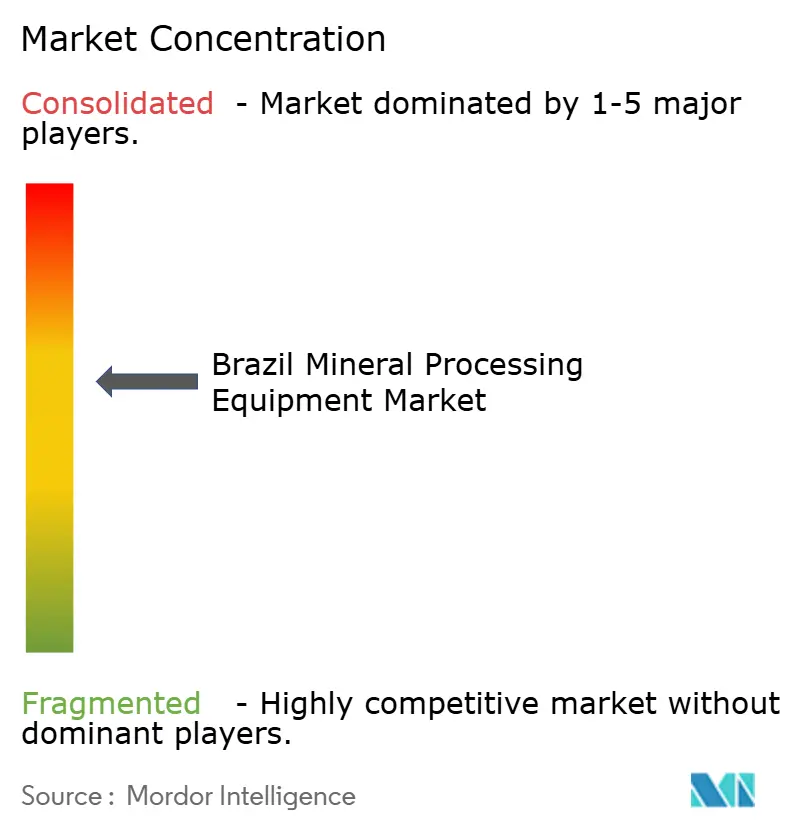
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Brazil Mineral Processing Equipment Market Analysis by 麻豆视频
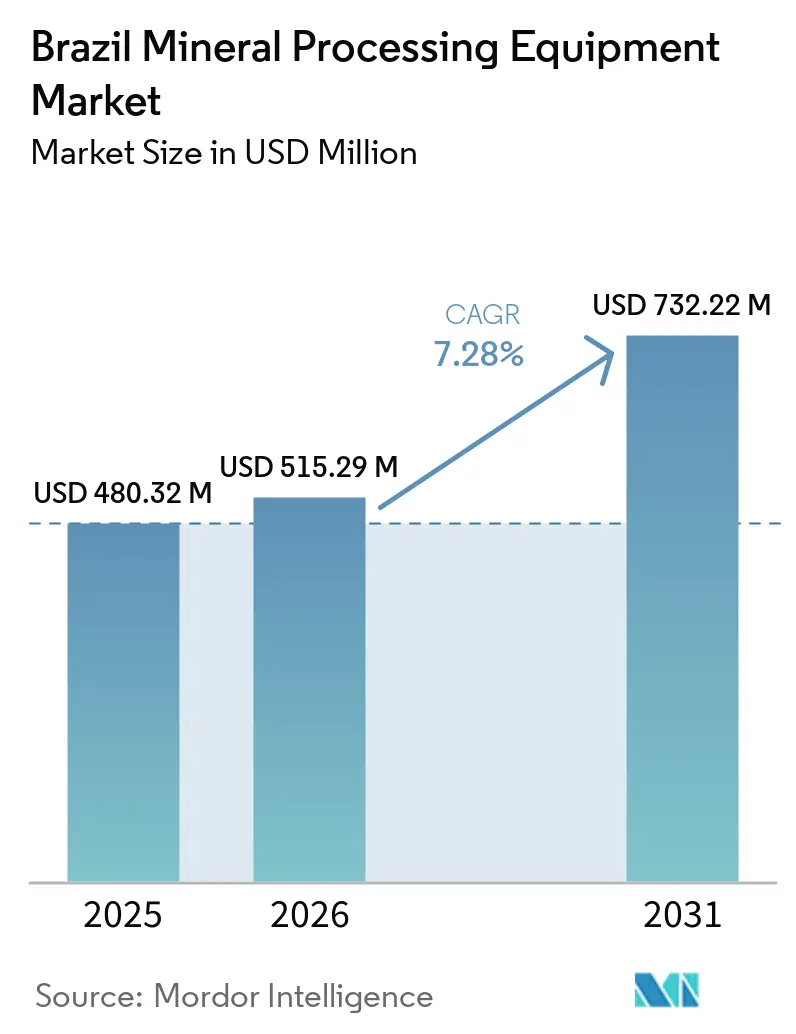
The Brazil mineral processing equipment market size was valued at USD 480.32 million in 2025 and is projected to grow from USD 515.29 million in 2026 to USD 732.22 million by 2031, at a CAGR of 7.28% from 2026 to 2031. Growth reflects Brazil’s simultaneous role as an iron-ore stronghold and a rising source of battery-grade minerals. Procurement decisions increasingly revolve around automation mandates, tailings-safety compliance, and the energy transition’s appetite for lithium and nickel concentrates. Surface operations in Pará and Minas Gerais continue to anchor replacement cycles for crushers and conveyors. Yet, emerging lithium projects in the Jequitinhonha Valley are steering budgets toward flotation cells and high-pressure grinding rolls for treating hard-rock spodumene ore. Suppliers able to pre-assemble skid-mounted plants and bundle life-cycle services now have an edge, as compressed shutdown windows make rapid installation critical to sustaining throughput.
Key Report Takeaways
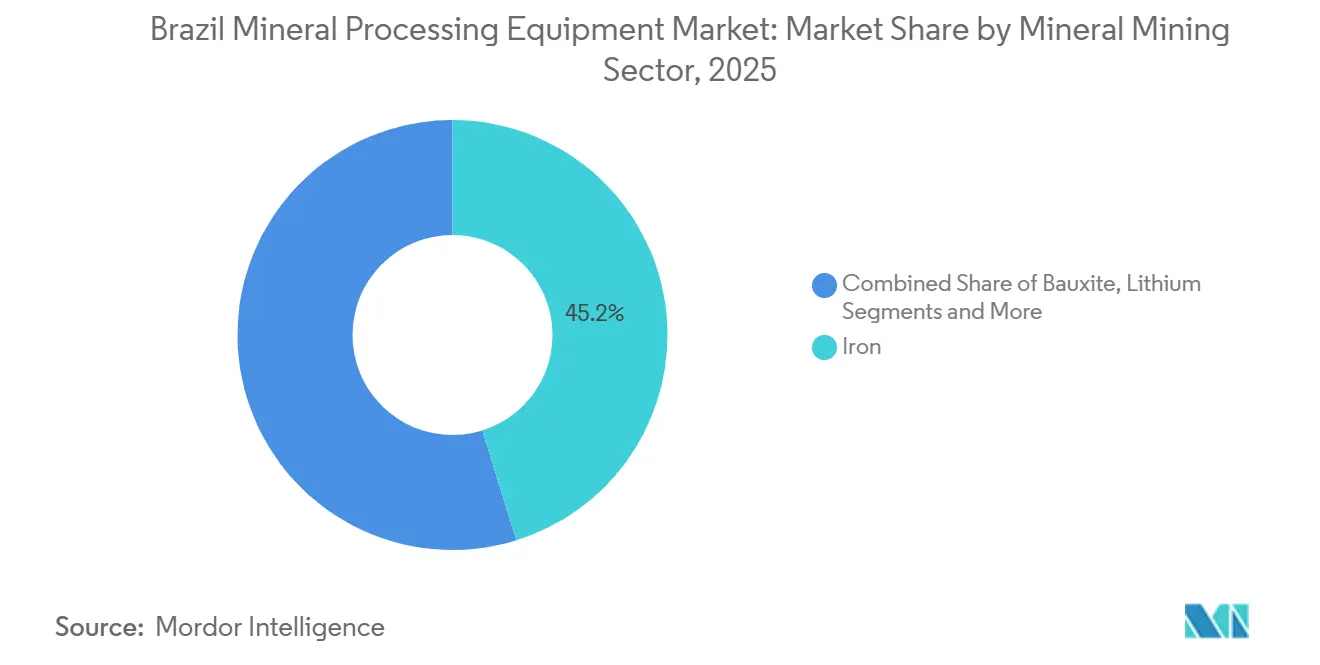
- By mineral mining sector, iron ore led with 45.19% of Brazil's mineral processing equipment market share in 2025, while lithium is projected to expand at an 11.97% CAGR through 2031.
- By equipment type, crushers commanded a 25.38% share of the Brazilian mineral processing equipment market in 2025, whereas flotation cells are projected to register the fastest growth at a 9.01% CAGR through 2031.
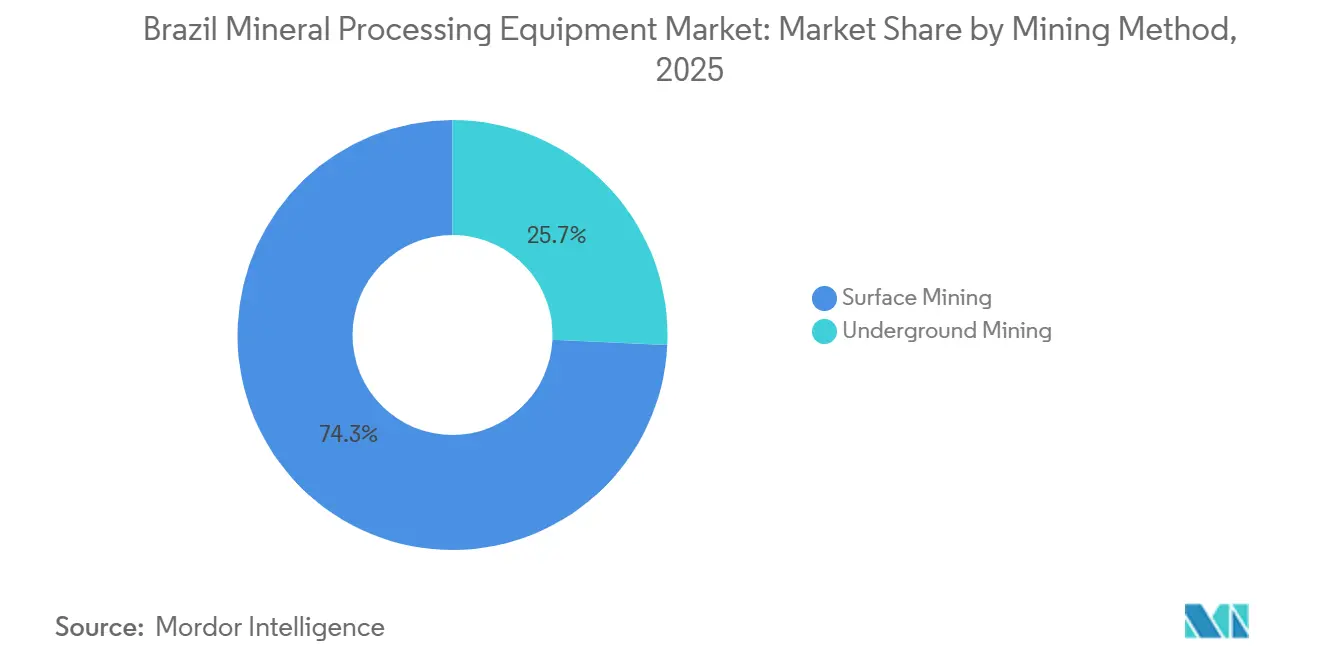
- By mining method, surface operations accounted for 74.26% of Brazil's mineral processing equipment market share in 2025; underground mining is forecasted to grow at a 11.01% CAGR through 2031.
- By automation level, manual systems accounted for 62.28% of Brazil's mineral processing equipment market share in 2025, while fully automated solutions are set to grow at a 11.44% CAGR through 2031.
- By region, the Southeast Brazil region accounted for 41.19% share of the Brazilian mineral processing equipment market in 2025; the Northern Brazil is projected to grow the fastest at an 8.63% CAGR over 2026-2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
National developments in Brazil connect differently with activity unfolding across other parts of the world. In the global mineral processing equipment market coverage, 麻豆视频 integrates these into a single analytical framework.
Brazil Mineral Processing Equipment Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increasing Mineral Production Volumes | +2.1% | Pará, Minas Gerais, Goiás | Medium term (2-4 years) |
| Government Incentives and Fast-Track Licensing | +1.4% | National | Short term (≤2 years) |
| Critical-Energy-Transition Minerals | +1.2% | Minas Gerais, Pará, Goiás | Long term (≥4 years) |
| OPEX Cut by Digital-Twin Retrofits | +0.9% | Pará, Minas Gerais | Medium term (2-4 years) |
| Tailings-Dam Safety Upgrades | +0.8% | Minas Gerais, Pará | Medium term (2-4 years) |
| ESG-Linked Financing | +0.6% | National | Short term (≤2 years) |
| Source: 麻豆视频 | |||
Increasing Mineral Production Volumes (Iron, Bauxite, Lithium)
Brazilian producers continue to lift run-of-mine output on iron, copper, nickel, and lithium, sustaining year-round demand for replacement and expansion equipment. Restarting high-throughput iron-ore complexes in Minas Gerais sparked new orders for conveyors and gyratory crushers to handle 15 million tonnes of annual output. Lithium growth, led by hard-rock projects in the Jequitinhonha Valley, requires dense-media separators and flotation lines configured for spodumene concentrate. Producers ramping up copper and nickel output in Pará are now specifying high-pressure grinding rolls for finisher circuits to unlock lower-grade ore blocks. The National Mining Agency’s latest licensing rounds have opened additional areas for strategic minerals, signaling multi-year pipelines for greenfield plants[1]Silva, G.F.; Silva, A. D. R.; Souza Gaia, S. M., "AN OVERVIEW OF CRITICAL AND STRATEGIC MINERALS POTENTIAL OF BRAZIL", Geological Survey of Brazil, lithium-triangle-southamerica.com. Each new approval adds pressure on OEMs to shorten delivery lead times and strengthen local service centers.
Government Incentives and Fast-Track Licensing (PMI, Decree 11.120/22)
Decree 11.120/2022 eliminated earlier state-monopoly barriers to lithium exploration and formalized an accelerated permitting channel for battery-grade projects [2]"Decree No. 11.120: allowing the foreign trade of lithium and its derivatives", International Energy Agency, iea.org. Subsequent inter-agency coordination has begun to harmonize IBAMA and state environmental reviews, trimming duplicate documentation. Early users of the pathway secured operating licenses several months earlier than historical averages, translating directly into earlier equipment purchase commitments. Rising royalty receipts now fund technical training programs, expanding the pool of operators certified on autonomous haulage and digital control platforms. In parallel, Congressional debate on a National Critical Minerals Policy has lent long-term clarity to investors, further supporting procurement momentum.
Surge in Demand for Critical-Energy-Transition Minerals
Western battery and renewable-technology supply chains increasingly depend on diversified sources of lithium, nickel, and copper. Brazilian concentrators have responded by installing complex beneficiation lines that exceed the process complexity of bulk iron-ore plants. Copper-nickel operations in Pará adopted rotary-kiln electric-furnace flowsheets, driving purchases of large-diameter dryers, kilns, and wet scrubbers. Rare-earth projects in Goiás now trial magnetic and gravity separators calibrated for monazite and ionic clay feedstocks. OEMs integrating digital-twin monitoring and renewable-power interfaces into plant packages are positioned to win future critical-mineral orders.
Automation and Digital-Twin Retrofits Cut OPEX by 10-15%
Vale plans to significantly expand its autonomous truck fleet by the end of the forecast period, aiming to achieve substantial reductions in tire wear and fuel consumption. This expansion is expected to validate the scalability and payback of automation retrofits. Parallel contracts for AutoMine-ready surface drills illustrate that fully driverless technology is moving beyond haulage into drilling and loading. WEG’s sensor suite reduced maintenance costs at a zinc mine by a minimal margin, offering a replicable template for predictive analytics across crushing and grinding circuits [3]"WEG monitoring solutions enable preventive and corrective actions in the mining sector", Smart Water Magazine, smartwatermagazine.com. As more mines view automation as a hedge against labor shortages, suppliers combining hardware, software, and maintenance services gain recurring revenue streams.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Tightening Carbon-Tax Discussions | -1.1% | National, with delays in Pará, Minas Gerais | Long term (≥4 years) |
| Chronic Rail and Port Bottlenecks | -0.8% | Pará (Carajás-Ponta da Madeira), Minas Gerais-Espírito Santo (EFVM-Tubar?o) | Long term (≥4 years) |
| High Industrial Electricity Tariffs | -0.5% | National | Medium term (2-4 years) |
| Shortage of Cyber-Skilled Technicians | -0.4% | Pará, Minas Gerais | Long term (≥4 years) |
| Source: 麻豆视频 | |||
Tightening Environmental Licensing and Carbon-Tax Discussions
Brazil’s mining projects continue to navigate multi-year environmental reviews, extending payback calculations and delaying equipment orders. Proposed carbon-pricing frameworks could add multi-million-dollar cost lines to energy-intensive crushing and grinding operations. With mining excluded from simplified licensing pathways, OEMs must factor extended bid validity and financing cushions into commercial proposals. The resulting uncertainty disincentivizes smaller producers from adopting advanced process routes, slowing the diffusion of technology across the long tail of mines.
Chronic Rail and Port Bottlenecks Raise Delivered-Equipment Costs
Key bulk-freight corridors, notably the Carajás Railway and Port Ponta da Madeira, operate near nameplate capacity. Any outage reverberates through equipment logistics, forcing suppliers to overstock parts or charter higher-cost road freight. Komatsu and other OEMs have responded by localizing component machining and rebuild centers to mitigate transit risks. Still, until rail concessions expand or new terminals come online, large plants face elevated contingency premiums on imported mills, kilns, and drives.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Mineral Mining Sector: Lithium’s Premium Drives Flotation Upgrades
Iron ore currently holds the largest share, at 45.19%, of the Brazilian mineral processing equipment market, reflecting its entrenched production base in Pará and Minas Gerais. Producers continue to replace high-wear crushing and screening circuits to maintain export volumes. The reliability imperative favors modular stations assembled within restricted shutdown windows. Vendors achieving rapid brownfield tie-ins win contracts because every hour offline equates to lost rail-slot revenue. Ancillary orders for conveyor condition-monitoring and dust suppression accompany core crusher replacements, strengthening aftermarket pipelines.
Lithium is the fastest-expanding subsector, advancing at a 11.97% CAGR on the back of spodumene projects in the Jequitinhonha Valley. New hard-rock concentrators favor high-pressure grinding rolls and optimized flotation flowsheets that drive recoveries while minimizing reagent consumption. As lithium players commit to low-carbon supply chains, equipment packages increasingly include renewable-energy interfaces and digital-twin process control. This technical premium widens supplier differentiation, rewarding firms with proven references in battery minerals.


By Equipment Type: Modular Crushing Stations Compress Installation Cycles
Crushers dominate the Brazilian mineral processing equipment market with a 25.38% share, owing to iron ore debottlenecking campaigns that are replacing aging primary stations. The ability to mobilize fully assembled modules by road or rail has become a decisive factor in purchase awards. Mines demand minimal foundation work and plug-and-play electrical systems to fit within narrow shutdown windows. Such constraints spur the rise of prefabricated skids complete with feeders and screens.
Flotation cells register the quickest climb, recording a 9.01% CAGR as producers re-treat old tailings and commission new lithium and nickel concentrators. Cells equipped with energy-efficient motors and froth-camera vision are preferred for their ability to cut reagent bills. Upgraded drives enable impeller-speed optimization and the lifting recovery of fine sulfides. OEMs pairing cell supply with motor health monitoring tap recurring service revenue and strengthen customer lock-in.
By Mining Method: Underground Copper Drives Autonomous Drill Demand
Surface operations retain the highest share, at 74.26%, of the Brazilian mineral processing equipment market due to the dominance of open-pit iron ore complexes in Carajás and Minas Gerais. In-pit crushing and conveying networks continue to replace diesel haulage, trimming emissions and reducing operating spend. The logistical scale of these sites sustains steady demand for belt splicing, idlers, and drive upgrades across multi-kilometer conveyors.
Underground mining is posting the sharpest growth, with a 11.01% CAGR, as deepening copper orebodies in Pará require autonomous loaders and cable-bolting rigs that thrive in confined headings. Capital intensity pushes operators toward equipment packages that integrate digital mine planning, ground-support analytics, and fleet-management dashboards. Efficient ventilation and battery-electric platforms are gaining traction as part of broader decarbonization efforts.
By Automation Level: Fully Automated Systems Gain Share Despite Skills Gaps
Manual systems still account for 62.28% of the Brazilian mineral processing equipment market, reflecting a large installed base of conventional crushers and haul trucks. Budget-constrained mines opt to retrofit condition-monitoring sensors rather than leap to full autonomy. OEMs, therefore, bundle low-cost gateway devices that feed cloud dashboards, enabling a gradual digital migration.
Fully autonomous solutions experience the strongest uptick at an 11.44% CAGR as flagship producers extend driverless fleets and remote-operated drills across iron and copper pits. Early adopters showcase double-digit productivity gains, persuading lenders to finance similar projects. Training academies jointly run by OEMs and universities aim to address the technician shortage, ensuring that installed fleets meet performance guarantees.
Geography Analysis
Southeast Brazil, anchored by Minas Gerais, leads current demand, capturing 41.19% of Brazil's mineral processing equipment market share in 2025, owing to dense clusters of iron ore, lithium, and gold mines. Suppliers benefit from Belo Horizonte’s engineering talent pool and easy road access, enabling fast turnaround on rebuilds and component swaps. Autonomous haulage pilots in Itabira and Brucutu highlight the region’s readiness to absorb advanced technology. State-level policy incentives further encourage tailings reprocessing, keeping dewatering equipment workshops busy. Continuous investments in training centers cultivate a pipeline of operators certified on digital control rooms.
The Northern Brazil region, dominated by Pará, is the fastest-growing region, with an 8.63% CAGR, as Carajás iron ore operations and Salobo copper expansions adopt large, autonomous fleets. OEMs have begun localizing service hubs in Parauapebas to cut lead times and sidestep congested ports. Remote sites prioritize equipment ruggedness and remote support capabilities because extreme rainfall complicates travel for on-site technicians. Developments in high-throughput relocatable crushers at S11D demonstrate the region’s appetite for innovation that extends pit life while curbing diesel use. The interplay of abundant renewable power and critical mineral deposits positions Pará as a testing ground for carbon-neutral flowsheets.
The Central-West, Southern, and Northeast Brazil collectively form a diversified cluster of phosphate, nickel laterite, and bauxite operations. Goiás pilots activated clay plants that harness waste heat and draw on renewable grids, requiring specialized kilns with low-NOx burners. Southern coal and iron ore mines trial semi-automated conveyor-inspection drones to prolong belt life. Although smaller in revenue terms, these regions present white-space opportunities for mid-tier OEMs that bundle equipment with operator training and remote troubleshooting. Regional development banks increasingly tie loan disbursements to equipment packages that embed energy-efficiency guarantees, reinforcing the push toward high-spec machinery.
For the mineral processing equipment market, country-specific intelligence is available for Argentina, Mexico, China, Canada, Germany, France, Spain, South Korea, and Turkey, each offering a view on the jurisdiction-level dynamics as applicable.
Competitive Landscape
Market concentration is moderate, as the five largest suppliers account for a significant share of revenue in Brazil's mineral processing equipment market. Their edge stems from modular-plant libraries and multi-year service agreements that lock customers into proprietary ecosystems. Metso’s rapid-install FIT stations and FLSmidth’s semi-mobile sizers illustrate the premium miners place on fast commissioning. These platforms shorten payback periods by curbing construction risk.
Sandvik has strengthened its position by combining hardware with AutoMine automation suites. The January 2026 order for 16 surface drills included full-life tool supply and remote-monitoring warranties, increasing client switching costs. Komatsu complements this strategy with localized rebuild centers that slash logistics expenses and strengthen customer retention. The blended model of hardware plus embedded software drives recurring revenues and stabilizes aftermarket margins.
Domestic innovator WEG differentiates through custom motors and predictive-maintenance sensors that slot into flotation and grinding lines. Its ability to retrofit competitors’ equipment widens the addressable installed base. Smaller disruptors now promote interoperable autonomy kits that retrofit mixed fleets, threatening to erode OEM lock-in. Meanwhile, demand for tailings dewatering and reprocessing creates opportunities for niche vendors specializing in paste thickeners and dry stacks.
Brazil Mineral Processing Equipment Industry Leaders
-
FLSmidth A/S
-
Sandvik AB
-
The Weir Group PLC
-
Komatsu Ltd.
-
Metso Corporation
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- January 2026: FLSmidth commissioned an 11,500-ton-per-hour semi-mobile crushing station at the S11D mine to support pit advancement and enhance the mine’s material handling and crushing capacity.
- January 2026: Sandvik secured an order from Vale Base Metals for 16 AutoMine-ready surface drills, with deliveries scheduled through 2027. The order supports Vale Base Metals’ efforts to enhance automation capabilities and improve operational efficiency in its surface mining operations.
- October 2025: Metso launched its Life Cycle Services model at Exposibram, enabling mining companies to outsource performance target management to the OEM. The model supports a more integrated service approach by allowing Metso to assume responsibility for meeting agreed operational performance objectives throughout the equipment life cycle.


Brazil Mineral Processing Equipment Market Report Scope
The Brazil Mineral Processing Equipment market is analyzed across the mineral mining sector, equipment type, mining method, automation level, and region.
By Mineral Mining Sector, the market is segmented into Bauxite, Iron, Lithium, Nickel, Copper, and Others. By Equipment Type, the market is segmented into Crushers, Feeders, Conveyors, Grinding Mills, Screening Equipment, Flotation Cells, Magnetic & Gravity Separators, Tailings Management, Drills & Breakers, and Others. By Mining Method, the market is segmented into Surface Mining and Underground Mining. By Automation Level, the market is segmented into Manual, Semi-Automatic, and Fully Autonomous. By Region, the market is segmented into Northern Brazil, Northeast Brazil, Southeast Brazil, Southern Brazil, and Central-West Brazil. Market forecasts are provided in terms of Value (USD).
| Bauxite |
| Iron |
| Lithium |
| Nickel |
| Copper |
| Others |
| Crushers |
| Feeders |
| Conveyors |
| Grinding Mills |
| Screening & Classification |
| Flotation Cells |
| Magnetic & Gravity Separators |
| Tailings Management Systems |
| Drills & Breakers |
| Others |
| Surface Mining |
| Underground Mining |
| Manual |
| Semi-Automated |
| Fully Automated |
| Northern Brazil |
| Northeast Brazil |
| Southeast Brazil |
| Southern Brazil |
| Central-West Brazil |
| By Mineral Mining Sector | Bauxite |
| Iron | |
| Lithium | |
| Nickel | |
| Copper | |
| Others | |
| By Equipment Type | Crushers |
| Feeders | |
| Conveyors | |
| Grinding Mills | |
| Screening & Classification | |
| Flotation Cells | |
| Magnetic & Gravity Separators | |
| Tailings Management Systems | |
| Drills & Breakers | |
| Others | |
| By Mining Method | Surface Mining |
| Underground Mining | |
| By Automation Level | Manual |
| Semi-Automated | |
| Fully Automated | |
| By Region | Northern Brazil |
| Northeast Brazil | |
| Southeast Brazil | |
| Southern Brazil | |
| Central-West Brazil |


Key Questions Answered in the Report
How large will the Brazil mineral processing equipment market?
The Brazil mineral processing equipment market size was valued at USD 480.32 million in 2025 and is projected to grow from USD 515.29 million in 2026 to USD 732.22 million by 2031, at a CAGR of 7.28% from 2026 to 2031.
What is the forecasted CAGR for equipment demand between 2026 and 2031?
The market is projected to expand at a 7.28% CAGR over the period.
Which mineral segment dominates equipment purchases in 2025?
Iron ore leads, holding 45.19% of market share in 2025.
Which equipment type is growing fastest?
Flotation cells post the highest growth, advancing at a 9.01% CAGR through 2031.
Page last updated on:



