
South Korea Mining Equipment Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 1.69 Billion |
| Market Size (2026) | USD 1.78 Billion |
| Market Size (2031) | USD 2.34 Billion |
| Growth Rate (2026 - 2031) | 5.61 % |
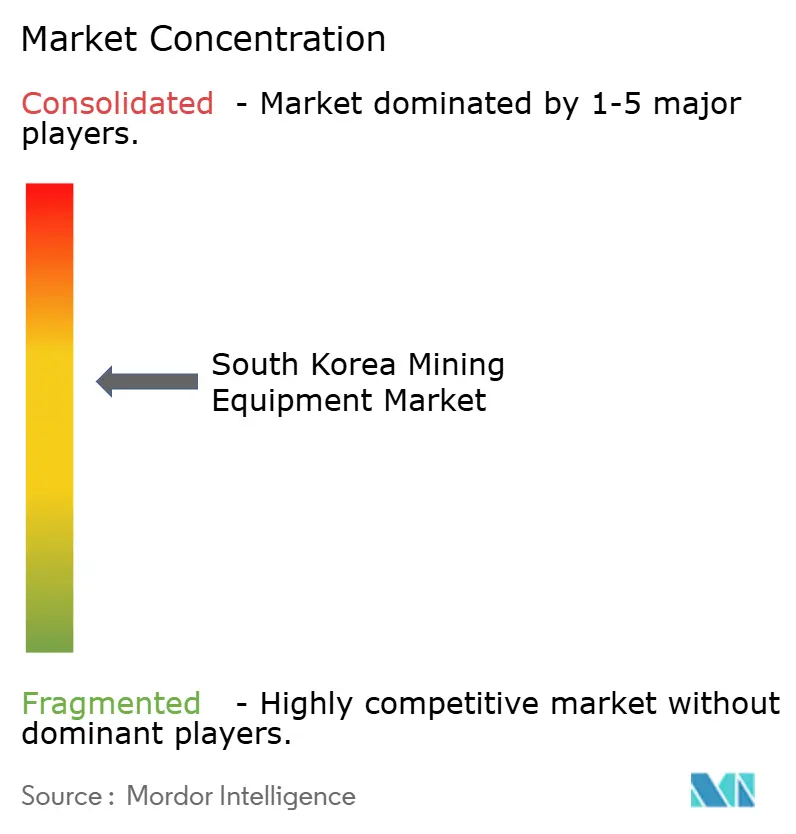
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
South Korea Mining Equipment Market Analysis by 麻豆视频
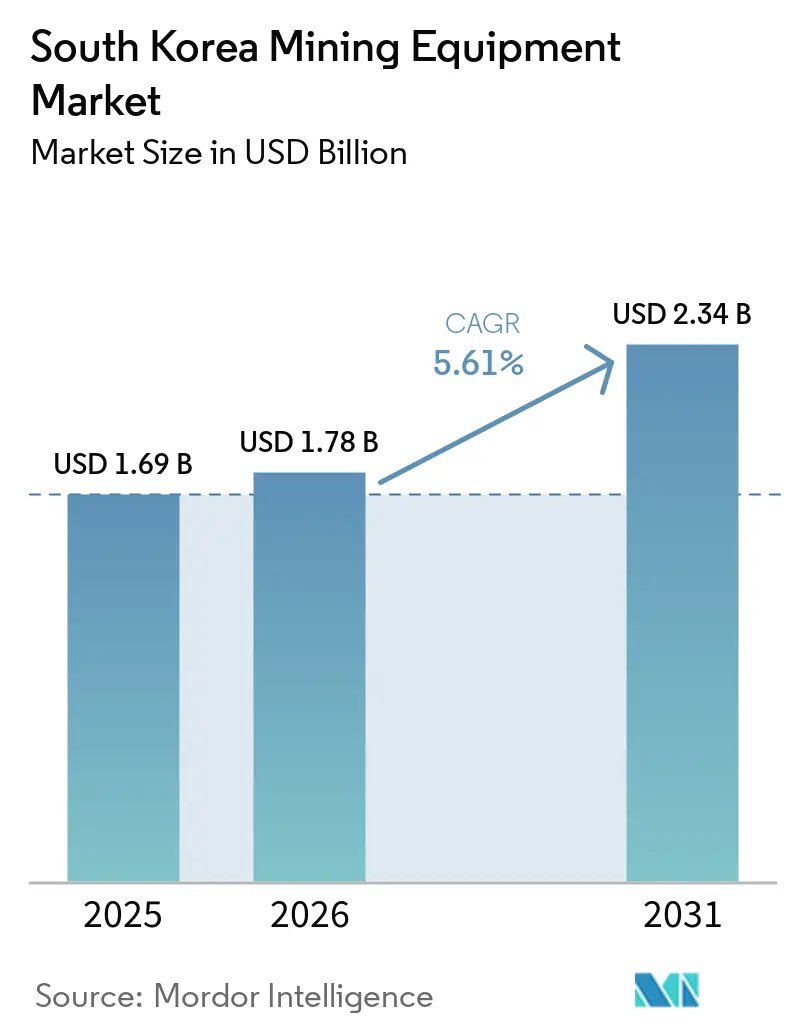
The South Korean mining equipment market is expected to grow from USD 1.69 billion in 2025 to USD 1.78 billion in 2026, and is forecast to reach USD 2.34 billion by 2031 at a CAGR of 5.61%. This trajectory reflects Seoul's pivot toward critical minerals self-sufficiency and the cascading capital demands of LG Energy Solution and SK On, whose combined multi-billion-dollar lithium-ion and lithium-iron-phosphate plant investments create volatile procurement cycles that ripple through excavator and processing-equipment orders. The Ministry of Trade, Industry, and Energy increased funding for critical minerals exploration from KRW 39 billion to KRW 67.5 billion in 2026. It established a KRW 250 billion strategic stockpile fund, signaling that extraction of tungsten, rare earths, and lithium will anchor equipment demand through the forecast window.
Key Report Takeaways
- By equipment type, excavators led the South Korean mining equipment market, with a 45.21% share in 2025; the same category is projected to expand at a 5.97% CAGR through 2031.
- By mining method, surface operations accounted for 66.43% of the South Korean mining equipment market share in 2025, whereas underground mining is advancing at a 6.46% CAGR to 2031.
- By application, metal mining accounted for 49.85% of the South Korean mining equipment market in 2025, and mineral mining is set to grow at a 6.93% CAGR through 2031.
- By power source, diesel equipment dominated the South Korean mining equipment market, with an 80.13% share in 2025, while battery-electric alternatives are rising at an 8.13% CAGR over 2026-2031.
- By automation level, manual systems held 74.17% of the South Korean mining equipment market share in 2025, yet fully autonomous solutions are poised for a 15.16% CAGR to 2031.
- By geography, the Seoul Capital Area accounted for 45.33% of the South Korean mining equipment market share in 2025, and Yeongnam is forecast to log the fastest 7.11% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
South Korea Mining Equipment Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Electrification Push from Steel and Battery Giants | +1.2% | Seoul Capital Area, Yeongnam | Medium term (2-4 years) |
| Critical-Minerals Exploration Subsidies | +0.9% | National, early gains in Yeongnam and Hoseo | Long term (≥4 years) |
| Tier-4 Final Engine Retrofit Program (2027) | +0.8% | National | Short term (≤2 years) |
| Mine-site 5G Private Networks | +0.7% | Seoul Capital Area, Yeongnam | Medium term (2-4 years) |
| OEM-agnostic “K-SmartMine” Data Platform | +0.5% | National | Medium term (2-4 years) |
| Rare-earth Process-waste Recycling | +0.4% | Seoul Capital Area, Honam | Long term (≥4 years) |
| Source: 麻豆视频 | |||
Electrification Push from Domestic Steel and Battery Giants
In April 2026, POSCO signed a memorandum with Volvo Construction Equipment to co-develop high-strength steel for battery-electric excavator frames. This highlights Korea's steelmakers viewing electrified mining fleets as both customers and testing grounds for advanced alloys. LG Energy Solution is investing USD 5.5 billion in Arizona lithium-iron-phosphate and energy-storage-system plants starting in 2026. SK On secured a USD 13.5 billion government energy-storage procurement contract and is building Korea's largest LFP cell factory. These investments create fluctuating capital-expenditure cycles, impacting the domestic excavator market as battery companies alternate between expansion and cost-cutting. In 2024, Volvo CE's Changwon plant began producing lithium-ion battery packs, enabling local assembly of electric loaders and haulers, reducing import tariffs and lead times for Seoul-area tunnel contractors. The POSCO-SK On lithium-supply agreement for 25,000 tons between 2026 and 2028 links excavator demand to cathode-precursor production schedules, causing equipment orders to rise during battery-material capex surges. This contrasts with stable coal-equipment replacement cycles and introduces volatility, complicating dealer inventory planning.
Government-Backed Critical-Minerals Exploration Subsidies
South Korea is investing significantly to reduce import dependence on critical minerals by offering grants covering up to 30% of the capital expenditure for Tier-4 final compliant drills, autonomous LHDs, and ore-sorting systems.[1]“Critical Minerals Subsidy Framework,” Ministry of Trade, Industry & Energy, mk.co.kr. Seoul's Ministry of Trade, Industry and Energy increased exploration funding to KRW 67.5 billion for 2026 and allocated KRW 250 billion for a strategic stockpile. This reflects the focus on rare-earth and tungsten self-sufficiency through sustained drilling and underground development. Korea reactivated the Korea Resources Corporation's exploration arm in 2024 and set a 20% rare-earth recycling target by 2030, driving demand for drill rigs and crushers. Almonty Industries' Sangdong tungsten mine highlights this shift. Phase 1 achieved 640,000 tons of ore and 2,300 tons of concentrate in 2025. Phase 2 aims for 1.2 million tons of ore and 4,600 tons of concentrate by 2027, requiring additional loaders and haulage systems. The government prioritizes domestic suppliers, with Hyundai Doosan Infracore securing orders for excavators and loaders through won-denominated financing and parts depots in Gangwon Province. While coal mines like Dogye are closing, critical minerals projects offer 45-year mine lives, ensuring long-term equipment replacement opportunities.
Mandatory Retrofit Program for Tier-4-Final Engines
In 2015, Korea adopted the US EPA Tier 4 Final nonroad diesel standards. Operators of excavators and loaders manufactured before this cutoff face a 2027 compliance deadline requiring engine swaps, selective catalytic reduction retrofits, or fleet retirement. HD Hyundai Engine and Doosan Infracore offer Tier 4 Final repower kits, but high retrofit costs, estimated at 30 to 40% of a used excavator's residual value, drive many owners toward new purchases, especially with government low-interest loans for critical minerals projects. The regulation significantly impacts Seoul Capital Area quarries, where aging fleets and limited cash flow accelerate fleet turnover and increase exports of pre-2015 machines to Southeast Asia. Komatsu's early Tier 4 Final production in 2014 provided a compliance advantage, while post-2015 entries by SANY and XCMG with compliant engines reduced incumbents' regulatory edge.
Mine-Site 5G Private-Network Roll-Outs Enabling Autonomy
In 2024, KT Corporation deployed a 5G and LTE private network at Almonty's Sangdong tungsten mine, enabling real-time telemetry for loaders and remote ventilation control from a surface center. In 2025, Hanwha Systems and KT signed an agreement to develop smart-mining solutions for Taebaek limestone quarries, integrating autonomous trucks with 5G-connected crushers to improve throughput. Epiroc's Boomer S2 drill rig at Daesung MDI's Samcheok mine used 5G to synchronize blast-hole patterns with geological data, increasing drilling efficiency by 5-10% and ore production by 10-20%. Korea opened private 5G spectrum in 2021, allowing mine operators to license dedicated slices without sharing bandwidth, accelerating autonomy adoption compared to markets relying on public networks.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Skilled-operator Shortage | -0.8% | National, acute in Seoul Capital Area | Short term (≤2 years) |
| Volatile LG and SK Capex Cycles | -0.6% | Seoul Capital Area, Yeongnam | Medium term (2-4 years) |
| Strict Noise-Emission Limits | -0.4% | Seoul Capital Area, urban peripheries | Long term (≥4 years) |
| Rising Used-Equipment Imports | -0.3% | National, port cities | Short term (≤2 years) |
| Source: 麻豆视频 | |||
Chronic Skilled-Operator Shortage Inflating Labor Costs
An aging workforce and limited mining curricula leave haul-truck utilization rates languishing below 65%, pushing wages up by 18% in 2024 alone [2] “Workforce Trends in Korean Mining,” Korean Society of Mineral & Energy Resources Engineers, ksmer.org. Aging demographics continue to exacerbate workforce challenges, particularly in industries reliant on skilled labor. In 2024, the median age of underground equipment operators surpassed 50, underscoring the growing issue of an aging workforce. This trend poses significant concerns for the sustainability of operations, as older workers approach retirement and fewer younger individuals enter the field. Concurrently, from 2020 to 2025, enrollments in vocational training for heavy machinery plummeted by 30%, as younger generations increasingly gravitate towards white-collar professions. This shift in career preferences further compounds the labor shortage, creating a pressing need for strategies to attract and retain talent in this critical sector.
Volatile LG- and SK-Controlled CAPEX Cycles
In 2026, LG Energy Solution's USD 4.3 billion Tesla lithium-iron-phosphate deal and USD 5.5 billion Arizona plant investment drove excavator demand for lithium-brine and graphite mines. However, a USD 1.2 billion cost-reduction program in Q3 2026 halted discretionary equipment purchases, leaving dealers with excess inventory. SK On's USD 13.5 billion government energy-storage contract caused a procurement spike in 2025-2026, followed by a 2027 pause as capacity additions were absorbed. These cycles shorten equipment payback periods, forcing distressed sales and lowering residual values. The POSCO-SK On lithium-supply agreement for 25,000 tons between 2026 and 2028 partially stabilizes demand but creates a 2027 trough, idling excavators at precursor-feedstock mines. Battery-material capex volatility causes 18-24 month demand swings, straining dealers' working-capital buffers and increasing reliance on used imports from Australia and Japan.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Equipment Type: Excavators Dominate Across Applications
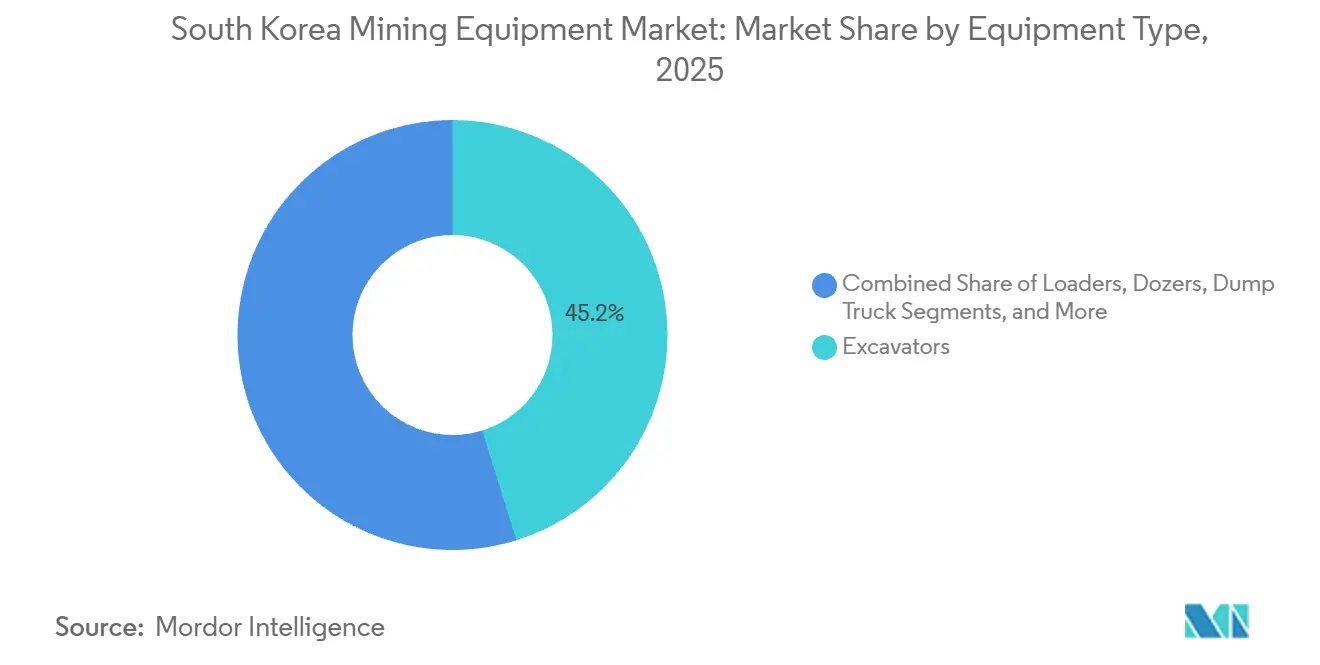
In 2025, excavators accounted for 45.21% of market revenue and are projected to grow at a 5.97% CAGR through 2031, exceeding the overall market's 5.61% CAGR. Growth is driven by underground tungsten and rare-earth projects requiring high-reach, narrow-body models. Almonty Industries' Sangdong mine uses 30-ton and 50-ton excavators for ore and waste handling, with Phase 2's expansion necessitating 8-10 additional units by 2027. Loaders hold the second-largest share, primarily serving limestone quarries in Gangwon and Chungcheong provinces. Volvo CE's Changwon plant supplies battery-electric loaders to Seoul-area contractors for zero-emission compliance in tunnels. Dozers and motor graders serve niche applications like site preparation and haul-road maintenance, but hold less than 15% of the market due to the preference for excavator-truck systems.
Dump trucks and drills/breakers each contribute 8-12% of revenue. Articulated haulers are gaining traction in Sangdong's underground ramps, where rigid-frame trucks are less effective. Crushing, pulverizing, and screening equipment is a high-value segment driven by the shift to limestone and rare-earth tailings processing. Modular jaw crushers and vibrating screens are in demand for their mobility. Metso Outotec and Sandvik lead this segment, while Hyundai Doosan is developing a domestic cone-crusher line to capture aftermarket parts revenue as excavator margins face pressure from used imports. The "Others" category, including roadheaders, continuous miners, and rock-bolting rigs, is growing with underground automation. Sandvik's MT720 roadheader on the Indeokwon-Dongtan tunnel demonstrates low-noise, high-precision excavation, outperforming conventional methods in urban areas.


By Mining Method: Underground Gains on Critical-Minerals Push
In 2025, surface mining contributed 66.43% of Korea's mining revenue, driven by limestone quarries. In 2019, 83,769 kilotons of limestone accounted for 78% of the country's mineral production value. Underground mining, with a 33.57% share, is expected to grow at a 6.46% CAGR through 2031 due to government subsidies for deep tungsten and rare-earth deposits. Almonty's Sangdong mine highlights this shift, with Phase 1 extracting 640,000 tons annually using long-hole stoping. Phase 2 aims for 1.2 million tons with sub-level caving and autonomous loaders. The Ministry of Trade, Industry, and Energy allocated KRW 67.5 billion for underground exploration, while Korea Resources Corporation resumed geological surveys in 2024 to map tungsten veins.
Surface operations dominate limestone extraction for cement and steel flux. However, the closure of Dogye Coal Mine in July 2025 ended 1.2 million tons of annual surface coal demand. The last private coal mine will close in 2028, redirecting investments to rare-earth and lithium-brine projects, favoring underground methods. At Daesung MDI's Samcheok mine, Epiroc's Boomer S2 drill rig increased ore production by 10-20% through real-time blast-hole optimization. KT Corporation's 5G network at Sangdong enables remote loader operation, reducing operator risks and increasing equipment utilization from 65% to 80%, justifying the higher cost of autonomous machines.
By Application: Metal Mining Leads, Mineral Processing Accelerates
In 2025, metal mining contributed 49.85% of revenues, supported by operations like Sangdong tungsten and copper-zinc in Gangwon Province. Mineral mining, including rare-earth processing, feldspar, and silica, is projected to grow at 6.93% through 2031. This growth aligns with Seoul's 20% rare-earth recycling target for 2030, enhancing secondary-processing capacities. In 2024-2025, companies such as POSCO HY Clean Metal, LG Energy Solution, and SK Innovation began rare-earth recovery pilots using hydrogen decrepitation furnaces and magnetic separators. These require modular crushing plants near battery gigafactories in the Seoul Capital Area and the Hoseo regions. Following Dogye's closure, coal mining's share fell below 5%. With the last private colliery closing in 2028, demand for excavators and haul trucks will shift to metal and mineral applications.
Limestone, under mineral mining, was Korea's top commodity by tonnage at 83,769 kilotons in 2019, but its low unit value of USD 8-12 per ton limits equipment investments. Tungsten concentrate, valued at USD 250-300 per metric ton unit, contrasts sharply. A lithium supply agreement between POSCO and SK On for 25,000 tons from 2026 to 2028 ties metal-mining equipment demand to battery-material procurement cycles. Rare-earth tailings processing will require specialized crushing circuits to protect neodymium and dysprosium from oxidation. In 2025, Metso Outotec tested a closed-loop jaw-crusher system for lithium-ion black mass, but Korean operators prefer Hyundai Doosan for its after-sales proximity. This preference creates opportunities for domestic firms to develop turnkey recycling modules. The Ministry of Trade, Industry and Energy allocated KRW 250 billion from its critical-minerals fund to strengthen secondary-processing infrastructure. The 6.93% CAGR for mineral mining reflects growth in both primary extraction and recycling demand.
By Power Source: Diesel Dominates, Battery-Electric Gains Traction
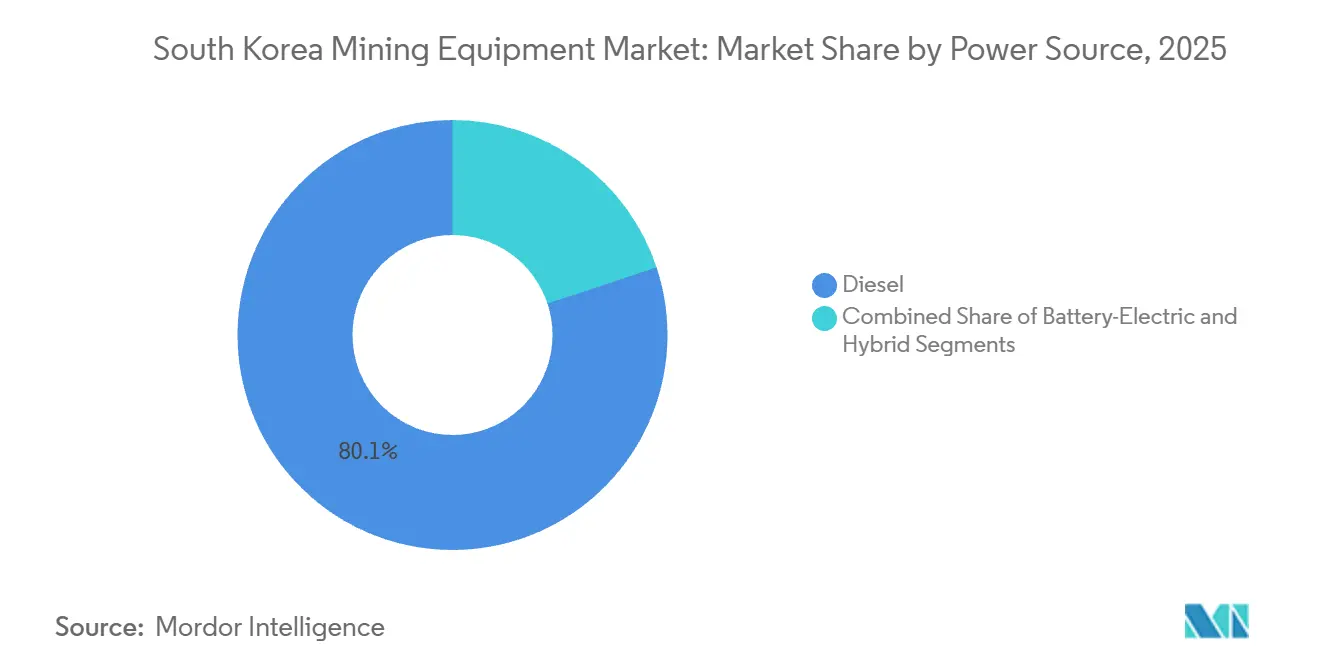
Diesel power sources accounted for 80.13% of 2025 revenue due to the existing base and energy density needed for 12-hour shifts. Battery-electric units are projected to grow at a CAGR of 8.13% through 2031, supported by Volvo CE's lithium-ion production and stricter zero-emission mandates in Seoul. Hybrid power sources, combining diesel generators with battery buffers, are expected to capture 5-8% market share, appealing to operators seeking reduced fuel consumption. Komatsu's WX04B and Epiroc's Scooptram ST14 SG began trials in Korea in 2025, with adoption dependent on charging infrastructure like Sangdong's fast-charging stations enabling 18-hour utilization.
Korea's adoption of US EPA Tier 4 Final standards in 2015 and the 2027 retrofit deadline will push operators of pre-2015 excavators to choose between costly engine replacements or battery-electric models. The 8.13% CAGR for battery-electric units reflects cautious adoption as operators await proof of cost parity. Lithium-ion battery degradation and high replacement costs challenge the business case if annual utilization is below 2,000 hours.
By Automation Level: Manual Fleets Persist, Fully Autonomous Surges
Manual equipment accounted for 74.17% of the installed base in 2025, reflecting high costs of autonomous retrofits ranging from USD 200,000 to 300,000 per excavator and limited availability of 5G-enabled mine sites outside Gangwon Province. Semi-autonomous systems held a 15-20% market share, appealing to operators seeking productivity improvements without full infrastructure upgrades. Fully autonomous equipment, contributing 5-8% of 2025 revenue, is projected to grow at 15.16% through 2031, supported by 5G private-network deployments and retrofit kits from major manufacturers. Epiroc's Boomer S2 at Daesung MDI's Samcheok mine demonstrated autonomy's benefits beyond labor cost savings by achieving efficiency and production gains.
In 2021, Korea opened private 5G spectrum, enabling mine operators to license dedicated bandwidth without competing with consumer traffic. This regulatory advantage has accelerated autonomy adoption compared to markets reliant on public networks. At Almonty's Sangdong mine, KT's 5G/LTE network enables remote control of underground loaders, reducing operator headcount and increasing equipment utilization. The shortage of skilled operators and rising wages have made the 3-4 year payback period for autonomous systems more attractive. However, the 74.17% share of manual equipment highlights the challenges of retrofitting legacy fleets, limiting adoption to greenfield sites and large operators, while smaller quarries continue to rely on manual equipment.
Geography Analysis
The Seoul Capital Area accounted for 45.33% of 2025 revenue, driven by metro extension projects and Hyundai Doosan Infracore's Incheon headquarters, which reduced parts lead times and enabled 24-hour service response. Sandvik's MT720 roadheader, used on the Indeokwon-Dongtan railway tunnel, demonstrated low-noise, precision excavation, operating at 68 dB(A) and outperforming conventional methods in urban granite excavation. Growth is expected to moderate to 4.8-5.2% through 2031 due to noise-emission constraints under the Noise and Vibration Control Act, which are driving quarry relocations and higher capital costs for compliant equipment.
Yeongnam is projected to achieve the fastest regional CAGR at 7.11% through 2031, supported by government subsidies for critical minerals projects. Almonty Industries' Sangdong mine expansion will double ore throughput by 2027, requiring additional autonomous equipment integrated with KT's 5G network. The Ministry of Trade, Industry, and Energy has increased exploration funding and established a strategic stockpile, reinforcing long-term demand for mining equipment in the region.
Honam and Hoseo regions contribute smaller shares, primarily from limestone quarries serving cement plants, with growth limited to 3.5-4.5% due to fragmented ownership and restricted capital for low-noise retrofits. The "Others" category, including Jeju Island and rural Gangwon, accounts for less than 5% of revenue, driven by small-scale aggregate and ornamental-stone extraction favoring used equipment.
Competitive Landscape
The South Korea mining equipment market is moderately concentrated, with Caterpillar, Komatsu, and Hitachi Construction Machinery maintaining strong dealer networks and 24-hour service support. Hyundai Doosan Infracore, formed in January 2026 through the merger of HD Hyundai Construction Machinery and HD Hyundai Infracore, leverages local-content preferences and won-denominated financing to secure orders from key clients like POSCO and SK Ecoplant. Chinese manufacturers SANY and XCMG offer lower prices but face challenges due to concerns over parts availability and resale value, limiting their market share to 8-10%. Rising imports of used excavators from Japan and Australia, valued at USD 1.73 billion in 2025, have pressured margins for mid-tier models, prompting OEMs to offer telematics bundles, extended warranties, and financing subsidies, which impact profitability despite stable unit volumes.
Opportunities exist in battery-electric crushing plants for rare-earth tailings, driven by zero-emission mandates at urban-fringe sites, and in semi-autonomous drill rigs for narrow-vein tungsten deposits, segments underserved by global OEMs. Volvo CE's collaboration with POSCO to develop high-strength steel for battery-electric excavator frames reflects a strategic alignment between Korean steelmakers and electrified mining fleets, expected to boost domestic production and reduce import lead times. Epiroc's Boomer S2 autonomous drill rig at Daesung MDI's Samcheok mine has shown 10-20% ore-production gains, highlighting autonomy's potential beyond labor savings, while Sandvik's refurbished MT720 roadheader deployed on the Indeokwon-Dongtan tunnel demonstrates cost-effective, high-performance solutions.
Korean engineering firms are emerging as disruptors by developing turnkey rare-earth recycling modules, such as compact crushing plants near battery gigafactories, a niche overlooked by global OEMs. The Ministry of Trade, Industry and Energy's KRW 250 billion critical-minerals fund supports secondary-processing infrastructure, creating opportunities for domestic suppliers offering won-denominated financing and rapid parts delivery. These developments, combined with policy support and strategic collaborations, are shaping the competitive landscape of the South Korea mining equipment market.
South Korea Mining Equipment Industry Leaders
Caterpillar Inc.
Komatsu Ltd.
Hyundai Doosan Infracore
Hitachi Construction Machinery
Volvo Construction Equipment
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- June 2025: Sweden-based OEM Volvo Construction Equipment announced an investment of approximately USD 260 million to expand crawler excavator production across global regions, including South Korea. The initiative focuses on localizing manufacturing capacity to reduce dependence on long-distance exports and strengthen regional supply chains.
- May 2025: HD Hyundai Construction Equipment inaugurated a smart factory in Ulsan with an investment of approximately EUR 131 million (KRW 200 billion) to modernize its production capabilities. The facility integrates AI-based inspection, robotics, and real-time production tracking systems to enhance manufacturing efficiency.


South Korea Mining Equipment Market Report Scope
| Excavators |
| Loaders |
| Dozers |
| Motor Graders |
| Dump Trucks |
| Drills and Breakers |
| Crushing, Pulverizing and Screening |
| Others |
| Underground Mining |
| Surface Mining |
| Metal Mining |
| Mineral Mining |
| Coal Mining |
| Diesel |
| Battery-Electric |
| Hybrid |
| Manual Equipment |
| Semi-Autonomous |
| Fully-Autonomous |
| Seoul Capital Area |
| Yeongnam (South-East) |
| Honam (South-West) |
| Hoseo (Central) |
| Others |
| By Equipment Type | Excavators |
| Loaders | |
| Dozers | |
| Motor Graders | |
| Dump Trucks | |
| Drills and Breakers | |
| Crushing, Pulverizing and Screening | |
| Others | |
| By Mining Method | Underground Mining |
| Surface Mining | |
| By Application | Metal Mining |
| Mineral Mining | |
| Coal Mining | |
| By Power Source | Diesel |
| Battery-Electric | |
| Hybrid | |
| By Automation Level | Manual Equipment |
| Semi-Autonomous | |
| Fully-Autonomous | |
| By Geography | Seoul Capital Area |
| Yeongnam (South-East) | |
| Honam (South-West) | |
| Hoseo (Central) | |
| Others |


Key Questions Answered in the Report
How large is the South Korea mining equipment market in 2025?
The market is valued at USD 1.69 billion in 2025 and is forecast to reach USD 2.34 billion by 2031.
Which equipment category generates the most revenue?
Excavators lead with a 45.21% share in 2025 and continue to expand fastest at a 5.97% CAGR.
What region shows the highest growth momentum?
Yeongnam in South-East Korea is projected to grow at a 7.11% CAGR through 2031 due to steel and battery material investments.
How fast are battery-electric machines growing?
Battery-electric mining equipment is expected to grow at an 8.13% CAGR as operators pivot away from diesel.
Page last updated on:



