
United States Data Center Server Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 31.29 Billion |
| Market Size (2026) | USD 33.92 Billion |
| Market Size (2031) | USD 50.83 Billion |
| Growth Rate (2026 - 2031) | 8.42 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. | |
United States Data Center Server Market Analysis by 麻豆视频
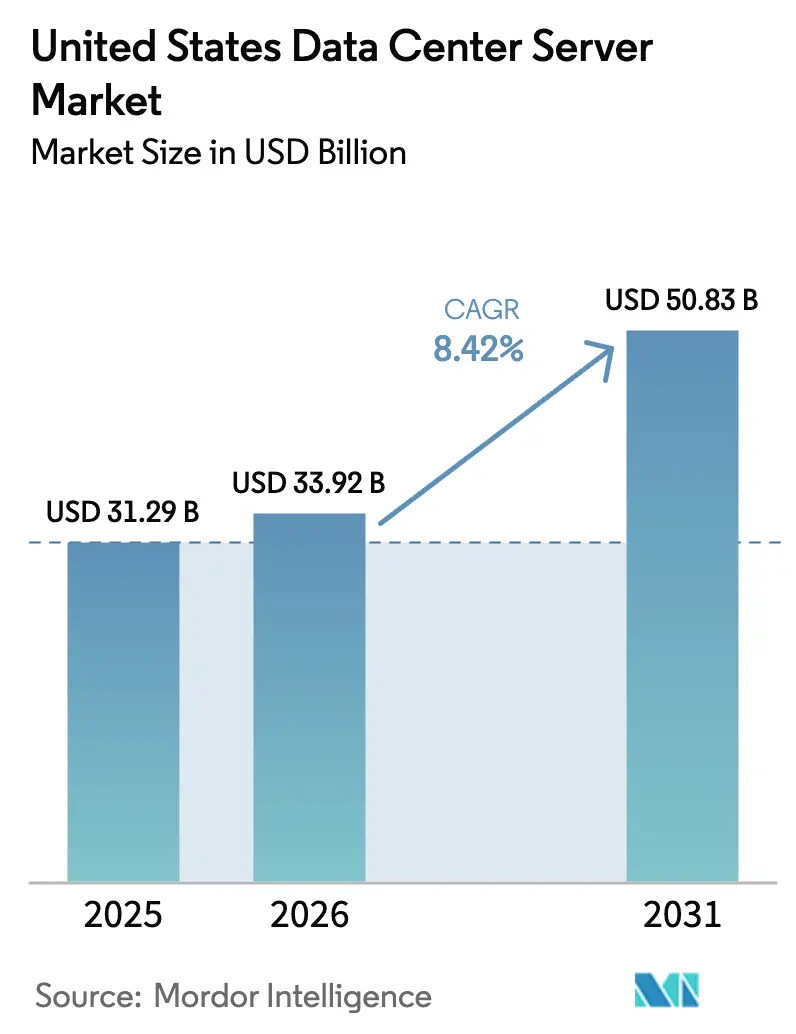
The United States data center server market size in 2026 is estimated at USD 33.92 billion, growing from 2025 value of USD 31.29 billion with 2031 projections showing USD 50.83 billion, growing at 8.42% CAGR over 2026-2031. Server demand is benefiting from a synchronized hyperscaler capital-expenditure cycle, the rapid spread of enterprise AI workloads, and new federal incentives for on-shore semiconductor manufacturing. Hyperscalers alone disclosed USD 676 billion of fresh data-center investment intentions in January 2025, with AWS and Microsoft earmarking USD 100 billion and USD 80 billion, respectively, for United States build-outs. AI workload growth is redefining server refresh rates, cutting lifecycles from six to five years as firms pursue higher density and liquid-cool-ready racks. IBM's annual Cost of a Data Breach Report revealed that in 2024, the global average cost of a data breach hit USD 4.88 million. This surge comes as breaches become increasingly disruptive, further straining cyber teams. Notably, breach costs increased by 10% from the previous year, marking the steepest rise since the onset of the pandemic. Alarmingly, 70% of organizations that faced breaches acknowledged experiencing significant or very significant disruptions.
Key Report Takeaways
- By tier, Tier 3 facilities led the United States data center server market share with 65.70% in 2025, while Tier 4 is forecasted to grow at a 12.79% CAGR through 2031.
- By form factor, half-height blades held 48.54% share of the United States data center server market size in 2025; quarter-height micro-blades are advancing at 13.87% CAGR.
- By application, virtualization and private cloud retained a 37.92% share of the United States data center server market, and AI/ML workloads are expanding at a 15.81% CAGR.
- By data center type, colocation captured 64.20% of the United States data center server market share in 2025, while hyperscaler deployments showed the fastest growth at 14.74% CAGR.
- By end-use industry, IT and telecom accounted for 25.93% of the United States data center server market revenue in 2025, as government and defense workloads are expected to accelerate at a 12.79% CAGR.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
United States Data Center Server Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid hyperscaler CAPEX cycle renewal | +2.3% | Global, concentrated in Virginia, Oregon, Texas | Medium term (2-4 years) |
| Enterprise AI/ML workload proliferation | +2.8% | National, with early gains in California, New York, Washington | Short term (≤ 2 years) |
| Edge-cloud convergence boosting micro-server demand | +1.4% | Asia Pacific core, spill-over to tier-2 US cities | Medium term (2-4 years) |
| Government incentives for domestic semiconductor/Server manufacturing | +1.2% | National, focused on Arizona, Ohio, Texas | Long term (≥ 4 years) |
| U.S. power-availability contracts favor liquid-cool-ready racks | +0.7% | Regional, concentrated in Pacific Northwest, Texas | Medium term (2-4 years) |
| Tier-2 city tax abatements attracting second-wave data-center builds | +0.6% | National, with early gains in Phoenix, Columbus, Austin | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Rapid hyperscaler CAPEX cycle renewal
Amazon, Microsoft, Google, and Meta collectively plan to spend more than USD 320 billion on data centers in 2025, extending server replacement cycles to five years as firms pursue AI compute density. Amazon’s USD 100 billion allocation alone is estimated to add a USD 700 million operating-income drag due to accelerated depreciation, yet it shortens payback periods for advanced liquid-cooled racks. Federal agencies are mirroring the trend; sixteen Department of Energy sites have been fast-tracked for server-dense builds, with online availability expected by 2027, reinforcing demand peaks in Virginia and Oregon.[1]U.S. Department of Energy, “DOE Identifies 16 Sites for AI Data Centers,” Energy.gov, energy.gov
Enterprise AI/ML workload proliferation
Financial institutions cite an 84% concern among executives over catastrophic data loss if AI infrastructure falls short. Accuracy levels of only 21% in banking models spur investment in servers optimized for vector processing and larger memory footprints. Healthcare systems leverage AI for diagnostics and documentation, driving rack densities up to 50 kW. Manufacturing groups are adopting Industry 4.0 applications on edge nodes, combining 5G and micro-data center form factors. Lenovo’s ThinkSystem V4 platform achieves 2.5× rack density and 2.4× performance-per-watt gains, underscoring its efficiency goals.
Edge-cloud convergence boosting micro-server demand
Latency-sensitive services, ranging from interactive gaming to smart-factory analytics, are relocating compute resources near end users through transportable 20-foot micro facilities. Early rollouts in Austin, Tampa, and Raleigh show hyperscalers leasing edge racks to improve content delivery. Dallas has become a Local Zone hub as Verizon deploys 5G Edge on AWS Wavelength. Compact quarter-height blades, liquid cooling, and modular enclosures together define preferred architectures for these distributed sites.
Government incentives for domestic semiconductor manufacturing
CHIPS-Act grants of USD 6.6 billion to TSMC, plus associated state-level tax credits, underpin USD 65 billion of foundry builds in Phoenix. Target output includes advanced AI accelerator dies and server CPUs. Intel collaborates with AWS on custom silicon while Micron lines up HBM production aligned to domestic fabs. Policymakers aim to have 20% of leading-edge nodes onshore by 2030, reducing reliance on Asian supply chains and stabilizing server bill-of-material costs.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising frequency and cost of cyber-intrusions | -1.8% | Global | Short term (≤ 2 years) |
| Supply-chain volatility for key silicon (HBM, GPUs) | -2.1% | Global, with acute impact on US hyperscalers | Short term (≤ 2 years) |
| Grid-interconnection delays exceeding 24 months in PJM and MISO | -1.3% | PJM and MISO regions (Mid-Atlantic, Midwest) | Medium term (2-4 years) |
| New EPA ENERGY STAR v4 idle-power caps constraining legacy refresh | -0.4% | National | Long term (≥ 4 years) |
| Source: 麻豆视频 | |||
Rising frequency and cost of cyber-intrusions
Average breach costs of USD 5.56 million in 2024, combined with downtime expenses exceeding USD 100,000 per event, elevate the total cost of ownership. Forty-two percent of banks have migrated AI workloads away from public clouds due to security concerns, prompting on-premises build-outs that lengthen procurement cycles and increase CapEx. Ransomware events, such as CloudNordic’s total customer data loss, illustrate worst-case scenarios compelling wider adoption of zero-trust architectures and biometric access controls.
Supply-chain volatility for key silicon (HBM, GPUs)
Extended twelve-month lead times for HBM stacks and a TSMC CoWoS packaging bottleneck hinder AI server shipments. SK Hynix export volumes fell 30% sequentially in January 2025, and proposed tariffs threaten to lift component costs by up to 30%. NVIDIA still holds 98% of data-center GPU shipments, making the ecosystem highly sensitive to its production cadence.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Data-Center Tier: Fault-tolerant builds accelerate Tier 4 adoption
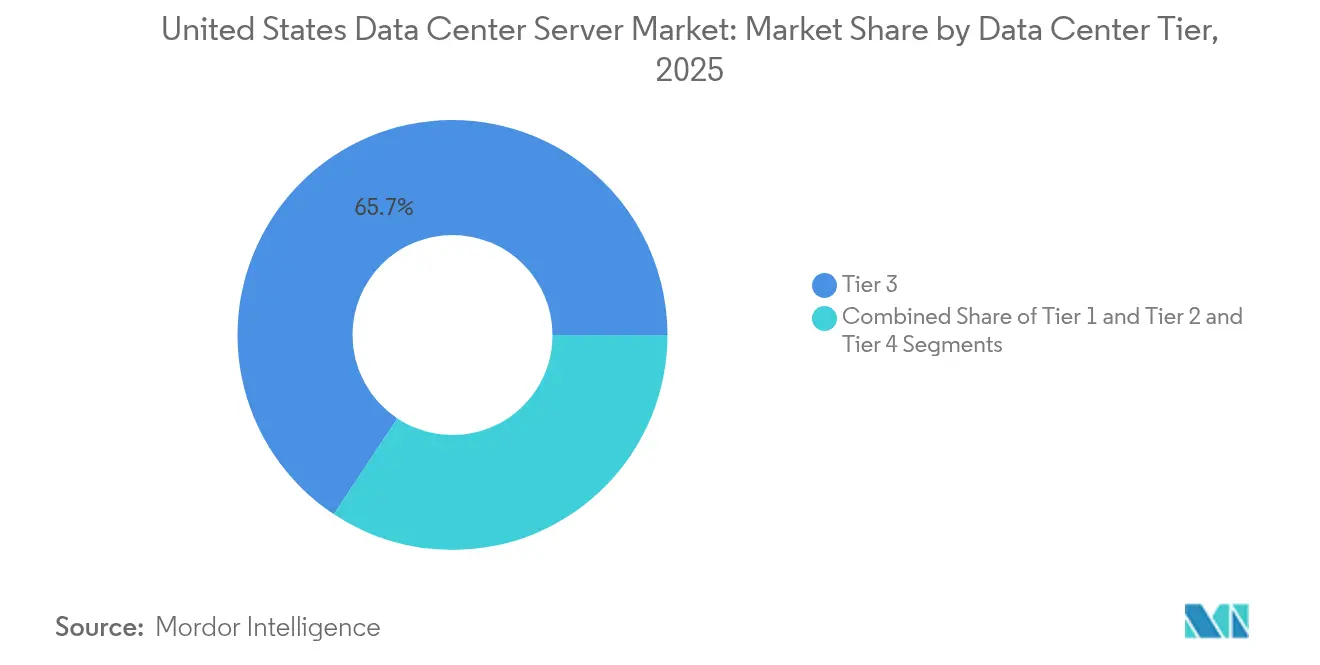
Tier 3 installations delivered 65.70% of revenue in 2025, anchoring the United States data center server market. Tier 4, though smaller, is projected to rise at 12.79% CAGR as hyperscalers assign AI training clusters to fully fault-tolerant halls where a single outage can cost over USD 100,000. The United States data center server market size contribution from Tier 4 is projected to grow steeply between 2026 and 2031. Federal programs that earmark sixteen sites for AI-ready builds favor Tier 4 specifications, given 50 kW-per-rack power densities anticipated by 2027.
Tier 1 and Tier 2 designs remain relevant for distributed edge nodes prioritizing cost efficiency over maximum redundancy. Financial-services migration toward Tier 4 also stems from stricter compliance and rising breach penalties. Altogether, the resilience imperative cements Tier 4 as the fastest-moving slice, reshaping colocation upgrade roadmaps and guiding liquid-cooling retrofits.


By Form Factor: Micro-blade innovation squeezes half-height share
Half-height blades retained 48.54% market share in 2025 on the strength of virtualization workloads. Yet quarter-height micro-blades are climbing at 13.87% CAGR as operators compress racks into 20-foot edge modules. The United States data center server market size for micro-blade deployments is thus on an upward trajectory through 2031. EdgeMicro’s city-center installs and manufacturing-sector Industry 4.0 pilots highlight the swing toward compact, energy-efficient hardware.
Full-height blades continue serving HPC clusters, but power-per-rack limits increasingly favor micro-blades paired with direct-to-chip liquid cooling. Hyperscalers are selectively adopting micro-blade platforms for AI inference nodes, balancing density against memory bandwidth needs.
By Application/Workload: AI/ML surges beyond legacy virtualization
Virtualization and private cloud maintained 37.92% share in 2025, anchoring the United States data center server market. AI/ML workloads, however, are forecast to expand 15.81% CAGR, pulling compute toward GPU-heavy nodes and high-bandwidth memory stacks. This shift underpins Dell’s USD 12.1 billion AI server backlog and amplifies demand for rack-scale liquid cooling.
High-performance computing persists for scientific projects, whereas storage-centric topologies absorb the data deluge from AI training. Healthcare’s adoption of inference engines for imaging and patient engagement drives specialized server procurement, and manufacturing brings low-latency edge AI to plant floors.
By Data-Center Type: Hyperscaler build-outs challenge colocation primacy
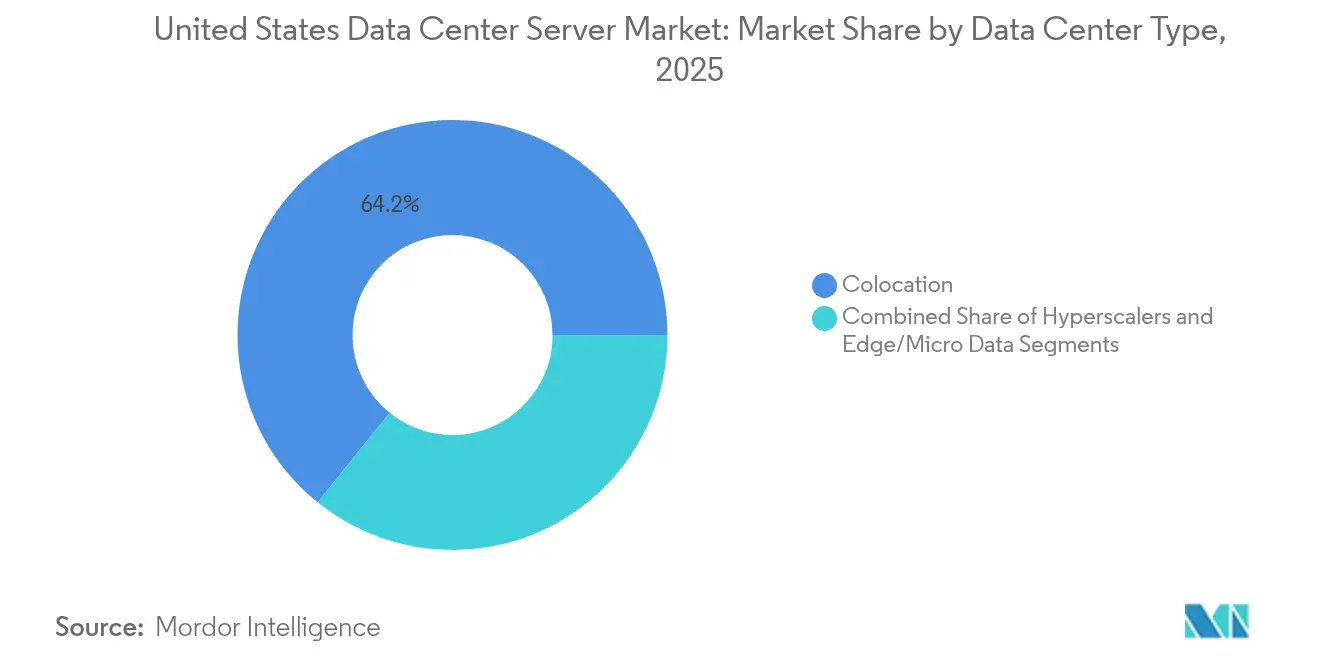
Colocation providers commanded 64.20% revenue in 2025, yet hyperscaler self-builds are running at 14.74% CAGR as integrated power, network, and cooling designs promise lower unit costs for AI. The United States data center server market share advantage enjoyed by colocation players is therefore narrowing over the forecast horizon. Meta, Google, and Amazon together target more than USD 240 billion in near-term investment, embedding liquid-cooled racks and direct-chip cold plates.
Colocation firms respond with AI-ready pods and renewable-energy PPAs. Flexential reports that 51% of enterprises still place edge workloads in colocation sites, signaling continued relevance for hybrid deployments even as hyperscalers stretch campus footprints.
By End-Use Industry: Government emergence narrows IT/telecom lead
IT and telecom sectors remained the largest buyer group at 25.93% in 2025, but government and defense workloads are growing 12.79% CAGR as federal AI initiatives roll out. The United States data center server industry is therefore seeing procurement diversification that balances commercial and public-sector demand. Department-of-Energy construction plans and AI export-control frameworks guide secure, high-density server specifications.
Financial-services firms report heightened risk concerns, pushing some AI compute onto private racks with enhanced encryption. Healthcare and manufacturing extend edge-server adoption for compliance and predictive-maintenance gains, respectively, broadening the customer mix.
Geography Analysis
Virginia, Oregon, and Texas together form the primary geographic core of the United States data center server market, thanks to competitive power prices, established fiber routes, and hyperscaler zoning incentives. Virginia’s proximity to federal agencies feeds low-latency workloads, whereas Oregon leverages hydroelectric resources and cool ambient temperatures to cut PUE scores. Texas draws development through deregulated energy markets and abundant land, anchoring mega-campus projects from AWS and Microsoft.
Secondary hubs are scaling quickly. Phoenix offers a dry climate and favorable property-tax abatements, while Columbus benefits from centrality to national backbones. Austin marries an expanding tech workforce with airport proximity for supply-chain efficiency. EdgeMicro’s Austin, Tampa, and Raleigh deployments confirm rising investment in tier-2 metros.
Interconnection delays in PJM and MISO pose regional headwinds, with queue times topping 24 months and capacity-auction costs hitting USD 14.7 billion. The NERC 2024 assessment projects 15% summer and 18% winter peak-load increases over the decade, underscoring grid modernization needs. California’s server energy-efficiency mandates add compliance layers but also steer buyers toward lower-idle-power nodes, aiding national sustainability targets.
Regulatory Landscape
United States data center server deployments are increasingly shaped by federal actions linking AI infrastructure to national security and grid reliability, along with faster-growing state oversight. In July 2025, the White House issued an action aimed at accelerating federal permitting for data center infrastructure. In 2026, the regulatory discussion broadened to large-load interconnection and cost-allocation as grid queues in regions such as PJM and MISO extend beyond 24 months. At the federal level, the Federal Energy Regulatory Commission (FERC) has been active on large-load interconnection topics, including frameworks affecting co-located load and generation, which can influence site selection, power contracting, and time-to-service for high-density AI halls.
Energy and sustainability guidance also feeds into server specifications, particularly around idle power and efficiency metrics, while security oversight for large server farms has gained attention. The US Department of Energy (DOE), through its Federal Energy Management Program (FEMP), continues to publish and refresh best-practice guidance for federal data centers, including design recommendations and performance metrics such as PUE and WUE. Alongside these federal signals, early-2026 tracking highlights hundreds of data center-related state bills across dozens of states, shifting from incentives toward requirements covering siting, utility coordination, reporting, and community impacts. That broadening adds compliance complexity for colocation operators and hyperscalers procuring new server capacity.
Value Chain Analysis
The United States data center server value chain starts with silicon and other high-value components (CPUs, GPUs, HBM, NICs), then moves through board-level integration, system OEM manufacturing, rack integration, and finally deployment into hyperscaler and colocation facilities. Upstream constraints around advanced packaging and memory availability can cascade into system lead times, while downstream readiness depends on power availability (transformers, switchgear, UPS), thermal infrastructure, and commissioned electrical capacity. As AI racks shift toward higher densities and liquid-cooling-ready configurations, the value chain extends beyond server chassis into cold plates, manifolds, heat exchangers, and facility water and heat-rejection systems.
In the midstream and downstream layers, federal programs and technical bodies are pushing practical adoption of efficiency and cooling innovations. DOE efforts such as the Data Center Cooling Collaborative aim to shorten time-to-market for advanced cooling approaches, while federal guidance from FEMP and partners such as NREL supports standard performance measurement using metrics including PUE, ERE, WUE, and CUE. These measurements feed into server selection criteria, including idle power behavior, power capping, and platform-level energy telemetry. Water and reuse constraints further shape site and design decisions, with programs such as the National Alliance for Water Innovation (NAWI) supporting water-reuse solutions aligned with higher-density server deployments.
Competitive Landscape
Competition in the United States data center server market is intensifying amid AI-driven demand spikes. Dell Technologies leads shipment revenue, posting USD 6.3 billion in Q1 FY26, and a record USD 12.1 billion AI backlog. Hewlett Packard Enterprise follows with 12.8% server-segment growth in 2024, leveraging its GreenLake platform for hybrid cloud uptake. AMD’s USD 3.9 billion Q4 2024 data-center revenue moved its CPU share past Intel to 27.2% in early 2025, signaling a reshuffled x86 hierarchy.[3]Tom’s Hardware staff, “AMD Overtakes Intel in Data-Center CPU Revenue,” Tomshardware, tomshardware.com
Partnerships are redrawing the field. AMD and Intel formed an advisory consortium to optimize x86 platform compatibility, while Qualcomm re-entered the server CPU arena via a tie-up with NVIDIA. NVIDIA’s Blackwell ecosystem aligns with ASRock Rack and GIGABYTE to seed AI-factory-grade systems. Super Micro Computer advances rack-scale liquid-cooled offerings, and Chemours partners with DataVolt on fluorinated dielectric fluids to manage 50 kW-per-rack heat loads.
Hyperscalers influence supplier roadmaps by locking multi-year deals for AI accelerator volumes, intensifying competition around delivery lead-times and energy-efficiency metrics. Component makers that secure domestic CHIPS-Act funding gain preferred-supplier status, while the broader vendor pool accelerates liquid-cool-ready designs to preserve relevance in high-density aisles.
United States Data Center Server Industry Leaders
Dell Technologies Inc.
Hewlett Packard Enterprise Company
Lenovo Group Limited
International Business Machines Corporation
Cisco Systems, Inc.
- *Disclaimer: Major Players sorted in no particular order


Market Opportunities and Future Outlook
A major whitespace area is emerging around "power-aware" server platforms and integrated rack-scale systems built to operate within tighter interconnection, permitting, and utility-coordination regimes while still meeting AI performance needs. Federal actions in 2025 elevated AI data centers at DOE facilities within a defense-oriented framing, and the July 2025 presidential action on accelerating federal permitting for data center infrastructure reinforces the value of standardized designs that can move through approvals faster and deploy predictably across sites. For server vendors and integrators, this creates room for configurable, liquid-cool-ready platforms, embedded energy telemetry, and validated reference architectures tied to utility requirements and facility metrics such as PUE and WUE, rather than one-off bespoke builds.
Grid flexibility and on-site energy strategies also expand the addressable need for servers that can operate under power constraints and support load management. DOE initiatives highlighted in 2026, including REFLEX focused on large-user grid flexibility, point to continued program support for demand-side approaches in constrained regions. At the same time, the DOE and FEMP best-practice ecosystem encourages operators to adopt measurable efficiency improvements, supporting procurement preference for newer server generations with better performance-per-watt and lower idle power behavior. As state-level oversight expands and FERC continues engaging on large-load interconnection and co-location frameworks, buyers increasingly weigh supply-chain transparency, security controls, and standardized deployment playbooks when purchasing server, rack, and thermal configurations for scale.
Recent Industry Developments
- June 2026: Dell Technologies announced the PowerEdge XE8812 server, featuring NVIDIA Vera Rubin NVL4 architecture for high-performance AI and HPC workloads. The debut expands high-density AI and HPC server capabilities in Dell's lineup, reinforcing leadership in AI-optimized rack infrastructure. The move heightens competition in AI-ready data-center procurement as customers pursue densification and advanced acceleration.
- June 2026: Dell Technologies expanded the Dell AI Factory with NVIDIA by incorporating PowerEdge R9822 and M9822 servers utilizing NVIDIA Vera CPUs to support agentic AI at scale. The expansion accelerates Dell's capacity to deliver large-scale AI systems and sets market expectations for scalable AI deployments in data centers. It influences supplier and customer decision dynamics in AI data-center builds.
- May 2026: Dell Technologies introduced the 18th generation of PowerEdge servers with air- and liquid-cooling designs, alongside the Dell PowerStore Elite storage system. The new generation targets AI-ready workloads and improves cooling efficiency and density. The update broadens Dell's product cadence to capture AI-driven refresh cycles.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers servers deployed inside US data centers, measured as revenues from server systems shipped for use in enterprise, colocation, and hyperscale facilities, including general purpose and accelerator-ready configurations.
Scope exclusions: We exclude servers primarily sold for non-data-center environments (such as typical office or home use) and related non-server infrastructure like power, cooling, and building fit-outs.
Segmentation Overview
- By Data-Center Tier
- Tier 1 and 2
- Tier 3
- Tier 4
- By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
- By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
- By Data Center Type
- Hyperscalers/Cloud Service Provider
- Colocation Facilities
- Enterprise and Edge
- By End-use Industry
- BFSI
- IT and Telecom
- Healthcare and Life-Sciences
- Manufacturing and Industry 4.0
- Energy and Utilities
- Government and Defence
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to set the market context and anchor the model to widely tracked US data center and compute indicators. We typically reference public sources such as US Census Bureau trade statistics, the US International Trade Commission data tools, the Bureau of Labor Statistics producer price indexes, ENERGY STAR program resources, and US government procurement portals for tender language and spend signals.
We also review annual reports, earnings transcripts, investor decks, and reputable technology press to map refresh cycles and demand drivers, then cross-check against paid subscriptions for company financials and news. For additional triangulation, we use patent databases and shipment-level import/export records when trade flows are a meaningful signal. The desk sources listed here are illustrative only, since we also use other public and paid references for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focuses on validating what desk indicators cannot fully explain, especially the split between hyperscale, colocation, and enterprise demand, and how server configurations are changing with AI and higher rack density. We speak with both supply side and demand side participants, including server OEM and channel roles, data center operators, and large end users across key US hubs. After interviews, we re-check assumptions such as unit mix, typical pricing, and replacement timing before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 35% | CXOs: 12% |
| Mid tier: 48% | Functional/Unit leaders: 30% |
| Smaller Players: 17% | Managers: 58% |
Market-Sizing & Forecasting
Sizing starts with a top-down build that reconstructs the US demand pool using data center capacity expansion and refresh behavior, which are then translated into server unit needs and value through configuration and pricing logic. To keep the totals realistic, selective bottom-up checks are applied, such as sampled ASP multiplied by estimated shipment volumes, channel checks on lead times, and supplier revenue reasonableness checks for the US portion of sales.
Inputs are chosen for observable linkages to server spend, including data center capacity additions by facility type, server refresh cycles by workload intensity, AI server mix and accelerator-ready penetration, average selling price changes by CPU generation and memory content, and constraints like power availability that can delay deployments. For forecasting, we use scenario analysis supported by simple time-series smoothing on core indicators, and then adjust assumptions based on what operators and procurement roles expect for ordering cadence and configuration shifts. Where bottom-up signals are incomplete, we handle gaps with conservative ranges and tighten them during follow-up calls and cross-checks against adjacent indicators like construction starts and import trends.
Data Validation & Update Cycle
Model outputs are checked against independent signals, and we review results for unusual jumps that do not match known procurement or pricing cycle behavior. If a variance is identified, we trace it back to a specific input, then run a second pass that tests sensitivity to mix, pricing, and refresh assumptions.
Before sign-off, numbers go through multi-step analyst reviews, and experts are re-contacted when a key assumption shifts or a large discrepancy persists. Reports are refreshed annually, with interim updates when material events occur, and a final pre-delivery review is completed so clients receive the most current view available.
麻豆视频's United States Data Center Server Market Size Compared Against Other Published Estimates
Published market sizes for US data center servers often differ because each publisher chooses its own product scope, base year, and pricing build, and then applies different assumptions for AI-driven configuration upgrades. The spread is also affected by how colocation and hyperscale purchases are treated, plus how quickly the model is refreshed when component pricing or lead times shift.
Some external estimates fold adjacent infrastructure or broader data center hardware into the total, which can lift the number even when server unit demand is unchanged. In contrast, 麻豆视频 counts only server systems deployed in US data centers and keeps switches, storage arrays, and facility equipment outside the total, and that scope choice is validated through operator-led refresh and ASP checks.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 麻豆视频 | USD 31.29 B (2025) | |
| Trade Journal A | USD 19.42 B (2024) | Uses an older base year and tends to rely on a narrower shipment lens, which can undercount AI-optimized configurations and the price uplift tied to higher memory and accelerator-ready builds. |
| Global Consultancy B | USD 39.80 B (2026) | Often reports a broader hardware spend view for data centers in the US, which can mix server totals with adjacent compute hardware assumptions and apply a more aggressive ASP progression into the forecast year. |
Taken together, the comparison shows that scope choices and pricing logic explain most of the distance between estimates, more than simple arithmetic differences. By keeping the model tied to observable US deployment and refresh signals, and by using repeatable checks on mix and ASP, the final number stays traceable to clear demand drivers that can be revisited each update cycle.


Key Questions Answered in the Report
What is the current value of the United States data center server market?
The market stands at USD 33.92 billion in 2026 and is forecast to reach USD 50.83 billion by 2031.
Which server application is growing the fastest?
AI and machine-learning workloads show the highest growth at a 15.81% CAGR through 2031.
Why are Tier 4 data centers gaining popularity?
Hyperscalers require fault-tolerant environments for AI training clusters, pushing Tier 4 demand to a 12.79% CAGR through 2031.
How are supply-chain shortages affecting deployment timelines?
Lead times for high-bandwidth memory and GPUs now stretch to twelve months, delaying AI server installations.
Which regions are attracting new data-center investments beyond traditional hubs?
Phoenix, Columbus, and Austin are emerging as preferred tier-2 locations due to land availability, power pricing, and tax incentives.
Page last updated on:
- Artificial Intelligence (AI) Data Center Market AI facilities worldwide, split by facility type, component and tier.
- Data Center Construction Market Global construction demand, split by tier, facility size and facility type.
- United States Data Center Storage Market The US storage, split by storage technology, storage type and end user.
- Japan Data Center Networking Market Networking demand across Japan, covering component.
- Spain Data Center Storage Market Storage in Spain, split by facility size and tier.



