
Saudi Arabia Mineral Processing Equipment Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 198.13 Million |
| Market Size (2026) | USD 215.92 Million |
| Market Size (2031) | USD 331.92 Million |
| Growth Rate (2026 - 2031) | 8.98 % |
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 麻豆视频. Reuse requires attribution under CC BY 4.0. |
|
Saudi Arabia Mineral Processing Equipment Market Analysis by 麻豆视频
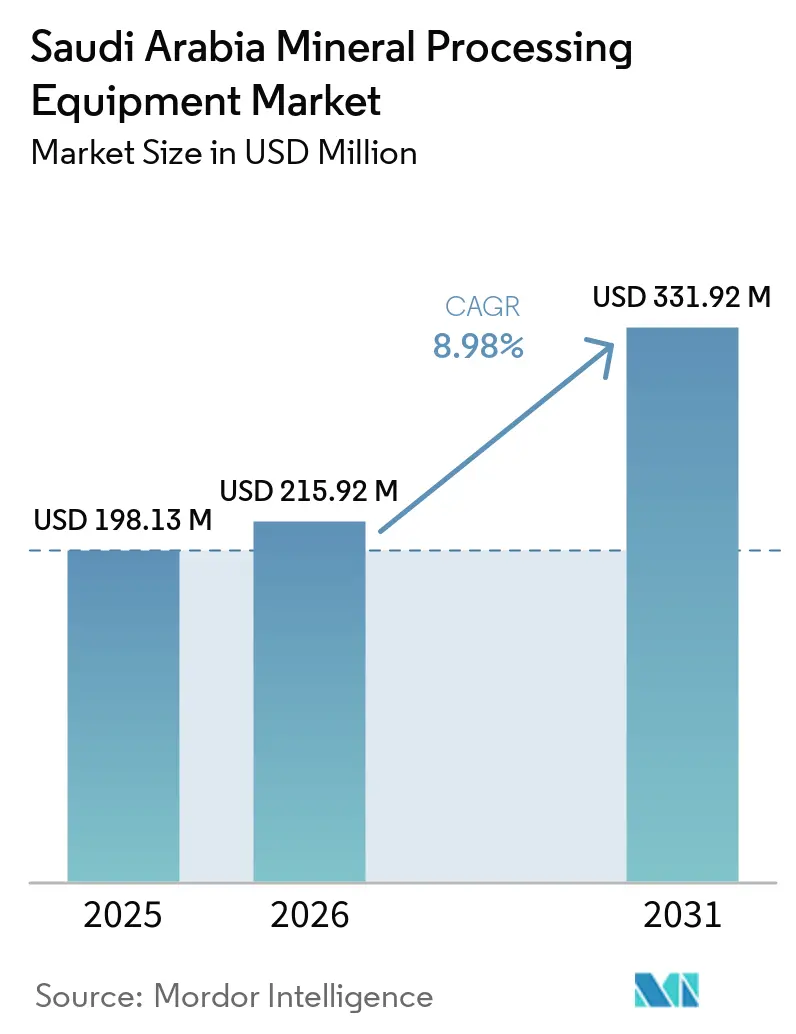
The Saudi Arabia mineral processing equipment market size was valued at USD 198.13 million in 2025, and is expected to increase from USD 215.92 million in 2026 to USD 331.92 million by 2031, growing at a CAGR of 8.98% over 2026-2031. Regulatory incentives under Vision 2030, including in-kingdom total value-added targets and fast-tracked licensing rounds, keep order books healthy for crushers, mills, and automation platforms. Localized manufacturing alliances with global original equipment manufacturers (OEMs) shorten delivery times and help producers meet Saudization quotas. Early adoption of renewable-powered comminution circuits cuts operating costs in remote sites where grid tariffs remain high. Competitive intensity remains moderate because the top five OEMs continue to dominate high-value contracts, while niche suppliers are gaining a foothold in electric drill rigs and digital twin solutions that improve uptime and reduce energy consumption.
Key Report Takeaways
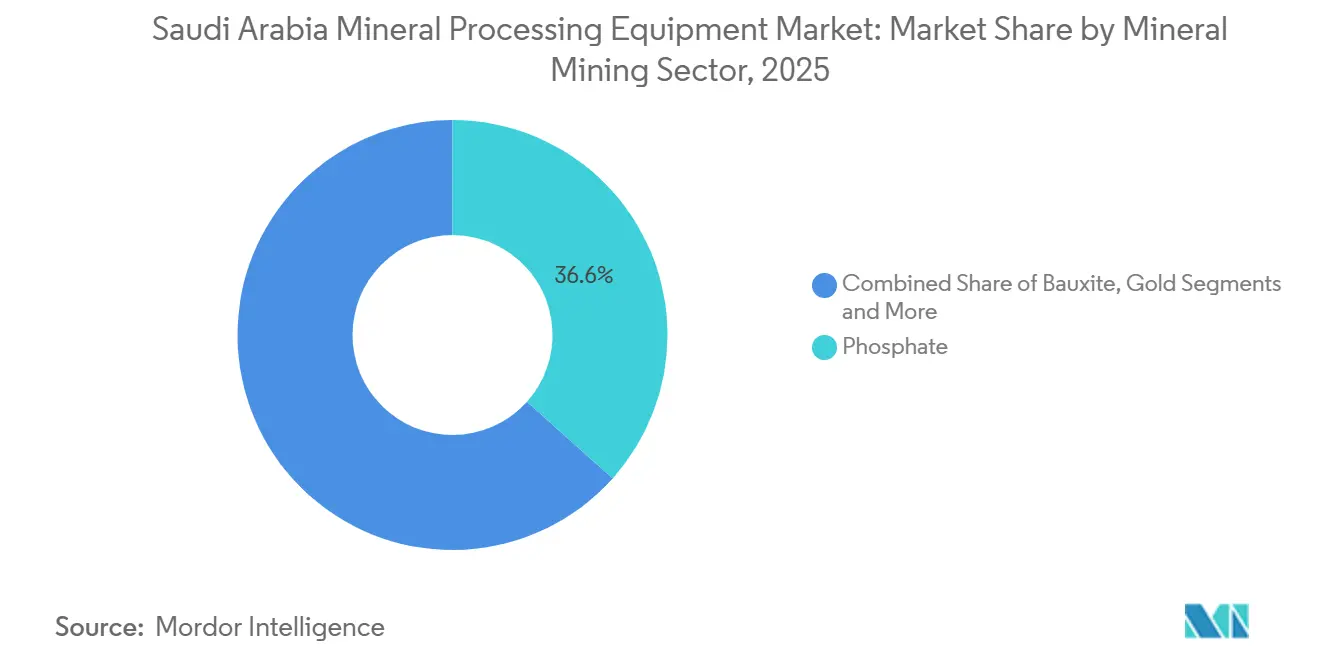
- In the mineral mining sector, phosphate led with a 36.62% share of the Saudi Arabia mineral processing equipment market in 2025, while lithium is projected to expand at a 10.26% CAGR through 2031.
- By equipment type, crushers and mills accounted for 35.38% of the Saudi Arabia mineral processing equipment market in 2025. At the same time, pumps and cyclones are projected to record the highest CAGR, at 9.93% through 2031.
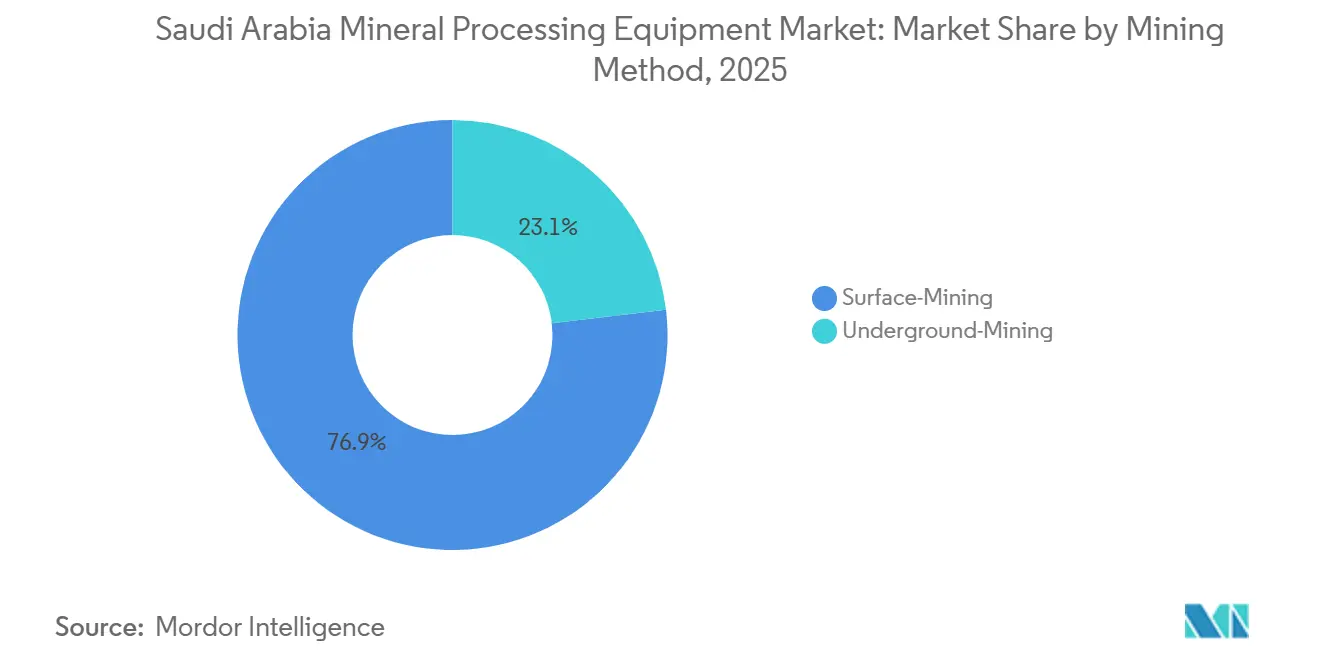
- By mining method, surface operations accounted for 76.87% share of the Saudi Arabia mineral processing equipment market in 2025, while underground mining is projected to post an 11.28% CAGR through 2031.
- By automation level, semi-automated fleets accounted for 53.28% share of the Saudi Arabia mineral processing equipment market in 2025, while fully automated systems are growing at a 14.83% CAGR through 2031.
- By province, Eastern Province accounted for 41.19% share of the Saudi Arabia mineral processing equipment market in 2025, whereas Tabuk Province grew the fastest at an 11.84% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 麻豆视频’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Figures recorded within Saudi arabia feed into a worldwide estimate while studying the global industry. 麻豆视频's mineral processing equipment market size captures this aggregation.
Saudi Arabia Mineral Processing Equipment Market Trends and Insights
Drivers Impact Analysis*
| Driver | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in Extraction Projects | +2.1% | Eastern Province, Northern Borders, Riyadh | Medium term (2-4 years) |
| Downstream-Mining Localization Incentives | +1.8% | Eastern Province, Makkah, Riyadh, Tabuk | Long term (≥ 4 years) |
| Integrated EPC-Mining Contracts | +1.2% | Tabuk, Al-Madinah | Medium term (2-4 years) |
| Crushing and Grinding Circuit Electrification | +0.9% | Eastern Province, Makkah, Tabuk | Short term (≤ 2 years) |
| Predictive-Maintenance Adoption | +0.8% | Eastern Province, Makkah, Riyadh | Short term (≤ 2 years) |
| Ma'aden and JV Exploration Spending | +0.7% | Eastern Province, Tabuk, Makkah, Al-Madinah, Northern Borders | Medium term (2-4 years) |
| Source: 麻豆视频 | |||
Surge in Phosphate and Bauxite Extraction Projects
Ma’aden’s multi-billion-dollar Phosphate 3 build-out lifts demand for bulk-handling and comminution circuits[1]"Ma'aden’s USD 7.4 billion Phosphate 3 project construction work launched", Gulf Construction, gulfconstructiononline.com. A recent renewable power purchase agreement at the Al Baitha bauxite mine signals a shift toward low-carbon equipment that favors electric drives and high-efficiency slurry pumps. Large reserves in the Northern Borders underpin multi-decade procurement cycles, giving OEMs predictable order visibility. EPC contractors specify larger SAG mills to meet rising throughput targets, and the parallel aluminum smelter debottlenecking helps keep downstream demand stable. Together, these projects anchor the Saudi Arabian mineral processing equipment market by ensuring a long runway of capacity additions.
Vision 2030 Downstream-Mining Localization Incentives
IKTVA quotas now apply to mining, obliging foreign OEMs to assemble key modules such as pump casings, cone-crusher heads, and control cabinets locally. Joint ventures signed in 2026 accelerate workforce training, helping to close skills gaps in mechanical and automation engineering. Tax holidays for regional headquarters further encourage OEMs to situate parts hubs in Jubail and Ras Al Khair. Local fabrication trims logistics costs by eliminating import duties and shortening lead times. As compliance scores become bid prerequisites, suppliers with Saudi footprints win a disproportionate share of tenders.
Rise of Integrated EPC-Mining Contracts in NEOM
NEOM’s port, concrete, and green-hydrogen projects pull in sizeable volumes of aggregates, silica, and specialty minerals. Contractors secure long-term quarry leases, spurring orders for mobile crushers and high-capacity screens. Integrated contracts bundle civil works with ore preparation, reducing interfaces and speeding mobilization. This structure favors turnkey vendors that can combine equipment, digital monitoring, and maintenance under one umbrella. Early delivery of crushing trains for “The Line” underscores how mega-projects can swing annual demand in single tenders.
Electrification of Crushing and Grinding Circuits
Switching from diesel gensets to grid or hybrid microgrids reduces fuel bills and helps mines meet carbon border fees in export markets. Grid integration at Jabal Sayid proved that electric jaw crushers and variable-speed drives can stabilize throughput. OEMs now promote modular e-houses and regenerative conveyors that reduce peak power draw. The Ministry’s renewable roadmap, aiming for 50% green electricity by 2030, gives mine planners confidence to specify all-electric comminution lines[2]"The Saudi shift: laying the groundwork for a clean energy future", UNDP, undp.org. Performance guarantees tied to energy intensity increasingly influence tender scoring.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Lengthy Permit Lead-Times | -0.6% | Eastern Province, Makkah, Tabuk, Al-Madinah, Northern Borders | Medium term (2-4 years) |
| Shortage of Certified Engineers | -0.5% | Eastern Province, Makkah, Riyadh, Tabuk | Long term (≥ 4 years) |
| High Grid-Power Tariffs | -0.4% | Tabuk, Northern Borders, Al-Madinah | Short term (≤ 2 years) |
| Import-Dependent Wear Part Lead-Time Delays | -0.3% | Eastern Province, Makkah, Riyadh, Tabuk, Al-Madinah | Short term (≤ 2 years) |
| Source: 麻豆视频 | |||
Lengthy Environmental-Permit Lead-Times
Environmental assessments can extend project schedules by more than a year, making contractors wary of placing early equipment orders. Water scarcity reviews add complexity because many deposits lie in arid zones that require desalination links. Inventory risk rises when mills or pumps arrive before site clearance, tying up capital in laydown yards. OEMs increasingly offer shipment deferral clauses and modular builds to mitigate such delays. Policymakers are digitizing approval workflows, yet on-the-ground progress remains gradual.
Shortage of Certified Automation Engineers
Advanced drill rigs, AI-based predictive maintenance software, and swarm robotics require specialists that the domestic talent pool cannot yet supply in sufficient numbers. Importing expatriates drives up salary overheads, while Saudization quotas limit the number of foreign experts firms can recruit. Universities have expanded mining and mechatronics courses, but graduates will not enter the workforce in large numbers before 2028. Consequently, many operators retain semi-automated fleets longer than technically optimal, tempering the take-up rate of fully autonomous systems.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Mineral Mining Sector: Phosphate Leads, Lithium Gains Momentum
Phosphate accounted for 36.62% of the Saudi Arabian mineral processing equipment market in 2025, supplying material for exports of diammonium and monoammonium phosphate. Producers favor large rotary kilns and high-throughput rock crushers that match rising fertilizer capacity. Attractive geology and established logistics keep capital flowing into expansion phases, locking in base-load demand for screens, feeders, and tailings pumps. Although lithium currently represents a smaller segment, it is projected to register the fastest CAGR at 10.26%, driven by brine-extraction pilots and plans to produce battery-grade hydroxide. This growth is increasing demand for hydrometallurgical pumps, ion-exchange columns, and fine-grinding mills optimized for clay-hosted ores.
Phosphate operators now incorporate solar power and filtered tailings, creating openings for dewatering presses and energy-efficient agitators. Long-cycle phosphate contracts offer OEMs annuity-like aftermarket revenue because rock hardness requires frequent liner and screen panel replacements. Lithium developers adopt modular plant layouts to scale production quickly, a trend that benefits suppliers of skid-mounted columns and plug-and-play control rooms. Together, these dynamics position the Saudi Arabian mineral processing equipment market as a two-track landscape in which mature phosphate output funds the transition to energy-transition minerals.


By Equipment Type: Crushers Dominate, Pumps Accelerate
Crushers and mills accounted for 35.38% of the Saudi Arabia mineral processing equipment market in 2025, as nearly every ore passes through primary and secondary comminution. Fixed-jaw units handle phosphate and bauxite, while high-pressure grinding rolls gain market share in gold pre-concentration. Suppliers differentiate on wear-part metallurgy and digital health sensors that flag liner changeouts before failure. Pumps and cyclones grow at a brisk 9.93% CAGR as lithium, copper, and rare-earth flowsheets rely on dense-media separation and leaching, which involve circulating corrosive slurries.
Large slurry pumps now ship with ceramic or rubber liners to extend maintenance intervals in high-solid circuits. Variable-speed drives fine-tune cyclone feed pressure, boosting recovery in finely disseminated deposits. Sustainability metrics favor pumps with lower specific energy consumption, prompting OEMs to redesign impellers for greater hydraulic efficiency. Across both categories, fleet-wide condition monitoring feeds into mine-wide digital-twin dashboards, raising the bar for sensor integration and data interoperability.
By Mining Method: Surface Dominance, Underground Upswing
Surface operations accounted for 76.87% of the Saudi Arabian mineral processing equipment market in 2025, as open-pit phosphate, bauxite, and gold projects dominate installed capacity. Contractors deploy autonomous blast-hole rigs and 200-t haul trucks to lift productivity while meeting strict safety codes. Slope stabilization and waste-dump management require high-angle conveyor systems that reduce diesel truck runs. Underground mining, forecast to climb 11.28% CAGR, gains traction as copper and polymetallic orebodies on the Arabian Shield move below the oxidation zone.
The underground shift drives demand for battery-electric load-haul-dump units and cable-bolting rigs that slash ventilation loads. Mines are adopting paste-fill plants to maximize ore extraction from narrow pillars, which increases demand for high-shear mixers and progressive-cavity pumps. Training simulators and remote operation centers become standard, ensuring that productivity gains from mechanization offset the higher capital intensity underground.
By Automation Level: Semi-Automated Transition Toward Full Autonomy
Semi-automated fleets accounted for 53.28% of the Saudi Arabian mineral processing equipment market in 2025 as miners retrofit legacy machines with collision-avoidance and GPS navigation systems. These upgrades deliver quick wins without the steep upfront costs of full autonomy. However, fully autonomous systems are racing ahead at a 14.83% CAGR, propelled by AI-driven fleet management platforms that enable 24-hour operations with minimal downtime.
OEMs now package autonomous drill rigs with cloud-hosted analytics that predict component fatigue and schedule maintenance during shift changes. Hybrid powertrains reduce greenhouse gas intensity, helping operators meet offtake agreements that factor in embedded carbon. As fiber and 5G coverage expand around mine hubs, latency drops, making centralized remote-control rooms a practical alternative to on-site operation.
Geography Analysis
Eastern Province accounted for 41.19% of the Saudi Arabian mineral processing equipment market in 2025, owing to integrated phosphate and aluminum complexes linked to export terminals. Well-established logistics corridors enable OEMs to ship oversized mills and transformers via dedicated ports, thereby reducing transit complexity. Local contractors enjoy economies of scale through shared fabrication yards that churn out conveyor trusses and crusher spares. Training centers in Jubail graduate technicians versed in predictive-maintenance software, making the province a talent magnet. Abundant renewable projects feed low-cost power into mining clusters, encouraging the electrification of comminution circuits and drawing further investment into the mineral processing equipment market in Saudi Arabia.
Makkah province trails closely behind due to gold projects such as Ar Rjum, which rely on carbon-in-leach tanks, gravity concentrators, and high-intensity grinding mills. The terrain’s higher altitude necessitates robust haul-truck drivetrains and air-cooled electric motors that handle temperature swings. Contractors leverage proximity to major highways to deliver oversized plant modules, reducing the need for on-site stick-built construction. The provincial administration fast-tracks road upgrades that cut haulage times for ore and consumables alike. Investment in local assay labs simplifies sample turnaround, fostering a supportive ecosystem for exploration drilling service providers.
Tabuk province, projected to post an 11.84% CAGR, benefits from NEOM-related infrastructure that calls for high-spec aggregates and specialty silica. Tabuk’s frontier deposits in tantalum and rare earths necessitate fine-grinding mills and magnetic separators not yet common in the domestic fleet. OEMs are setting up quick-response service outposts near NEOM to meet aggressive construction schedules. This two-province dynamic creates a balanced market where established hubs guarantee steady volumes and frontier regions deliver growth.
麻豆视频 evaluates the mineral processing equipment market with deeper country-level insights covering France, Spain, China, Canada, Germany, South Korea, Argentina, Turkey, and Japan.
Competitive Landscape
A handful of global OEMs dominate high-value tenders, yet market concentration stays moderate because specialized players fill technology niches. Multinational suppliers cement their edge by establishing joint ventures to localize pump casings, crusher frames, and control panels, thereby meeting IKTVA thresholds and slashing import duties. Domestic assemblers gain access to proprietary designs while OEMs secure rapid-response service capacity, a decisive advantage in tight production windows.
Product strategies increasingly revolve around digital twins and energy efficiency. Vendors embed vibration sensors and thermal cameras in mills and slurry pumps, feeding data into cloud analytics that recommend maintenance before catastrophic failure. Electric and diesel-electric hybrid trucks move from pilot to limited-commercial rollout, supported by commitments to expand grid capacity near mine clusters. Early mover advantage accrues to firms offering bundled hardware, software, and operator-training packages under performance-based contracts.
Price-based competition persists in lower-tier segments such as mobile jaw crushers for small quarries, where emerging Asian brands undercut established players. However, stringent uptime clauses in mega-project contracts favor OEMs with demonstrable reliability records. Warranty extensions, consignment stock near mine gates, and technician secondment arrangements become standard deal sweeteners. Environmental, social, and governance metrics now factor into award decisions, favoring suppliers that can certify reduced carbon and water footprints across product lifecycles.
Saudi Arabia Mineral Processing Equipment Industry Leaders
-
Metso Outotec
-
FLSmidth A/S
-
Weir Group PLC
-
Sandvik AB
-
Thyssenkrupp Industrial Solutions
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- July 2026: Saudi Readymix deployed Saudi Arabia’s first fully battery-electric wheel loader, supplied by XCMG. The loader has operated successfully through consecutive summer cycles in temperatures exceeding 50°C, validating the thermal performance of electrified heavy machinery in raw mineral processing operations under harsh desert conditions.
- March 2026: Ma’aden and Hatch agreed to accelerate the deployment of sustainable engineering solutions for Ma’aden’s upcoming phosphate and aluminum projects, supporting efficient project development and sustainability objectives.
- February 2026: Metso commissioned the first Nordberg HP350e cone crushers in Saudi Arabia’s Western Region, marking an important deployment of the company’s latest cone crushing technology in the region. The crushers feature 250 kW motors and are designed to deliver lower energy consumption per ton while supporting efficient crushing operations.
- January 2026: Metso secured a USD 148.6 million contract from Ma’aden to supply a complete gold-processing plant. The project scope includes the delivery of grinding mills and thickeners, which are key components of the gold-processing plant.
- November 2025: FABO commissioned a 1,000 t/h crushing and screening plant for NEOM, designed to efficiently process large volumes of aggregates and meet the project's stringent aggregate production volume targets.


Saudi Arabia Mineral Processing Equipment Market Report Scope
The Saudi Arabia Mineral Processing Equipment market is analyzed across the mineral mining sector, equipment type, mining method, automation level, and province. By Mineral Mining Sector, the market is segmented into Phosphate, Bauxite, Gold, Iron Ore, Copper, Lithium, and Others. By Equipment Type, the market is segmented into Crushers & Feeders, Screens & Grinding Mills, Conveyors, Pumps & Centrifuges, Drills & Breakers, and Others. By Mining Method, the market is segmented into Surface Mining and Underground Mining. By Automation Level, the market is segmented into Manual, Semi-Automatic, and Fully Autonomous. By Province, the market is segmented into Eastern Province, Makkah, Riyadh, Tabuk, Al-Madinah, and Others. Market forecasts are provided in terms of Value (USD).
| Phosphate |
| Bauxite |
| Gold |
| Iron Ore |
| Copper |
| Lithium |
| Others |
| Crushers & Mills |
| Screens & Feeders |
| Conveyors |
| Pumps & Cyclones |
| Drills & Breakers |
| Others |
| Surface Mining |
| Underground Mining |
| Manual |
| Semi-Automated |
| Fully Automated |
| Eastern Province |
| Makkah |
| Riyadh |
| Tabuk |
| Al-Madinah & Others |
| By Mineral Mining Sector | Phosphate |
| Bauxite | |
| Gold | |
| Iron Ore | |
| Copper | |
| Lithium | |
| Others | |
| By Equipment Type | Crushers & Mills |
| Screens & Feeders | |
| Conveyors | |
| Pumps & Cyclones | |
| Drills & Breakers | |
| Others | |
| By Mining Method | Surface Mining |
| Underground Mining | |
| By Automation Level | Manual |
| Semi-Automated | |
| Fully Automated | |
| By Province | Eastern Province |
| Makkah | |
| Riyadh | |
| Tabuk | |
| Al-Madinah & Others |


Key Questions Answered in the Report
What is the value of the Saudi Arabia Mineral Processing Equipment Market in 2026 ?
The Saudi Arabia mineral processing equipment market size was valued at USD 198.13 million in 2025, and is expected to increase from USD 215.92 million in 2026 to USD 331.92 million by 2031, growing at a CAGR of 8.98% over 2026-2031.
Which province buys the most processing machinery?
Eastern Province leads, anchored by integrated phosphate and aluminum complexes that continually upgrade comminution and conveying assets.
How fast is underground mining equipment spending growing?
Underground equipment posts an 11.28% CAGR to 2031 as copper and polymetallic deposits on the Arabian Shield move deeper.
Why is lithium noteworthy despite its small base?
Lithium shows the fastest 10.26% CAGR because brine-extraction pilots and battery-grade conversion plants are scaling in line with energy-transition goals.
What technologies cut operating costs in remote sites?
Electrified crushing circuits, variable-speed pump drives, and AI-based predictive-maintenance platforms lower fuel and downtime expenses.
Page last updated on:



